


EN
Should Mixed Earnings Require Action From Open Text Stock Investors?
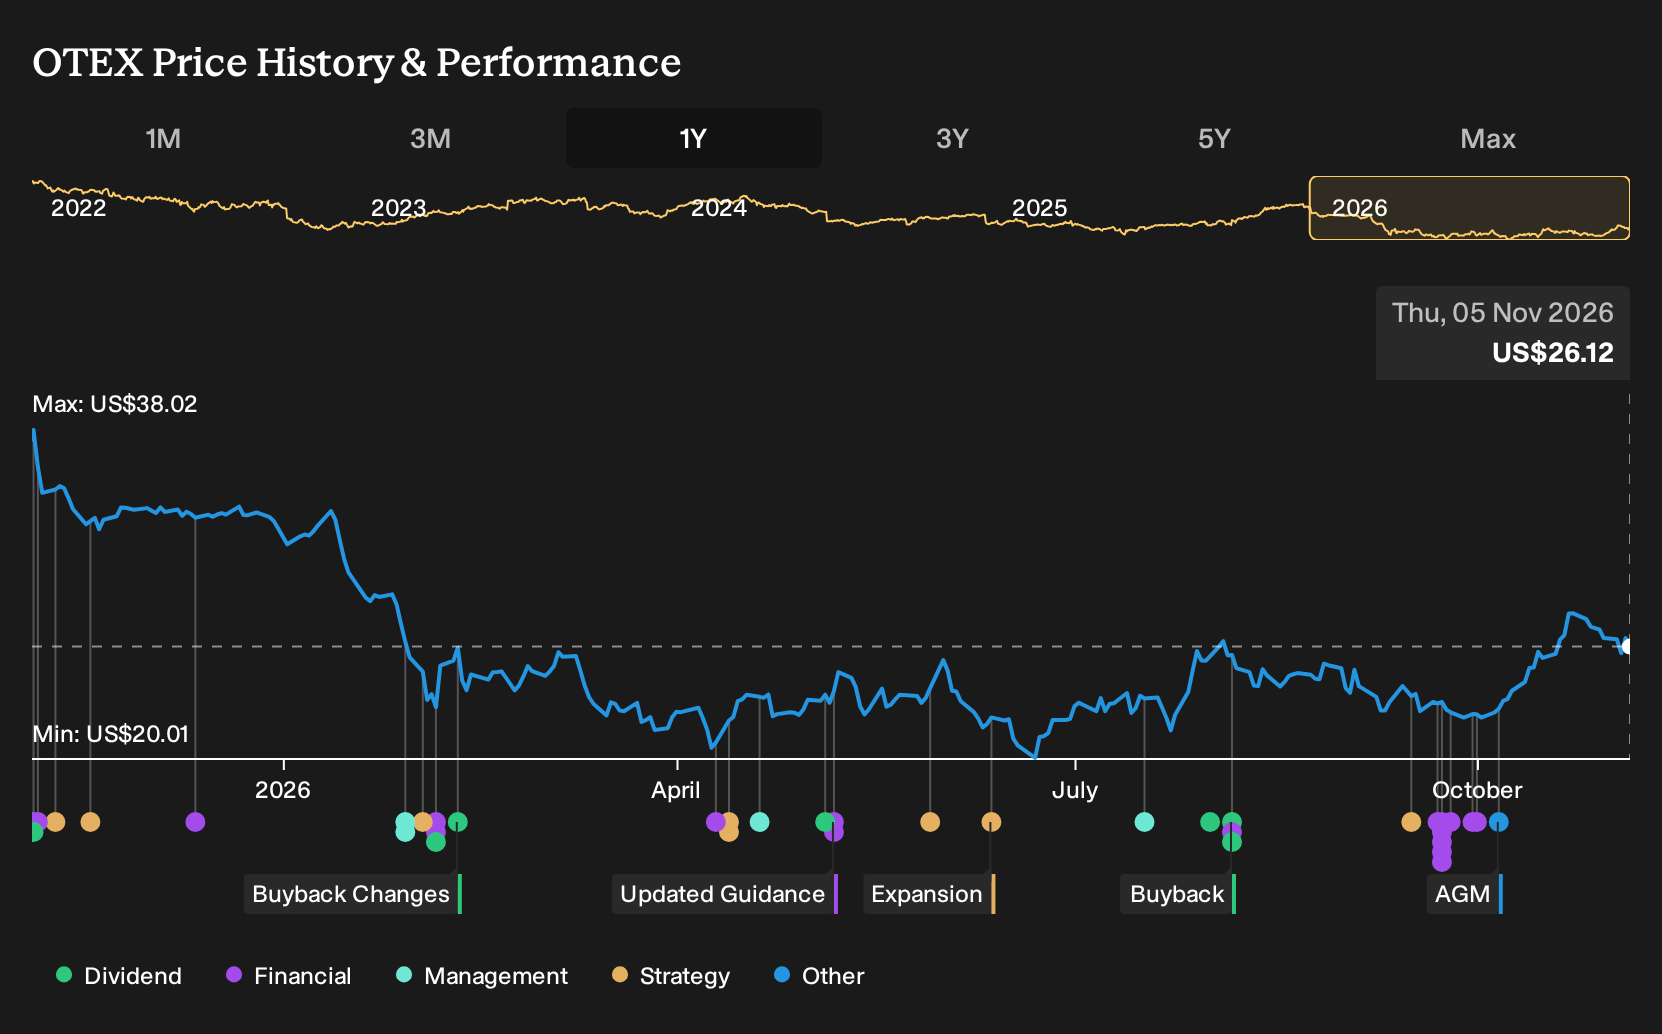
- Open Text reported first quarter results for the period ended September 30, 2026, with revenue of US$1,236.63 million, net income of US$155.25 million and diluted EPS from continuing operations of US$0.64.
- The Board kept its cash return program in motion with a non cumulative quarterly dividend of US$0.280 per common share, signaling a continued focus on distributing part of earnings even as revenue moved lower year on year.
- The next step is to examine how Open Text's softer revenue but higher earnings per share could reshape the investment narrative around profitability.
Open Text Investment Narrative Recap
To own Open Text, you need to believe the move toward cloud based, AI centric information management keeps gaining traction while the drag from legacy on premise products stays manageable. This quarter’s softer revenue but higher earnings per share underlines that cost discipline and mix shift are doing some work, even as top line momentum remains muted.
In the near term, the key swing factor is whether the cloud and AI upsell, together with the rebuilt go to market engine, can translate into healthier bookings without eroding margins more than planned. The main risk is that declining legacy streams and heavy FY27 investment keep overall revenue sluggish for longer.
The reaffirmed quarterly dividend of US$0.280 per share is the announcement that ties closest to this update. It highlights that Open Text is still committing cash to shareholders at the same time it reports net income of US$155.25 million on a smaller revenue base of US$1,236.63 million.
For you as an investor, that payout interacts directly with the firm’s balance sheet and investment plans. Capital returns can appear attractive when the stock trades on a lower P/E and offers a 4.29% yield, yet they also limit how quickly debt can be reduced if operating cash flow tightness persists or growth investments take longer to pay off.
Open Text's analyst narrative points to revenues of US$5.2b and earnings of US$638.3 million by 2029. This outlook is built on a view that revenue stays fairly flat while profit margins slip slightly and earnings ease by about US$4.7 million from US$643.0 million today.
Uncover why Open Text's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Open Text leans hard into margin risk. The lowest analyst group expected earnings to slide from US$643.0 million to about US$508.9 million by 2029 on revenue around US$5.2b, even before this quarter’s softer sales and steady dividend. As a result, you may see those more pessimistic narratives evolve, so it can be useful to compare several angles yourself.
Explore 3 other Open Text fair value estimates, including one that suggests it could be worth just $27.95.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Open Text research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Open Text. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Open Text's overall financial health at a glance.
Looking for more investment ideas beyond Open Text?
If the Open Text story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you zero in on other stocks that fit your risk tolerance and style.
- For investors who care most about resilience and capital preservation, filter for 32 resilient stocks with low risk scores that aim to keep downside in check while still participating in market upside.
- If you prefer businesses with strong finances and less reliance on external funding, focus on a list of solid balance sheet and fundamentals (24 results) that can better support dividends, buybacks, or reinvestment.
- Readers hunting for mispriced opportunities can scan our 42 high quality undervalued stocks where fundamentals and current valuations may not fully line up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com