


EN
Earnings Guidance Raised Might Change The Case For Investing In Sirius XM Stock
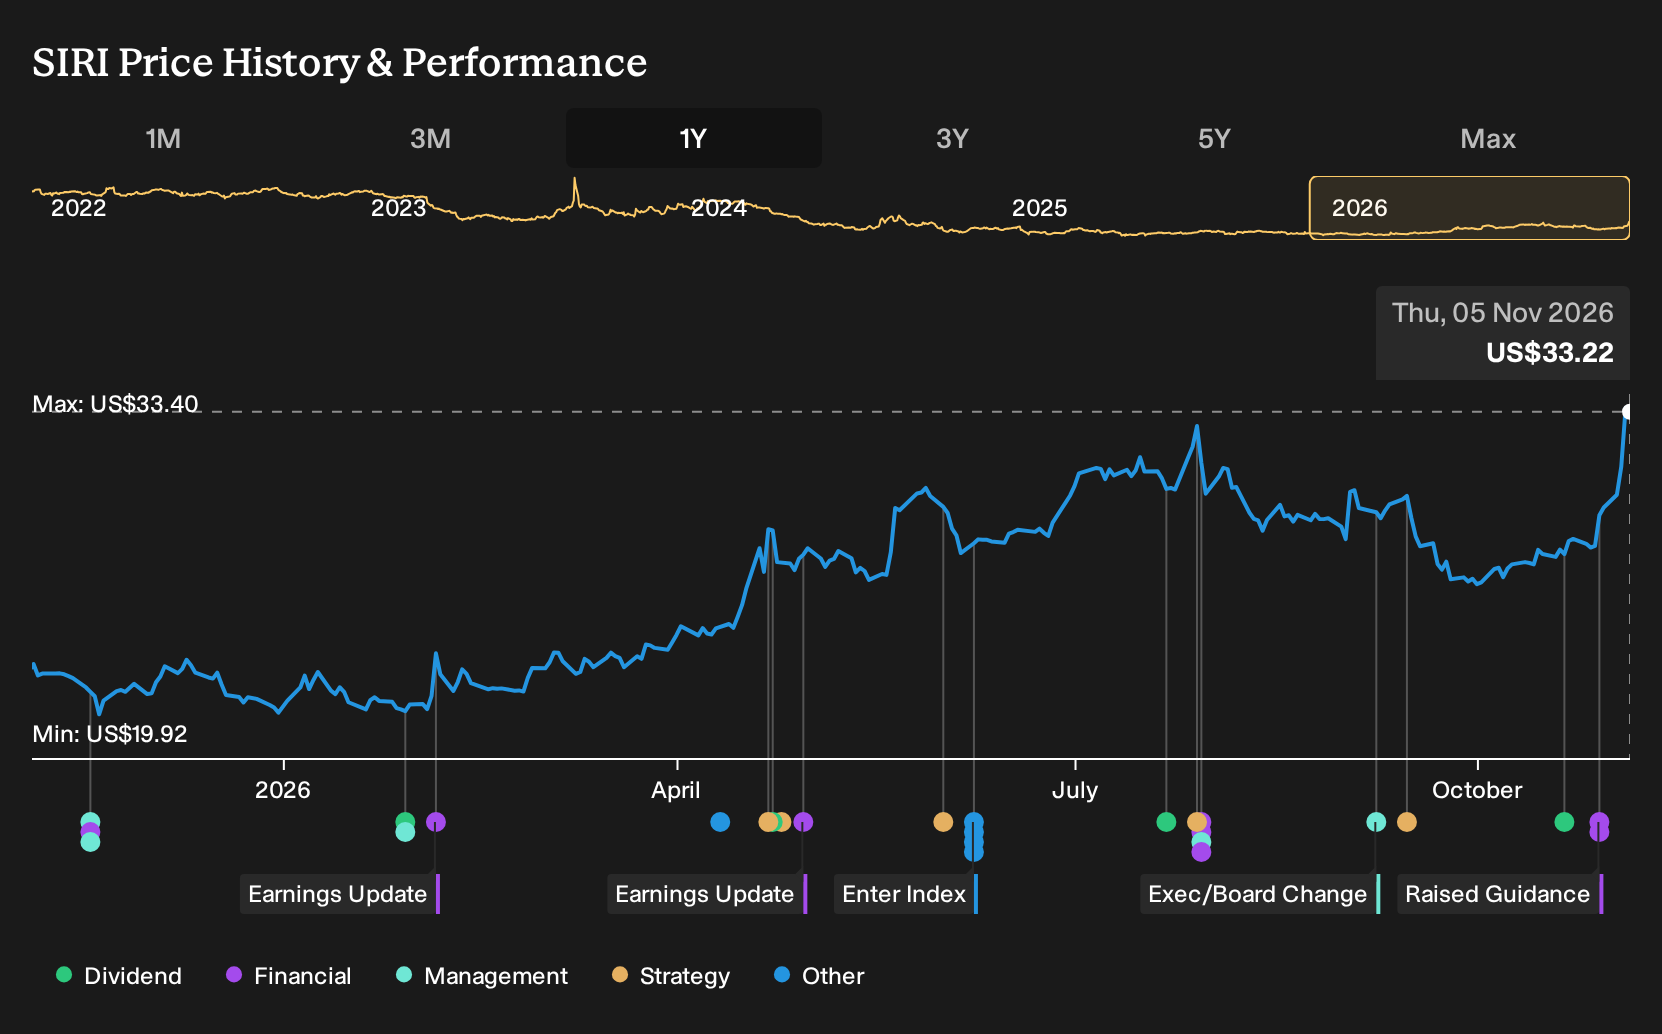
- Sirius XM Holdings reported third quarter 2026 revenue of US$2,153 million, net income of US$317 million, and raised full year 2026 guidance to about US$8.55 billion in revenue.
- The mix of broadly stable sales with higher net income and stronger earnings per share indicates tighter cost control and healthier profitability for Sirius XM Holdings.
- The next area of focus is how Sirius XM Holdings' higher full year earnings guidance might influence the existing investment narrative.
Scan beyond Sirius XM Holdings and compare other audio and media stocks that emphasize disciplined cost control, using our hand picked 21 high quality undiscovered gems as a starting list.
Sirius XM Holdings Investment Narrative Recap
For Sirius XM Holdings to make sense in a portfolio, you need to be comfortable with a relatively slow growing top line and a core thesis built around efficiency, sticky subscribers, and incremental monetization of audio content. The raised 2026 earnings guidance supports that story, since it points to the business squeezing more profit out of a largely stable revenue base.
The key near term swing factor is whether cost discipline and cross platform engagement can offset pressure from streaming competitors and any subscriber churn. The biggest risk remains muted revenue momentum and a high debt load. This update is helpful for confidence, but it does not remove those concerns.
The most relevant update is the new full year target of about US$8.55b in revenue with higher earnings guidance. That outlook is based on third quarter revenue of US$2,153 million and net income of US$317 million, with earnings per share from continuing operations varying between basic and diluted figures.
For you as a shareholder, the question is whether this guidance signals durable execution on cost efficiencies, digital audio advertising, and subscriber monetization, or simply reflects one good stretch of tighter spending. It also directly interacts with the risk that revenue growth stays muted, which could limit how much benefit investors assign to these improved earnings.
Sirius XM Holdings' current analyst narrative points to about US$9.2b in revenue and US$1.2b in earnings by 2029, based on assumed 2.1% yearly revenue growth and an earnings increase of roughly US$320m from about US$880m today.
Uncover why Sirius XM Holdings' fair value is essentially in line with its current price.
Exploring Other Perspectives
You might see Sirius XM Holdings differently if you focus on the bullish catalyst around digital audio advertising. The most optimistic analysts were already penciling in about US$10.3b of revenue and US$1.3b of earnings by 2029 before this guidance change. Those forecasts reflect a far more upbeat story than consensus, and this new information could nudge those narratives again.
Explore 7 other Sirius XM Holdings fair value estimates, including one that suggests as much as 44% potential increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Sirius XM Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sirius XM Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sirius XM Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sirius XM Holdings?
If Sirius XM Holdings has sharpened your thinking about efficiency, income potential, and risk, it can be useful to compare that perspective with other businesses that have very different profiles. The Simply Wall St Screener lets you quickly filter for traits that match your own priorities, whether that is resilience, income, or unrecognised quality.
- If you care most about stability and capital protection, start with companies that score well on balance sheet strength through our list of solid balance sheet and fundamentals (24 results).
- Income focused investors can focus on businesses that combine higher yields with consistency by reviewing the 6 dividend fortresses.
- Those who want mispriced quality can search for under followed businesses that still have solid fundamentals using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com