


EN
Amphastar Pharmaceuticals (AMPH) On Q3 Results Faces An Overvalued Narrative
Amphastar Pharmaceuticals (AMPH) just put fresh Q3 2026 numbers on the table, with management reporting higher quarterly sales, net income, and earnings per share compared with the same period last year.
Amphastar Pharmaceuticals shares have been on a strong run into this earnings release, with a 90 day share price return of 33.11% and a 1 year total shareholder return of 14.16%. However, the 3 year total shareholder return declined 47.22%, showing that recent momentum has only partly offset earlier weakness.
Scan how Amphastar Pharmaceuticals compares to other potential breakout healthcare names using our hand picked screener of 34 healthcare AI stocks as a starting universe.
Amphastar Pharmaceuticals just surged on strong Q3 figures; however, the shares now trade above the average analyst target while screens flag a wide discount to estimated fair value. Is the market being too cautious or appropriately blunt?
Most Popular Narrative: 23% Overvalued
Amphastar Pharmaceuticals last closed at $27.66, while the most followed narrative pegs fair value closer to $22.50 using a 7.24% discount rate. That gap puts the recent rally against a storyline that already assumes earnings progress but less room for missteps.
The current valuation implies investors are paying a premium for Amphastar Pharmaceuticals despite slowing two year revenue growth and compressed operating margins, which aligns with the view that the stock may be overvalued and exposed if execution disappoints.
See why 30 investors see Amphastar Pharmaceuticals as 23% overvalued.
Result: Fair Value of $22.50 (OVERVALUED)
Still, Amphastar Pharmaceuticals could challenge this overvaluation view if newer respiratory and injectable products broaden earnings support, or if upcoming insulin and peptide programs gain meaningful traction.
Find out about the key risks to this Amphastar Pharmaceuticals narrative.
Another View: Amphastar Pharmaceuticals Through The P/E Lens
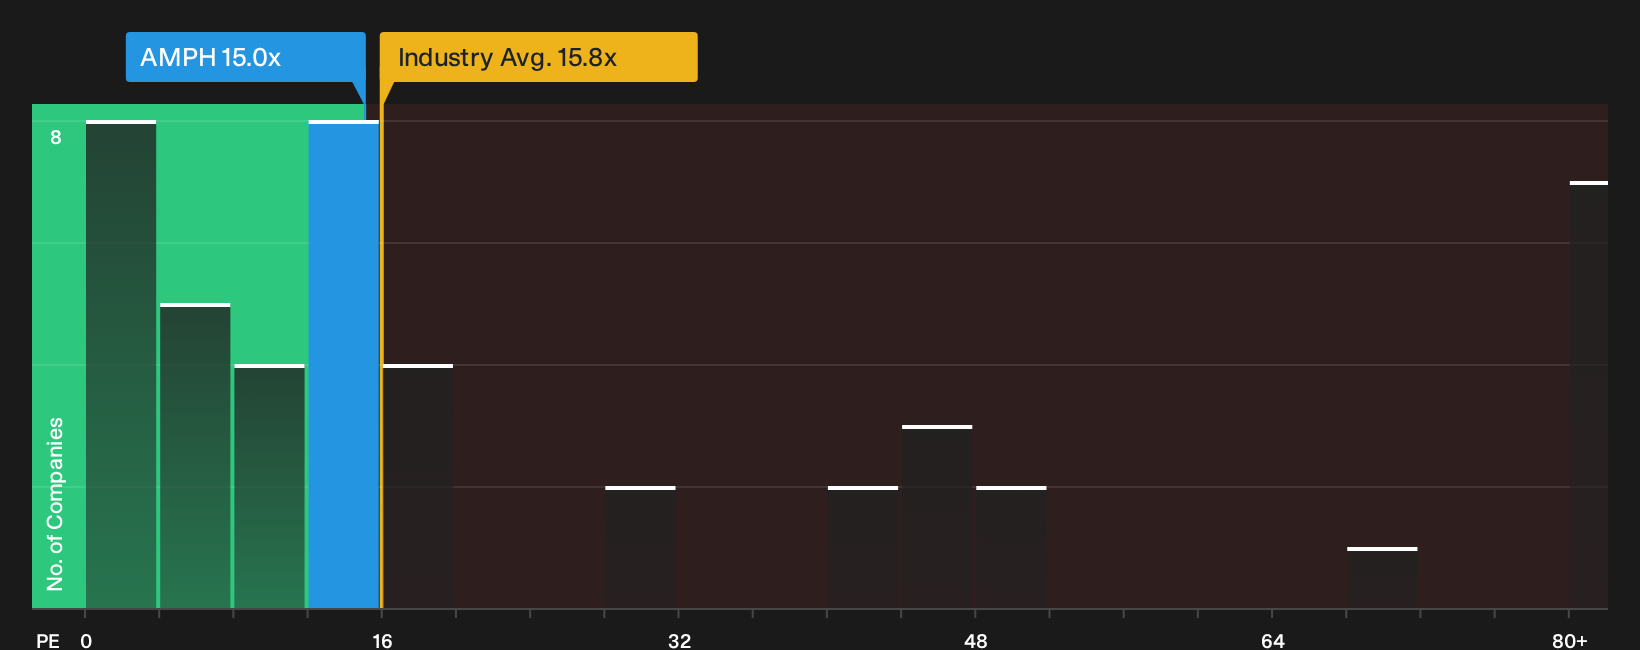
The first narrative frames Amphastar Pharmaceuticals as roughly 23% overvalued against a fair value of $22.50. A simple P/E check tells a softer story. At 15x earnings, AMPH trades slightly below the US pharmaceuticals group on 16.1x and well under peer averages near 34.3x, yet just above its own fair ratio of 14.1x. That mix of modest premium to fair ratio but discount to many rivals raises a practical question for investors. Is this pricing a small overpay for perceived quality, or a margin of safety if earnings prove steadier than feared?
To see what the numbers say about this price in more detail, have a look at our valuation breakdown for Amphastar Pharmaceuticals via See what the numbers say about this price — find out in our valuation breakdown..
For a clearer sense of how Amphastar Pharmaceuticals' current earnings multiple stacks up against its industry peers, review the latest comparison chart here
Next Steps
Mixed signals on Amphastar Pharmaceuticals so far. If you want to move quickly and firm up your own stance, start by weighing the 2 key rewards and 3 important warning signs 2 key rewards and 3 important warning signs
Looking for more Amphastar Pharmaceuticals sized ideas?
If Amphastar Pharmaceuticals has sharpened your focus, do not stop here. Broaden your watchlist with other clear, data driven ideas sourced from the Simply Wall St screener.
- Target resilient potential compounders by scanning a curated 42 high quality undervalued stocks that pair quality fundamentals with pricing that still leaves room for your own conviction to matter.
- Prioritize staying power by focusing on a list of solid balance sheet and fundamentals (24 results) so short term noise is less likely to derail your long term plan.
- Get early to quieter opportunities by reviewing a 21 high quality undiscovered gems before they sit firmly on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com