


EN
Primo Brands (PRMB) Stock May Be Pricey On Third Quarter Results
Primo Brands has rewarded shareholders with a strong multi year run, so the obvious question now is whether the current share price still lines up with what its earnings can justify. With the stock near US$22 and recent momentum in the background, the focus turns to how much profit power the business is being priced for today.
- Primo Brands has returned 62.9% over the past 3 years, which puts real pressure on the earnings story to support that kind of share price progress.
- The latest update on net sales growth, a new US$300m repurchase plan and an ongoing dividend may support expectations for steadier cash generation and capital returns that feed directly into what investors are willing to pay per dollar of earnings.
- The analysts covering Primo Brands have run their own numbers. See what analysts think Primo Brands's shares could be worth.
The stock's next move may depend on whether Primo Brands' current earnings level and trajectory are enough to make today's valuation look reasonable on an earnings basis.
If you want a second reference point alongside Primo Brands, a focused stock screen can help surface other ideas that fit clear criteria such as 42 high quality undervalued stocks.
Does Primo Brands Look Pricey on Earnings?
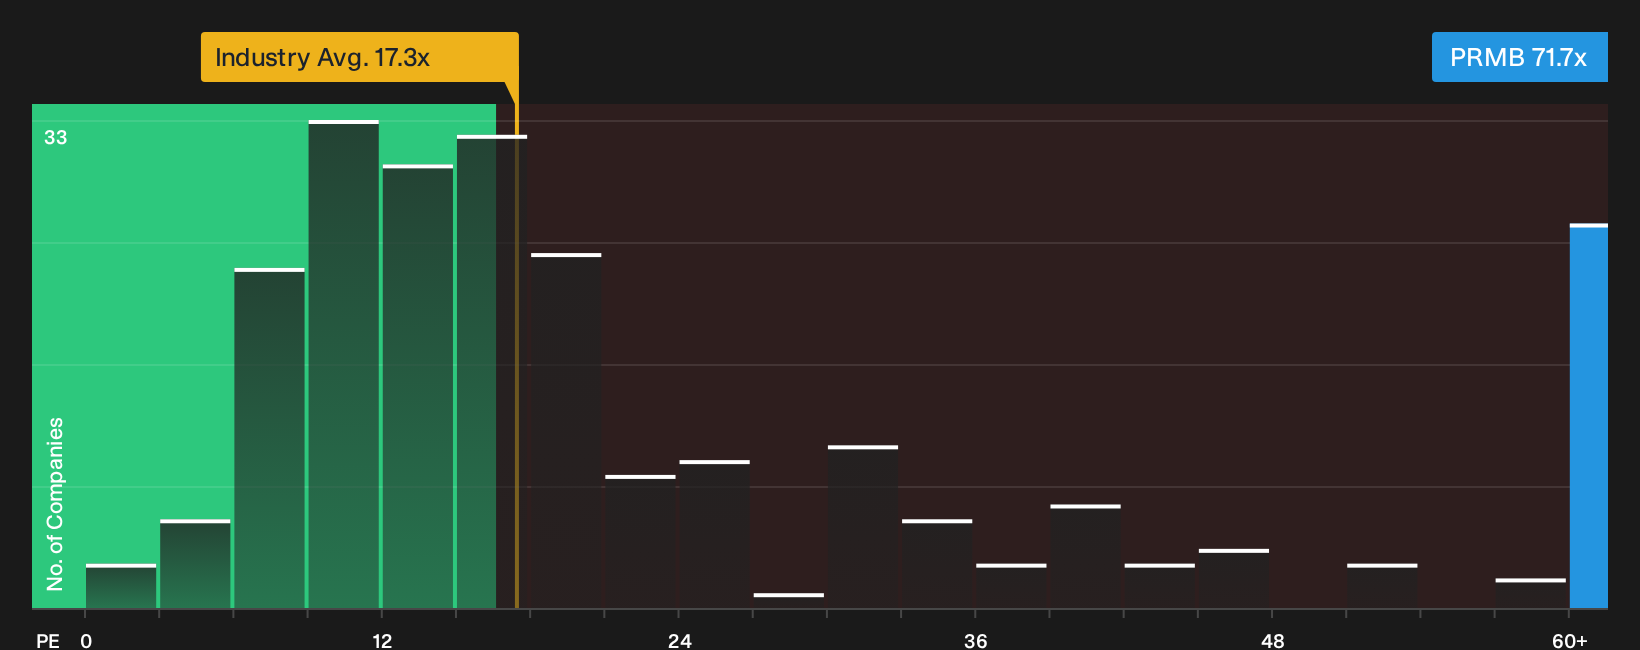
The P/E ratio suits Primo Brands because earnings sit at the center of how many investors think about this business. At around 71.7x earnings, the stock trades at a much richer multiple than the wider Beverage industry, which sits near 17.3x. It also prices in a clear premium to the peer group average of about 47.5x. That gap means each dollar of Primo Brands' profit is currently valued far higher than the sector norm.
Because the valuation sits this far above industry and peer benchmarks, the shares screen as overvalued on a straightforward earnings basis. The recent third quarter update, which included 3.1% net sales growth and a fresh US$300m buyback alongside a US$0.12 dividend, may help explain why investors are comfortable paying up for Primo Brands today. It also raises the bar for what future profit delivery needs to look like to support this kind of P/E multiple. Explore the numbers behind Primo Brands's P/E valuation.
The Primo Brands Narrative: What Would Justify Today's Price?
Narratives on Primo Brands pick up where the P/E question leaves off, by laying out what kind of future growth, profitability and earnings profile would need to play out for the stock to look materially cheaper or more expensive than it does today on Simply Wall St's Community page. Instead of stopping at a single ratio or model output, Narratives unpack the future that those numbers rely on so you can watch in real time whether that path is actually taking shape.
Community views on Primo Brands are split between those who see more upside left and those who think most of the story is already reflected in the share price.
Bull case: 25% undervalued
"Expanding production capacity for high growth premium brands like Mountain Valley and Saratoga through new facilities in Arkansas and Texas may help unlock constrained demand..."
Discover why this Narrative puts Primo Brands at 25% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect Primo Brands to struggle to rebuild direct delivery profitability as higher route counts, logistics costs and still-recovering volumes continue to weigh on margins..."
Explore why this Narrative puts Primo Brands at roughly fairly valued.
Primo Brands’ price is only one piece of the investment puzzle
Valuation tells you what investors are paying for Primo Brands today, but the research checks also flag specific risk signals that could tilt the balance of the investment case. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com