


EN
AbbVie (ABBV) Raises Guidance And Dividend On A Valuation That Still Divides
AbbVie guidance boost and dividend move draw fresh investor focus
AbbVie (ABBV) has just paired a higher full year outlook with a dividend increase and a run of positive drug updates, giving investors fresh information to reassess the stock after third quarter results.
Recent trading shows that AbbVie’s share price has climbed strongly over the past few months, with a 30 day share price return of 8.08% and a 90 day move of 17.15%. The 1 year total shareholder return of 35.53% and 5 year total shareholder return of 195.17% point to momentum that has attracted fresh attention around the latest earnings beat, guidance upgrade, dividend increase and a series of positive drug and licensing announcements.
Scan other healthcare names seeing similar interest to AbbVie’s latest guidance and dividend move by checking our curated list of 34 healthcare AI stocks.
After a jumpy few months for AbbVie and a fresh uplift in guidance, the share price now sits close to analyst targets while some fair value models still flag a much wider discount. Which reference point deserves more weight?
Price-to-earnings of 49.5x on AbbVie: Is it justified?
Valuation signals around AbbVie are mixed. The SWS DCF model points to a future cash flow value of $411.90 per share, while the last close sits at $288.24 and the stock trades on a P/E of 49.5x that is above both peers and the modelled fair P/E level.
The P/E ratio tracks how much investors are paying today for each dollar of AbbVie’s earnings. A 49.5x multiple indicates the market is paying a high price for current profit, especially when set against the US Biotechs industry average of 16.9x and a peer group average of 45.9x.
That premium suggests investors are pricing in strong earnings power and are willing to pay more for AbbVie’s profit stream than for typical biotech stocks. The estimated fair P/E of 47.9x sits slightly lower than the current multiple. This signals a level the market could move toward if sentiment or growth expectations cool from here.
Against the wider sector, the gap is even clearer. AbbVie’s 49.5x P/E is far above the 16.9x industry average. This points to a stock that is richly valued compared with many biotech peers that operate under similar regulatory and competitive conditions.
Explore the SWS fair ratio for AbbVie.
Result: Price-to-earnings of 49.5x (OVERVALUED)
Still, any slip in AbbVie’s drug pipeline progress, or a reset in earnings expectations, could quickly challenge the rich P/E and fair value narrative.
Find out about the key risks to this AbbVie narrative.
Another view on AbbVie’s value
The high 49.5x P/E paints AbbVie as expensive, yet the SWS DCF model points to future cash flows worth $411.90 per share against a current price of $288.24. That 30% gap frames AbbVie as undervalued on this lens. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
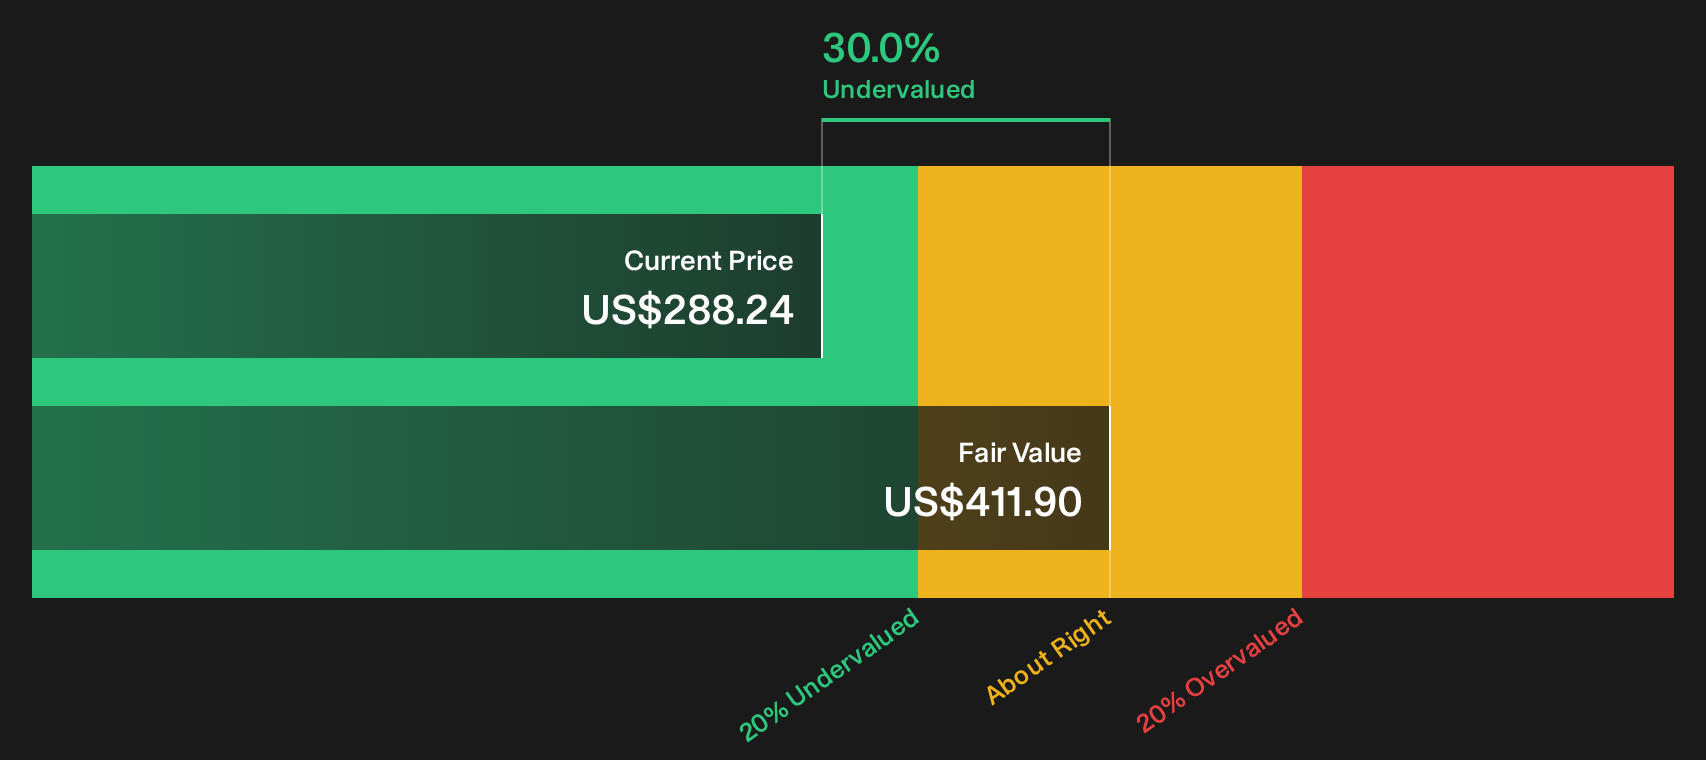
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AbbVie for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around AbbVie can feel confusing, especially with both flagged risks and clear bright spots on the table. If you want a fuller picture before deciding what it all means for your portfolio, start with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond AbbVie?
If AbbVie has sharpened your focus on opportunity and risk, do not stop here. Broader screening can surface ideas that better match your goals and risk tolerance.
- Target resilient compounding potential by scanning a curated set of 42 high quality undervalued stocks that pair quality fundamentals with more modest pricing.
- Secure more predictable income streams by reviewing a selection of 6 dividend fortresses built around higher yields and consistent payout histories.
- Dial down portfolio volatility by filtering for 32 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com