


EN
Texas Roadhouse (TXRH) Stock May Be Fully Priced On Cash Flow
Texas Roadhouse has rewarded long term shareholders, and the current share price around US$191.79 puts fresh attention on what the market is really paying for its cash flows. The question is whether that recent strength is grounded in the restaurant group's ability to keep generating and growing those cash streams over time.
- Over the past 5 years, Texas Roadhouse has delivered a total return of 127.4%, which raises the stakes on whether the current valuation still lines up with the cash the business produces.
- The chain's model of company operated restaurants with steady customer traffic can support recurring operating cash flow, which may influence how investors frame what a fair price is for those future inflows.
- What if you looked at Texas Roadhouse through its earnings instead? See why Texas Roadhouse's 30.5x P/E tells a different valuation story.
The issue now is whether Texas Roadhouse's recent share price around US$191.79 is appropriately reflecting the cash flows implied by its intrinsic value estimate using Discounted Cash Flow (DCF) analysis.
If you want to stress test whether Texas Roadhouse's 5 year return of 127.4% lines up with its cash flows, compare it with a wider set of companies using 42 high quality undervalued stocks
Is Texas Roadhouse Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here is built on Texas Roadhouse continuing to turn current operations into steady cash. Over the last twelve months the group produced about $391.7m in free cash flow, and the model assumes this pool of cash grows over time rather than shrinks. That helps anchor the idea that you are assessing an operating engine that is already producing meaningful cash, not a concept that still needs to prove it can fund itself.
Projected free cash flow is expected to be higher by 2028 and then to keep rising through the next decade, with growth rates that gradually slow as Texas Roadhouse matures in the model. When those future cash streams are discounted back and compared with the current share price of US$191.79, the DCF output suggests the estimated intrinsic worth of the equity is broadly in line with where the market is trading today. Find out what Texas Roadhouse could be worth using our Discounted Cash Flow (DCF) estimate.
The Texas Roadhouse Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Texas Roadhouse pick up where the valuation puzzle leaves off and explain which paths for growth, profitability and earnings would need to occur for the shares to appear meaningfully higher or lower than today’s price on a cash flow basis. Each narrative presents its own set of assumptions behind a fair value view, allowing you to compare those against Texas Roadhouse's actual results as fresh numbers are reported.
Community views on Texas Roadhouse are split between those who think the cash engine still has more to give and those who see recent efficiency gains as fragile.
Bull case: 9% undervalued
"Successful digital integration, including app upgrades, improved waitlist and to-go experience, and the completed rollout of digital kitchens and guest management, is already supporting calmer kitchens, better table turns, and to-go sales of more than $25,000 per week..."
Discover why this Narrative puts Texas Roadhouse at 9% undervalued.
Bear case: 18% overvalued
"Reliance on high beef usage in a tight cattle supply environment, together with produce inflation and only partial commodity contracting into the fourth quarter, leaves Texas Roadhouse exposed if input costs rise again faster than the planned 1% menu pricing..."
Explore why this Narrative puts Texas Roadhouse at 18% overvalued.
One more Texas Roadhouse check that sits outside the cash flow story
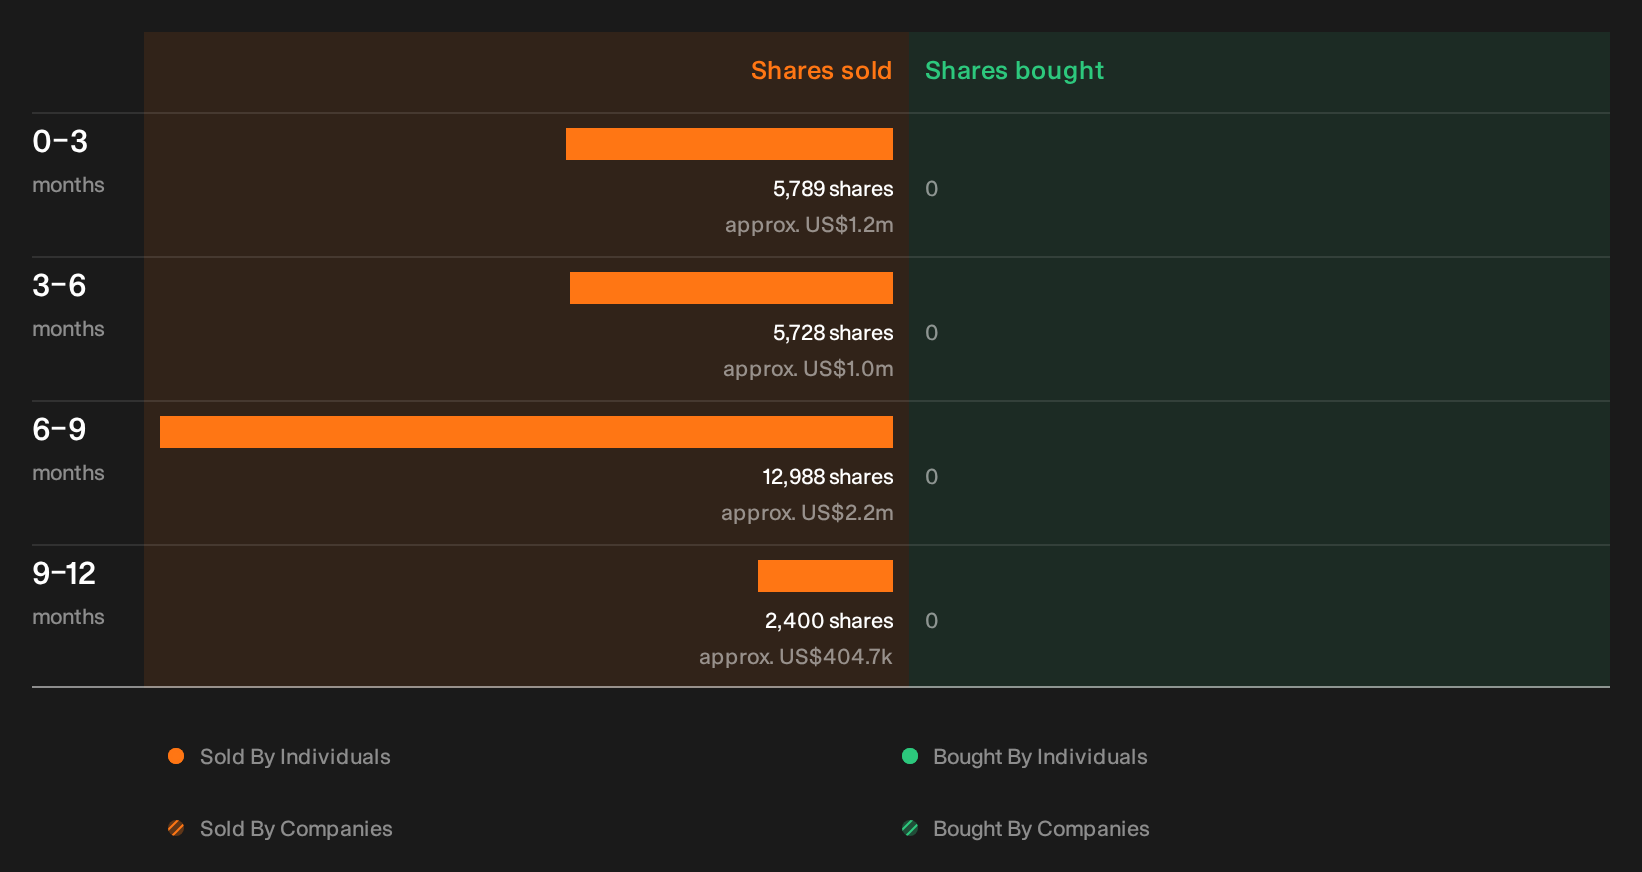
Cash generation tells only part of the Texas Roadhouse story. Recent transactions by people inside the business can carry extra information, and the specific sellers, sizes and possible signals are left for you to review. See the recent insider selling flagged for Texas Roadhouse.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com