


EN
Does Strong Manhattan Leasing Change The Bull Case For Vornado Realty Trust Stock?
- Vornado Realty Trust reported third quarter 2026 revenue of US$467.66 million and a net loss of US$31.61 million, along with higher funds from operations supported by strong Manhattan leasing and contributions from projects like PENN 1 and PENN 2.
- The REIT paired this operating update with fresh preferred dividend declarations and a large pipeline of signed but not yet commenced leases. This highlights a clear gap between accounting earnings and the cash generation that underpins its New York focused real estate platform.
- It remains to be seen how Vornado Realty Trust's Manhattan leasing activity and funds from operations will shape the broader investment narrative.
Vornado Realty Trust Investment Narrative Recap
To own Vornado Realty Trust, you need to believe the Manhattan leasing engine and PENN District upgrades can translate solid funds from operations into clearer earnings power over time. The latest quarter showed higher revenue but a move from net income to a net loss, so the cash flow story still sits ahead of the income statement.
The key near term swing factor is how quickly signed but not commenced leases roll into rent, especially in New York offices. The biggest risk is still the balance sheet. Elevated leverage, interest expense and refinancing needs could absorb a lot of operating progress if credit markets stay demanding.
The preferred dividend declaration on multiple series is the announcement that ties closest to this update. It points to Vornado Realty Trust continuing to service its hybrid capital stack even as it reports a net loss and funds ongoing redevelopment and leasing costs. For income focused investors, that is a tangible cash obligation, not an accounting line.
Those distributions also intersect directly with the main catalysts and risks. Paying preferred dividends while tenant improvements, leasing concessions and debt costs remain high leaves less room for retained cash. Execution on lease commencements at PENN 1, PENN 2 and other Manhattan assets, plus managing refinancing terms on more than US$4b of recent and upcoming debt, will shape how comfortable that payout looks over time.
What The Analyst Models Assume For Vornado Realty Trust
Analyst models around Vornado Realty Trust are built on a relatively steady revenue ramp, not a sharp rebound. The consensus view assumes top line expansion of 4.9% a year over the next three years, with the key swing factor being how much of the signed Manhattan leasing pipeline actually converts into ongoing rent checks.
Profit expectations in those models rest on margins rather than on outsized revenue surprises. Forecasts use a move in profit margin from about 0.3% today toward 7.4%, roughly in line with the current US Office REITs average, as the basis for long term earnings. On that framework, earnings are modeled at US$5.8 million today and US$160.9 million by 2029, which is a very large step up in absolute dollar terms even if the underlying assumption is simply that Manhattan Class A economics start to look more like the broader peer group.
The jump from single digit millions of earnings today to more than US$160 million in a few years implies a sharp shift in how much of Vornado Realty Trust's revenue drops to the bottom line. That shift is not just about rent. It assumes the PENN District upgrades, the Park Avenue Plaza acquisition and the broader leasing mix support higher margins once tenant work and concessions roll off and interest costs are contained.
Valuation work in the consensus snapshots connects that earnings path to price through the P/E multiple. To line up with the analyst price target, the stock would need to move from a P/E of 1,083.8x current earnings to 54.3x those projected 2029 earnings, which still sits above the 47.6x multiple currently ascribed to the wider US Office REITs group. The models also bake in a 2.78% annual decline in share count over the next three years, so part of the per share earnings ramp reflects buybacks as well as operating progress.
Discounting those future cash flows back to today uses an 8.42% rate in the Simply Wall St workup. That discount factor is one way of folding financing risk, rate sensitivity and Manhattan leasing uncertainty into a single number, even though real world pricing can move differently depending on how credit markets and tenant demand evolve between now and 2029.
Vornado Realty Trust's narrative projects US$2.2b revenue and US$160.9 million earnings by 2029. This is based on 4.9% yearly revenue growth and requires a very large earnings increase from US$5.8 million today.
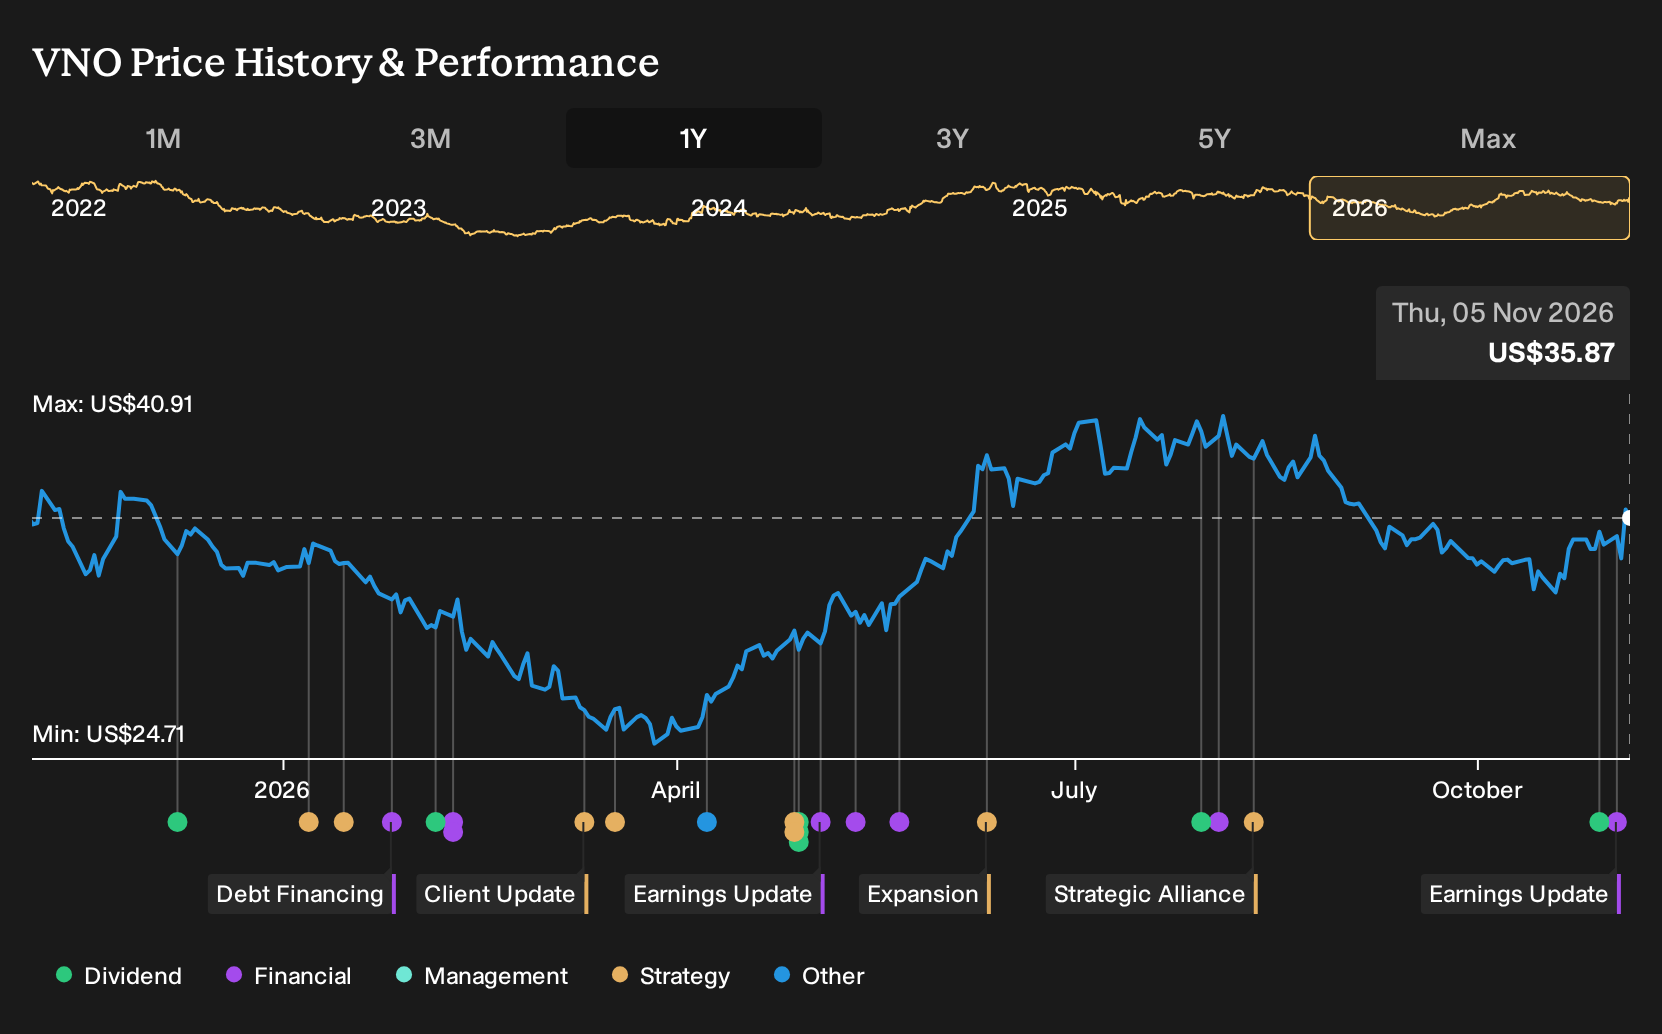
Uncover why Vornado Realty Trust's fair value indicates an 11% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts Vornado Realty Trust’s leverage front and center. Those analysts argue that heavy debt and refinancing needs could overshadow PENN District momentum. Before this earnings release, the most cautious forecasts only penciled in roughly 3.4% annual revenue growth to about US$2.1b and around US$154 million of earnings by 2029, so that camp may rethink its already cooler stance as the new results sink in.
Explore 3 other Vornado Realty Trust fair value estimates, including one that suggests as much as 14% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Vornado Realty Trust research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Vornado Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vornado Realty Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vornado Realty Trust?
If you want to put Vornado Realty Trust's story in context, compare it with other businesses that share similar cash flow themes, balance sheet profiles or income angles. The Simply Wall St Screener lets you filter for exactly the mix of quality, risk and income that fits your own checklist.
- For investors who want potential upside paired with quality fundamentals, start with a curated group of 42 high quality undervalued stocks that may trade below what their cash flows suggest.
- If steady balance sheets matter most to you, narrow the field to a list of solid balance sheet and fundamentals (24 results) that can help you focus on financially stronger businesses.
- For those hunting earlier stage ideas with room to mature, scan through a 9 elite penny stocks with strong financials that blends smaller market caps with stronger financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com