


EN
C3.ai (AI) Stock Looks Expensive Despite Its 75% Five Year Slump
C3.ai has been through a rough stretch on the market, which puts fresh attention on a simple question for you as a shareholder or potential buyer. Is the current share price meaningfully supported by the sales the business is generating today and what those revenues can realistically turn into over time?
- Over the past 5 years, C3.ai shares have fallen 75.2%, which puts the focus squarely on whether the revenue base can justify even the current reduced valuation.
- Recent coverage highlighting C3.ai as a key player in large scale AI and machine learning adoption can shape expectations for how quickly its software sales might grow relative to what investors are paying per dollar of revenue.
- Your read on C3.ai is one view; the desks covering it have another. See what analysts think C3.ai's shares could be worth.
The stock's next move may depend on whether C3.ai's current market value lines up with what its sales suggest investors are actually getting for their money.
If you are weighing C3.ai against other AI focused opportunities, it can help to see how pricing and business profiles compare across 41 AI small caps.
Does C3.ai Look Pricey on Sales?
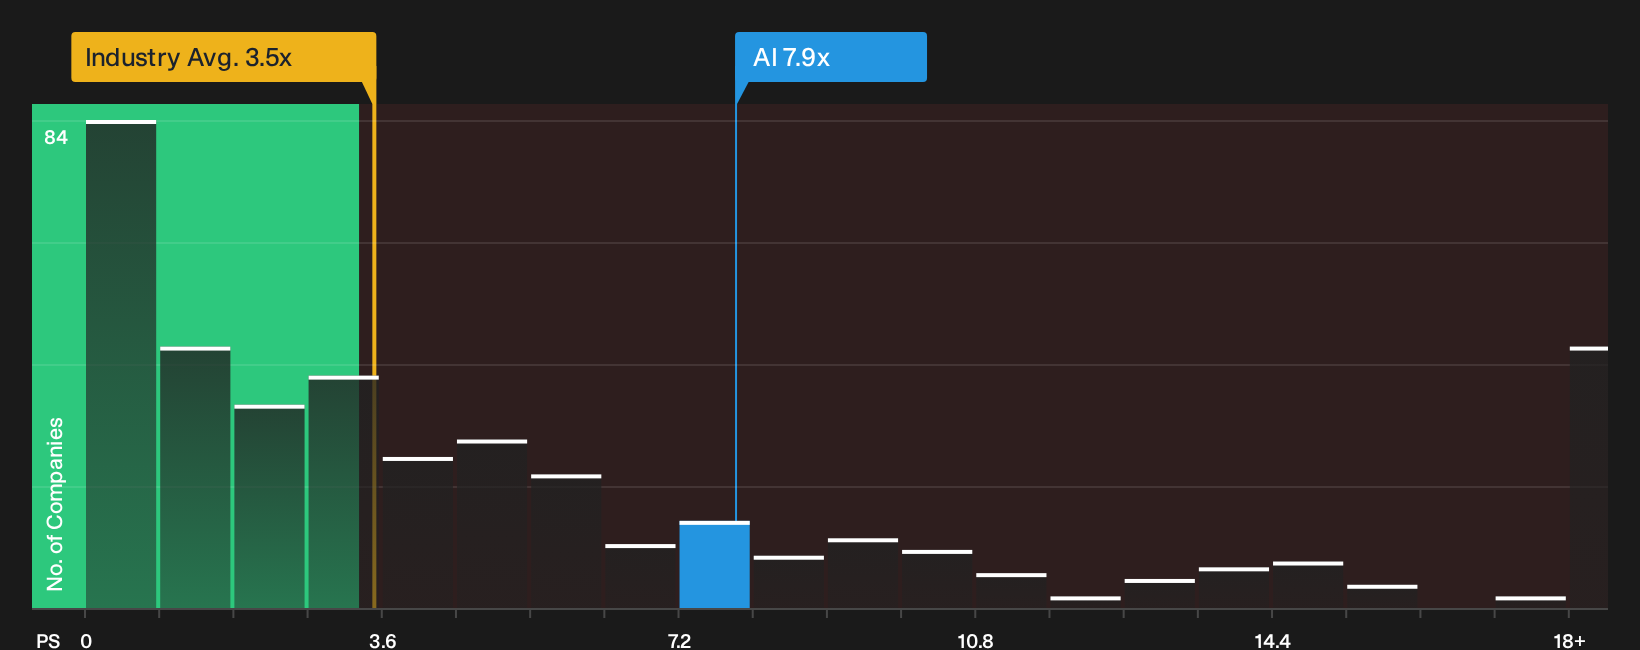
The P/S ratio tends to suit C3.ai because the focus is on how the market values each dollar of software revenue rather than current earnings. On this measure, the stock trades at about 7.9x sales, which is higher than both the wider software industry on roughly 3.5x and the peer group around 2.3x. That is a steep step up in what buyers are currently paying for the company’s top line.
The fair multiple model, which blends C3.ai’s growth profile, margins, size and risk, points to a much lower P/S level and flags the shares as overvalued on this framework. Because the gap is large, the output is better read as a warning that losses and perceived risk are heavily penalising the fair value estimate rather than as a precise target. Despite C3.ai being highlighted in recent AI and machine learning market reports as a key player in enterprise adoption, the price on this metric still implies a rich revenue valuation that needs careful scrutiny before you commit fresh capital. Explore the numbers behind C3.ai's P/S valuation.
The C3.ai Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the C3.ai valuation question leaves off by spelling out which combinations of future growth, profitability and earnings would need to hold for the stock to trade meaningfully higher or lower than it does today. They also frame each scenario as a thesis you can track over time rather than a one off snapshot, all hosted on C3.ai's Community page.
Community views on C3.ai split between those who see enough federal and cost progress to back the current valuation and those who think expectations still run ahead of the business.
Bull case: 24% undervalued
"A multistage restructuring that lowered non GAAP operating expenses from US$139.9 million in Q3 2025 to US$88.5 million in Q1 2027, alongside the first quarter of positive free cash flow of US$2.1 million, opens the door for incremental revenue from the existing C3.ai platform to fall through more directly to operating income and cash generation..."
Discover why this Narrative puts C3.ai at 24% undervalued.
Bear case: 28% overvalued
"The current valuation implies that C3.ai’s share price already bakes in meaningful long term success of its enterprise and federal AI platform strategy despite ongoing operating losses and past revenue pressure..."
Explore why this Narrative puts C3.ai at 28% overvalued.
One more C3.ai checkpoint before you act on the valuation
Analyst models outline where they expect C3.ai to be a few years from now. This gives you one more reference point to compare with today’s pricing. Explore where analysts expect C3.ai to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com