


EN
Waystar (WAY) Stock May Trade At A Premium Despite 19% Fall
Waystar Holding has seen its share price move around this year, and with earnings in focus after recent results, the live question is whether the current valuation really lines up with what the business is earning today.
- The stock is down 19.3% over the past year, which puts extra weight on whether the present valuation can still be explained by the earnings profile.
- Recent earnings updates tied to Waystar's AI-driven healthcare payment platform may support expectations for stronger profitability, which can influence how much investors are prepared to pay for each dollar of profit.
- Your read on Waystar Holding is one view; the desks covering it have another. See what analysts think Waystar Holding's shares could be worth.
The issue now is whether Waystar's current share price around US$28.88 is justified by its earnings when measured against the Fair Ratio benchmark.
If you want to test the same earnings question across a wider set of AI focused healthcare names, compare Waystar against 34 healthcare AI stocks.
Is Waystar Holding Getting Expensive on Earnings?
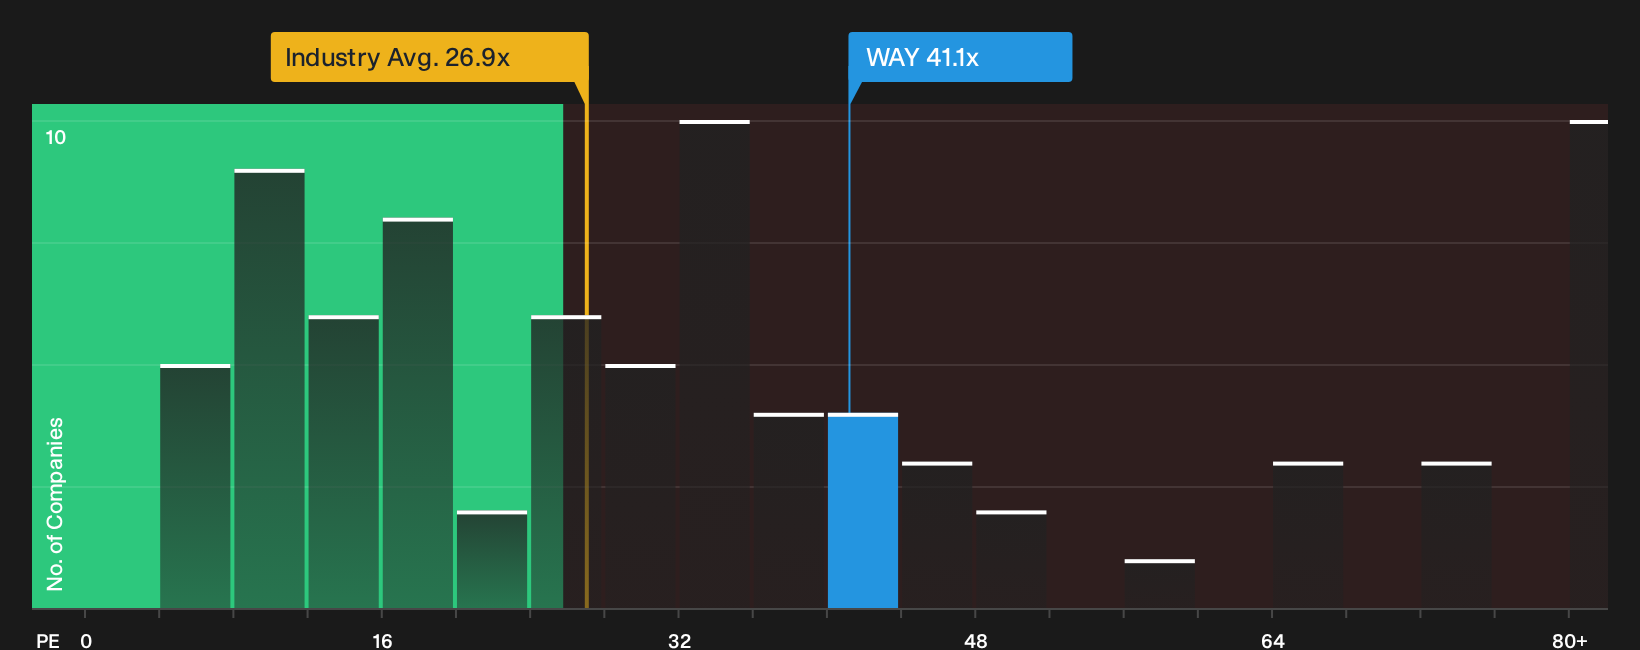
The P/E ratio fits Waystar Holding because earnings are the main yardstick many investors use for software like healthcare platforms that are already producing profits. Waystar trades on roughly 41.1x earnings, compared with about 26.9x for the wider Healthcare Services group, which puts a clear premium on the stock. Against a peer average of roughly 57.1x, the multiple sits partway up the range rather than at the top end.
Recent Q3 2026 results beat earnings forecasts and pointed to stronger AI driven payment volumes. Yet the current P/E still runs above the level suggested by a Fair Ratio framework that ties the multiple to Waystar's growth profile, margins, risk and scale. That gap implies investors are already paying up for a relatively optimistic earnings path, so any bumps in execution or AI adoption could matter more for this share price than for a cheaper healthcare software peer. Explore the numbers behind Waystar Holding's P/E valuation.
The Waystar Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Waystar Holding leaves off. They spell out which combinations of future growth, margins and earnings would need to materialise for the stock to be worth meaningfully more or less than today’s price. Each scenario links a fair value estimate to a specific storyline about Waystar Holding's potential catalysts and key risks, so you can track over time which version of events is actually showing up in the numbers on the Community page.
Community views on Waystar Holding split between investors who see more upside in the AI platform story and others who treat it as closer to fairly priced.
Bull case: 32% undervalued
"Evidence that hospitals are consolidating 15 to 32 legacy vendors onto Waystar Holding’s unified platform and that multi module customers report stronger improvements in collections…"
Discover why this Narrative puts Waystar Holding at 32% undervalued.
Bear case: roughly fairly valued
"Although AltitudeAI and other agents currently touch roughly 40% of revenue and are contributing to 30% of new bookings, growing use of general purpose LLMs by health systems and technology partners could compress the premium Waystar can charge for AI…"
Explore why this Narrative puts Waystar Holding at roughly fairly valued.
Waystar Holding’s price is only one piece of the decision
Valuation tells you what the market thinks today, but the analyst playbook for where Waystar Holding might sit a few years from now gives you a very different lens on the same ticker. Explore where analysts expect Waystar Holding to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com