


EN
Is Workiva (WK) Undervalued As Third Quarter 2026 Results Reset The Narrative?
Workiva (WK) just released third quarter 2026 results, giving investors fresh numbers on how its reporting platform business is performing. The update also covers the first nine months of the year.
Workiva’s recent third quarter results landed alongside a sharp shift in sentiment, with the 30-day share price return of 21.86% and 90-day move of 31.26% pointing to building momentum, even as the 1-year total shareholder return declined 1.62% and the 5-year total shareholder return fell 44.25%.
Scan how Workiva’s earnings surprise compares with other software operators seeing strong sentiment shifts using our hand picked 42 high quality undervalued stocks.
Bulls see Workiva’s earnings and sentiment shift as the start of a reset. Bears see a brief bounce in a long slide. Which case do today’s valuation markers lean toward?
Most Popular Narrative: 5% Undervalued
On the most followed view of Workiva, the current share price of $85.50 sits a little below an implied fair value of $89.80, leaving a small valuation gap that only really makes sense if the growth engines behind the story keep firing.
The main thing that has to go right is that Workiva successfully scales AI enabled, agentic-first workflows across regulatory, financial reporting, GRC and sustainability solutions while maintaining the high gross and net retention it currently reports.
The current valuation implies Workiva is fairly valued on the assumption that durable subscription growth, rising operating and free cash flow margins and expanding multi-solution and international cohorts are already reflected in the share price.
See why 8 investors see Workiva as 5% undervalued.
Result: Fair Value of $89.80 (UNDERVALUED)
Still, Workiva’s story can break if European sustainability rules shift in ways that curb demand, or if rapid partner led deployments start to damage retention.
Find out about the key risks to this Workiva narrative.
Another View: What Workiva Looks Like On Earnings Multiples
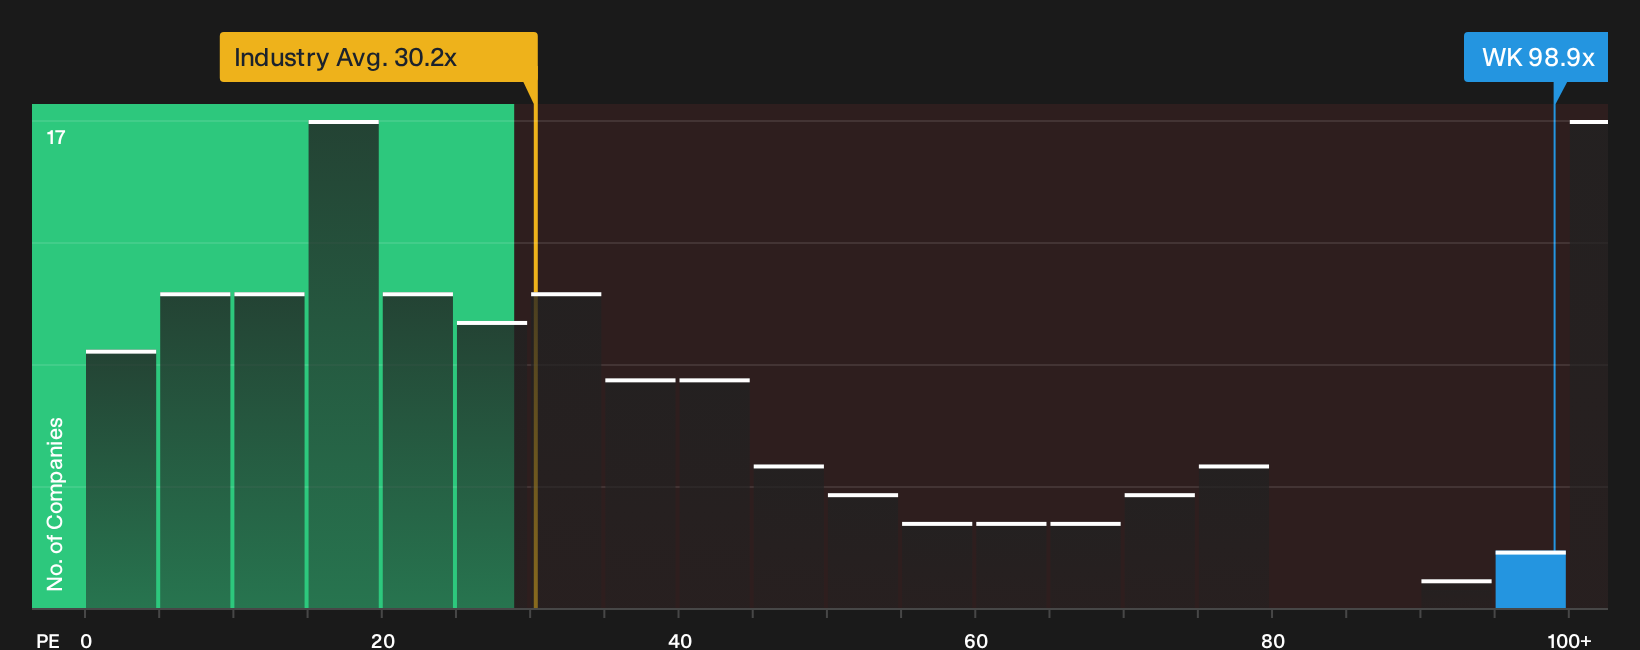
The DCF based fair value suggests Workiva shares trade well below an estimate of future cash flow value, yet the P/E ratio of 98.9x paints a very different picture. That compares with a 41.9x fair ratio estimate and a 31x industry average, which signals meaningful valuation risk if expectations cool.
To see how the earnings based yardstick lines up with other cross checks, and what the current price might be baking in, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Workiva is clearly split, and that kind of gap is where careful readers can move fastest. Weigh the upside and downside for yourself by starting with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Workiva?
If Workiva has sharpened your thinking, do not stop here. Use fresh screeners to spot other opportunities that fit the way you like to invest.
- Target companies with strong balance sheets by scanning our curated list of solid balance sheet and fundamentals (24 results) and focus your research on businesses with financial cushions built in.
- Hunt for potential bargains using the 21 high quality undiscovered gems that filters for quality fundamentals where market attention still feels limited.
- Dial down portfolio stress and concentrate on resilience by working through the 32 resilient stocks with low risk scores that highlights stocks with lower assessed risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com