


EN
PDF Solutions (PDFS) Earnings Jump Draws Focus, Is The Pullback A Valuation Opportunity?
Earnings jump puts PDF Solutions’ recent results in focus
PDF Solutions (PDFS) just posted third quarter and nine month figures that showed higher revenue and a swing in profitability compared with a year earlier, prompting fresh attention on the stock.
The share price reaction has gone the other way, with PDF Solutions falling 13.24% on the day and down 36.59% over the past month, even though the year-to-date share price return is still up 16.82% and the 1-year total shareholder return sits at 25.57%. Recent momentum has clearly faded.
Scan 41 profitable AI stocks that aren't just burning cash that share PDF Solutions’ focus on semiconductor and AI-related software, while already producing profits instead of just burning cash.PDF Solutions recently moved from reporting losses last year to posting a profit, followed by a sharp pullback in the share price. Is most of the rerating already reflected in the current price, or does the valuation still leave room for more?
Most Popular Narrative: 43% Undervalued
Against a last close of $34.52, the most followed narrative framework for PDF Solutions arrives at a fair value of $60.75. This frames the recent pullback as a discount within that story rather than a standalone warning sign.
The shift toward a higher mix of recurring and subscription based revenue, highlighted by US$205.1m of recurring revenue in 2025 and a backlog of US$271m that excludes future runtime and gainshare, indicates a larger base of future contracted revenue that can support operating leverage and steadier earnings.
See why 14 investors see PDF Solutions as 43% undervalued.
Result: Fair Value of $60.75 (UNDERVALUED)
Still, heavy R&D and capital spending on eProbe systems, along with any renewed weakness in high margin volume based revenue, could pressure the bullish PDF Solutions narrative.
Find out about the key risks to this PDF Solutions narrative.
Another View: What the P/E ratio says about PDF Solutions
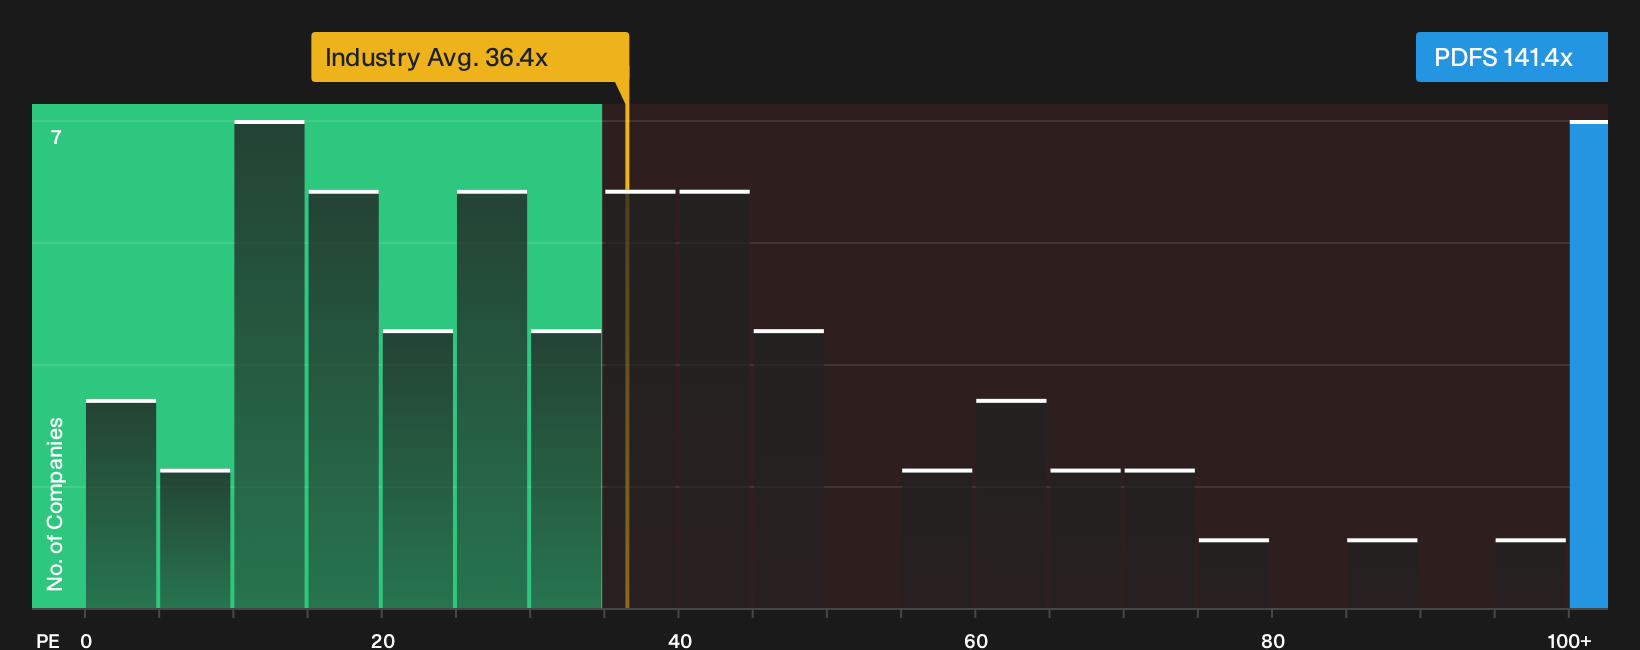
That $60.75 fair value hinges on the long term earnings path. A simple P/E check tells a different story. PDF Solutions trades at about 141.4x earnings, compared with 42.5x for the US semiconductor group and a fair ratio of 42.1x from the model. That kind of gap points to meaningful valuation risk if expectations ease.
It raises a blunt question for anyone looking at PDF Solutions today. Is this a rerating that can be supported by future delivery, or a multiple that leaves little room for disappointment, as suggested in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around PDF Solutions can be confusing, so consider acting promptly, reviewing the numbers yourself, and weighing 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond PDF Solutions?
If PDF Solutions has sharpened your thinking on valuation and expectations, it makes sense to broaden your watchlist with a few focused, data driven stock ideas.
- Target resilience by reviewing 32 resilient stocks with low risk scores that aim to limit downside while still keeping you in the market.
- Hunt for overlooked potential as you scan 21 high quality undiscovered gems that pair solid fundamentals with limited analyst coverage.
- Anchor your portfolio by checking a list of solid balance sheet and fundamentals (24 results) so you are not relying on fragile financial structures when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com