


EN
FIGS (FIGS) Stock Looks Above Fair Value On Its 245% Run
FIGS has delivered a sharp share price recovery in recent years, and with the stock closing at US$20.21, the key issue now is how firmly its earnings back that move. After such a strong swing in sentiment, the real question for investors is whether the current valuation rests on a solid profit base or expectations that may be hard to sustain.
- Over the past 3 years, FIGS has returned 244.9%, which puts a lot of weight on the idea that its current and future earnings can carry this higher share price.
- Recent analyst attention, including a higher price target and expectations for earnings per share growth over the next few years, may support the view that FIGS can convert revenue expansion into stronger profits.
- The analysts covering FIGS have run their own numbers. See what analysts think FIGS's shares could be worth.
The issue now is whether the earnings FIGS generates today, and what it may reasonably add over time, are enough to justify the price investors are being asked to pay.
If you are weighing whether FIGS at US$20.21 is really supported by its earnings, it can help to compare it with 42 high quality undervalued stocks.
Does FIGS Look Pricey on Earnings?
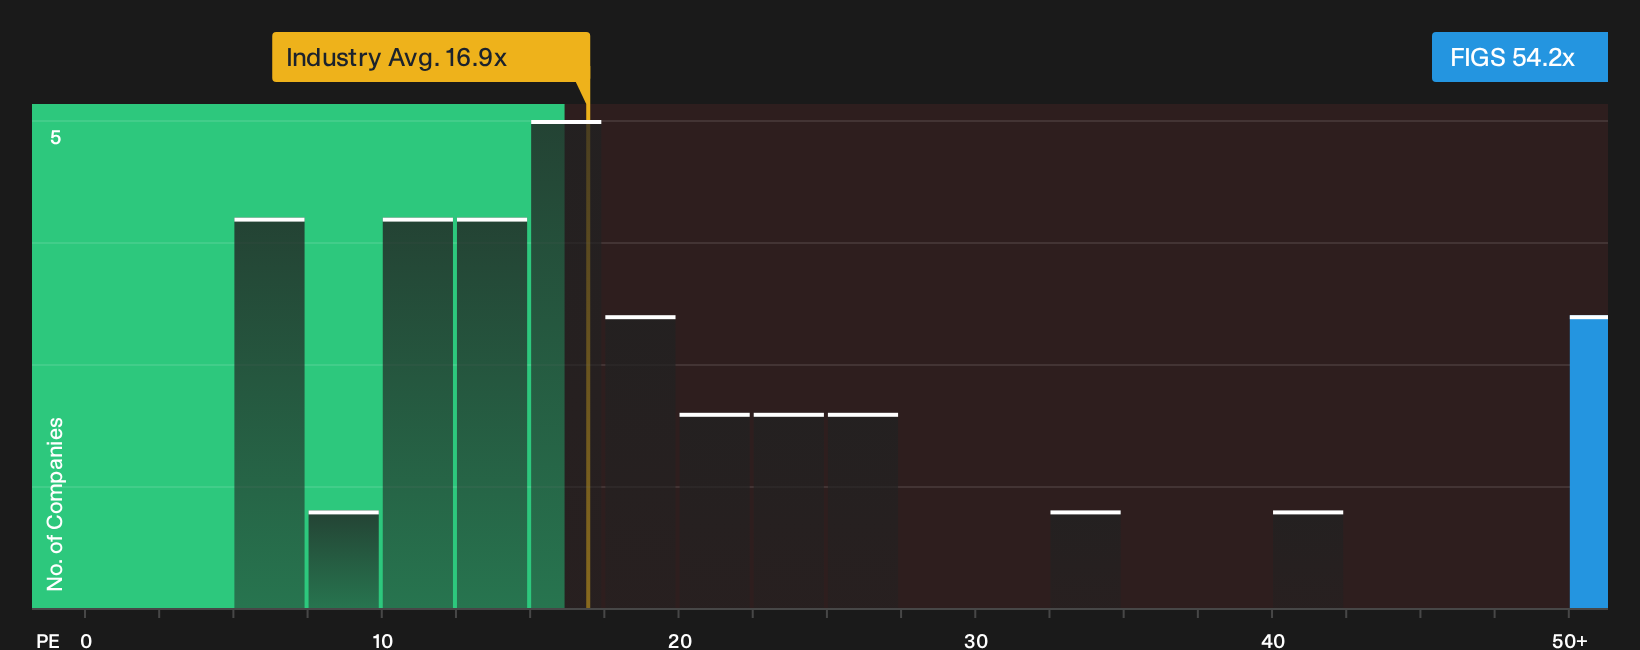
The P/E ratio is a clean way to see how much you are paying for each dollar of FIGS earnings. On that yardstick, FIGS trades on a P/E of 54.2x, which is well above the Luxury industry average of 16.9x and also higher than the peer group average of 21.9x. Compared with a tailored fair value multiple that adjusts for the business profile, the current level screens as overvalued. The gap is large enough that the model reads more like a warning signal than a precise target.
Oppenheimer lifting its price target to US$25 ahead of earnings has clearly helped enthusiasm, yet the present P/E still prices FIGS on a rich earnings tag relative to sector benchmarks and similar companies. For anyone considering the stock, the key question is whether the quality and durability of those profits fully support such a premium P/E, or whether expectations have moved ahead of what the income statement currently shows. Explore the numbers behind FIGS's P/E valuation.
The FIGS Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where FIGS' rich P/E leaves off and explain which paths for growth, profitability and earnings would need to occur for the stock to trade meaningfully higher or lower than today’s level on the Community page. Each narrative links its number to a clear view on future expansion, margins and risk, giving you something concrete to revisit as fresh information becomes available.
Community sentiment on FIGS splits into two clear camps, with one side seeing meaningful upside while the other worries the current price already bakes in a lot.
Bull case: 19% undervalued
"Widening wallet share per healthcare professional as FIGS converts more scrub buyers into full head to toe customers, with non scrubwear already approaching roughly one fifth of revenue, can create a higher revenue ceiling per active customer…"
Discover why this Narrative puts FIGS at 19% undervalued.
Bear case: 40% overvalued
"Execution. FIGS is in a precarious position where it has experienced a monumental decline in share price following a weakness in performance, which makes investors more skeptical about the business and leaves less room for error…"
Explore why this Narrative puts FIGS at 40% overvalued.
One more FIGS checkpoint before you make a move
There is a whole other lens on FIGS that sits outside the current share price and reported earnings, and it lives in where professional forecasts see the business a few years from now. Explore where analysts expect FIGS to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com