


EN
How Investors May Respond To Agilent (A) New Mass Spectrometer Launch
- Agilent Technologies recently launched the 5987A single quadrupole mass selective detector with GC Assist and MassHunter 14, integrating with its 8890B and 8860B gas chromatographs to support higher scan rates, automated SIM method development and lower energy use for laboratory workflows.
- The new GC/MS setup focuses on automation, remote monitoring and up to 40% lower energy consumption, which speaks directly to lab customers facing staff constraints, quality control demands and operational sustainability targets.
- We will now look at how Agilent Technologies' investment narrative lines up with this GC/MS launch and its lab efficiency focus.
Scan beyond Agilent Technologies and see which lab efficiency plays are already gaining traction in our hand-picked list of list of solid balance sheet and fundamentals (24 results).
Agilent Technologies Investment Narrative Recap
To own Agilent Technologies, you need to believe the firm can keep turning high end lab hardware, software and services into steadier, higher margin cash flows. The key near term swing factor is execution on Ignite productivity, pricing discipline and ongoing instrument replacement cycles. The new 5987A GC/MSD and MassHunter 14 launch fits that story but does not radically change it on its own.
The biggest current risk remains pressure on research budgets in academia and government, as well as any fresh hit from tariffs or supply chain complexity. New capacity ramps, such as Train C at NASD, also come with near term margin dilution if efficiency gains or demand absorption lag expectations.
The Proscia acquisition is the announcement that most clearly connects to the same themes as this GC/MS launch. Both point to Agilent Technologies leaning into software, automation and data heavy workflows, which can support more recurring revenue and tighter integration with customer processes if execution stays on track.
For investors watching catalysts, the combination of higher value GC/MS systems, AI enabled pathology software and CrossLab services creates a broader ecosystem that could help offset softness in more cyclical capex budgets. The risk is complexity. Integrating software businesses and supporting advanced instruments across global labs requires consistent investment in support, security and quality, or customer satisfaction and margins could suffer.
Agilent Technologies' narrative projects US$9.0b revenue and US$2.2b earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about US$800m from US$1.4b today.
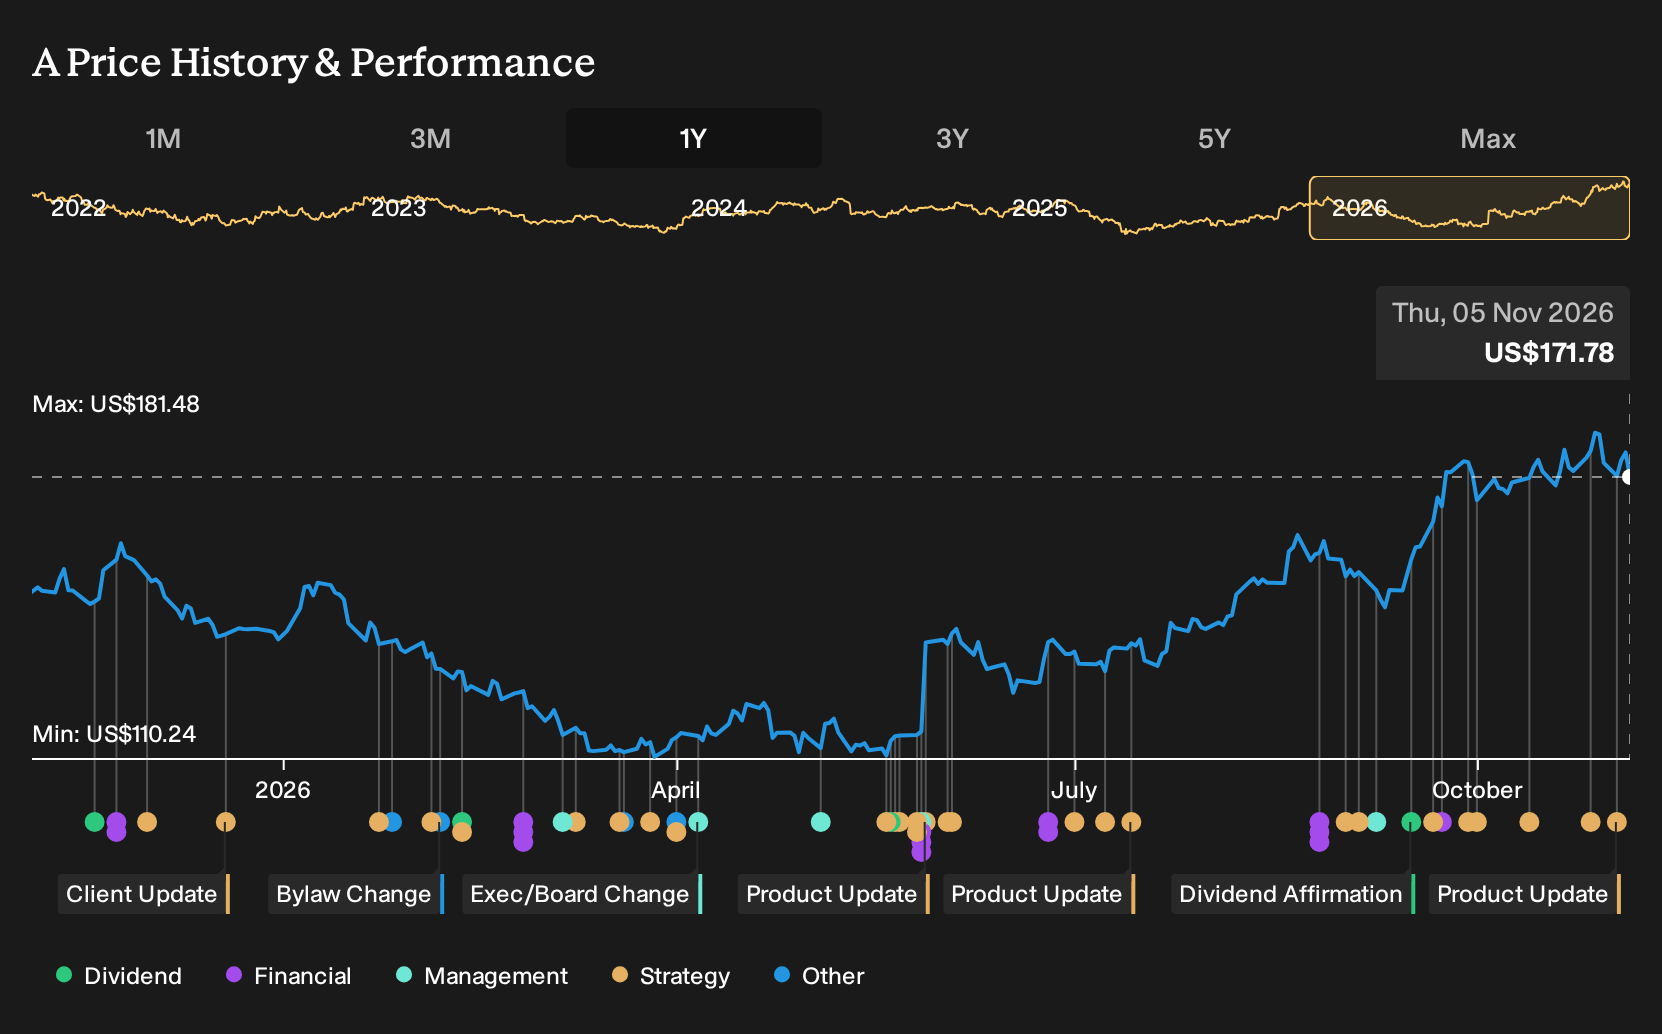
Uncover why Agilent Technologies' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The four fair value estimates from the Simply Wall St Community span roughly US$131 to US$182 per share, so private investors are clearly not singing from the same hymn sheet on Agilent Technologies. Set that against the upcoming Q4 2026 results and new GC/MS and Proscia driven products, and you get a mix of optimism and caution that is worth exploring through multiple viewpoints.
Explore 3 other Agilent Technologies fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Agilent Technologies research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Agilent Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agilent Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Agilent Technologies?
Agilent Technologies might be the right fit for you, or it might simply sharpen what you want from your next pick. Use that clarity to scan a wider field of opportunities with the Simply Wall St Screener and compare how other businesses stack up on quality, income and resilience.
- For investors who care most about downside protection and steadier balance sheets, check out a curated 32 resilient stocks with low risk scores that may suit a more conservative approach.
- If you want a combination of quality fundamentals and the potential for mispricing, take a look at our hand picked 21 high quality undiscovered gems to see what else is on the radar.
- Income focused readers can focus their attention on a targeted 6 dividend fortresses that prioritises higher yields alongside business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com