


EN
Where Does Ultragenyx Pharmaceutical (RARE) Value Sit After Cost Cuts?
Ultragenyx Pharmaceutical has seen its stock slide over several years, even as the business secures new drug approvals and restructures to cut costs. This puts fresh focus on what investors are really paying for its current level of sales. With the share price around US$15.57 after a volatile few months, the question is whether that market value lines up with what the company is generating at the top line today.
- The stock has fallen 81.0% over the past 5 years, so any view on Ultragenyx Pharmaceutical now hinges on whether its current market value still makes sense relative to its sales base.
- Regulatory progress on gene therapies and the push toward profitability through workforce and expense reductions can reshape expectations for how efficiently Ultragenyx Pharmaceutical may convert future revenue into cash.
- There is a second opinion on Ultragenyx Pharmaceutical worth weighing. See what analysts think Ultragenyx Pharmaceutical's shares could be worth.
The issue now is whether Ultragenyx Pharmaceutical’s current share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you are weighing Ultragenyx Pharmaceutical after a 5 year share price decline of 81.0%, it can help to compare this setup with 42 high quality undervalued stocks.
Is Ultragenyx Pharmaceutical Fairly Priced on Sales?
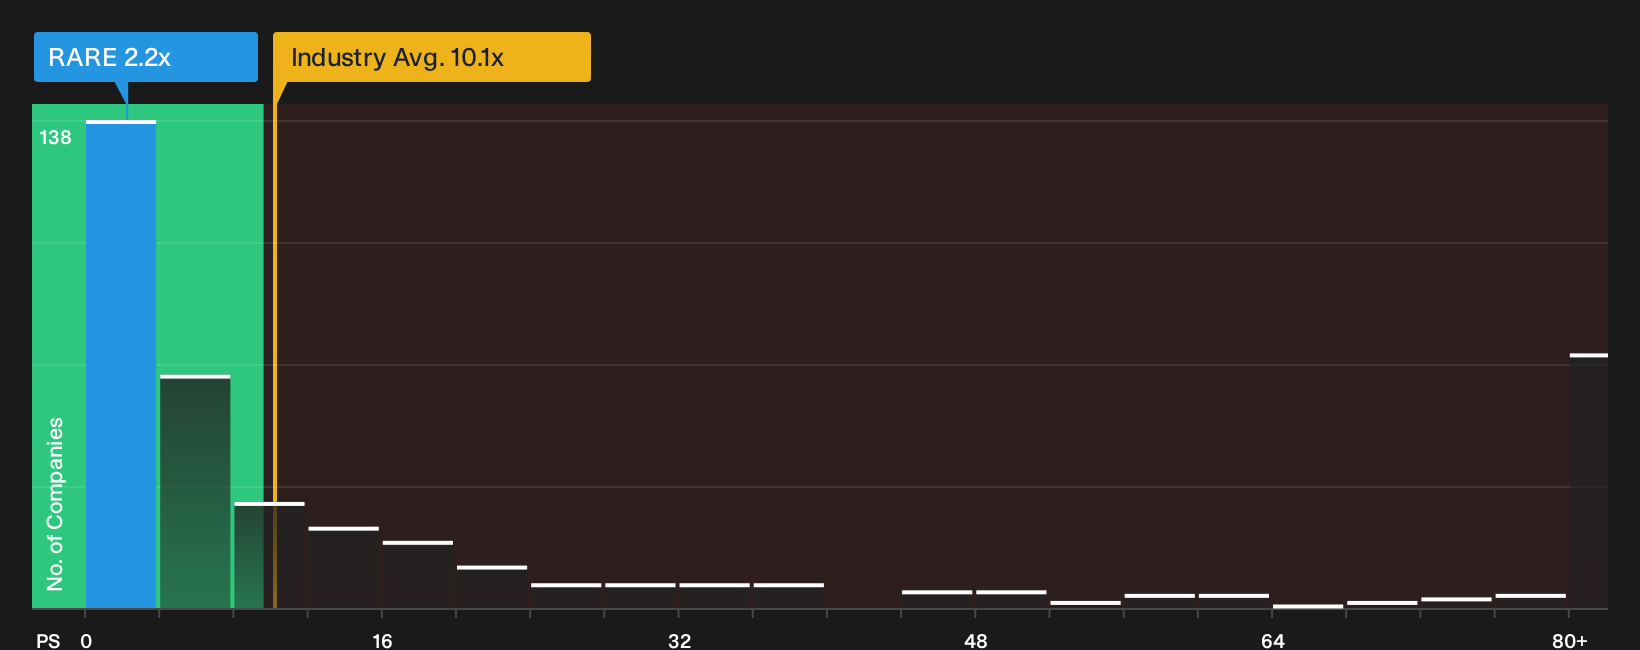
P/S is a useful lens for Ultragenyx Pharmaceutical because the business is still loss making, so investors often anchor on revenue rather than earnings. On this yardstick, the stock trades on a P/S of about 2.2x, which is far below the Biotechs sector average of roughly 10.1x and well under the peer group near 10.8x. That gap means the market is paying a much lower price for each dollar of Ultragenyx Pharmaceutical’s sales than for many comparable drug developers.
The Fair Ratio model, which adjusts the benchmark for Ultragenyx Pharmaceutical’s own growth outlook, margins, size and risk profile, points to a P/S very close to where the shares trade today. Because the recent gene therapy approvals and cost cuts are already in view, the relatively low multiple alongside that near matched Fair Ratio suggests investors are treating today’s sales base with some caution rather than giving it a clear discount or premium. Explore the numbers behind Ultragenyx Pharmaceutical's P/S valuation.
The Ultragenyx Pharmaceutical Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Ultragenyx Pharmaceutical pick up where the valuation puzzle above leaves off and explain which growth, margin and earnings paths would need to occur for the shares to appear meaningfully higher or lower than today’s price on the Community page. Each scenario ties its figures to a specific view of how Ultragenyx Pharmaceutical's growth, profitability and risk profile could evolve, giving you a reference point you can revisit as new information becomes available.
One of the top community narratives on Ultragenyx Pharmaceutical: 40% undervalued
"The 'Ultragenyx Turnaround Thesis' is trapped in a commercial illusion, mistaking a multi-product portfolio for financial stability while ignoring deep-rooted structural inefficiencies..."
Discover why this Narrative puts Ultragenyx Pharmaceutical at 40% undervalued.
One more Ultragenyx Pharmaceutical question before you move on
The price tag on Ultragenyx Pharmaceutical’s revenue only tells part of the story, because the people steering the business and how their pay is structured can strongly influence where that story goes next. See who runs Ultragenyx Pharmaceutical and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com