


EN
Natural Resource Partners (NRP) Could Be 53% Undervalued After Weaker Q3 Earnings
Natural Resource Partners (NRP) has drawn investor attention after reporting third quarter 2026 results. Revenue was US$44.82 million and net income was US$26.01 million, both below the prior year period.
Despite the softer third quarter, Natural Resource Partners’ recent share price performance has remained firm, with a 30 day share price return of 6.6% and a 90 day gain of 9.9% pointing to steady momentum. Over a longer horizon, total shareholder returns of 16.1% over one year and about 4x over five years indicate that the market has been rewarding the partnership even as investors reassess risk and income expectations around the latest earnings update.
Spot opportunities around Natural Resource Partners by scanning a curated set of resilient royalty and resource-focused businesses in our 32 resilient stocks with low risk scores.Natural Resource Partners looks like a robust royalty platform on recent return numbers, yet the latest earnings step down sets a different tone. After this run in the unit price, is that strength already fully baked in?
Price-to-Earnings of 15.5x: Is it justified?
Natural Resource Partners currently trades on a P/E of 15.5x, with the units at $117.52 and earnings that have declined on average by 3.7% per year over the past 5 years. At the same time, NRP is described as expensive versus the broader US Oil and Gas industry, but still cheaper than a narrower peer set.
The P/E ratio compares the unit price to earnings per unit and helps you see how much investors are paying for each dollar of profit. For a royalty focused partnership like Natural Resource Partners, this matters because earnings quality is flagged as high, yet returns on equity are described as low at 15.3% and profit growth has fallen both over the past year and over the 5 year period.
Against that backdrop, the P/E of 15.5x sits above the US Oil and Gas industry average of 11.2x. This signals the market is assigning a richer tag than the sector overall. At the same time, it remains below the 22.1x peer average. On this measure, NRP screens as comparatively cheaper than closer royalty and resource focused peers, even though its own recent earnings trends have declined.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 15.5x (ABOUT RIGHT)
Still, the investment case for Natural Resource Partners can be knocked off course if royalty volumes soften further or if commodity prices fall enough to undercut lease economics.
Find out about the key risks to this Natural Resource Partners narrative.
Another View: Cash Flows Paint A Different Picture
The earlier look at Natural Resource Partners focused on its 15.5x P/E, which suggested the units were on the expensive side versus the broader US Oil and Gas group. A different lens tells a very different story. Our DCF model estimates the future cash flow value at $253.40 per unit, while the units last traded at $117.52. On that basis, the units screen as heavily undervalued, which raises a sharp question for investors: Is the market underestimating the durability of Natural Resource Partners’ royalty cash flows, or is the model too generous about what those future distributions might look like?
Look into how the SWS DCF model arrives at its fair value.
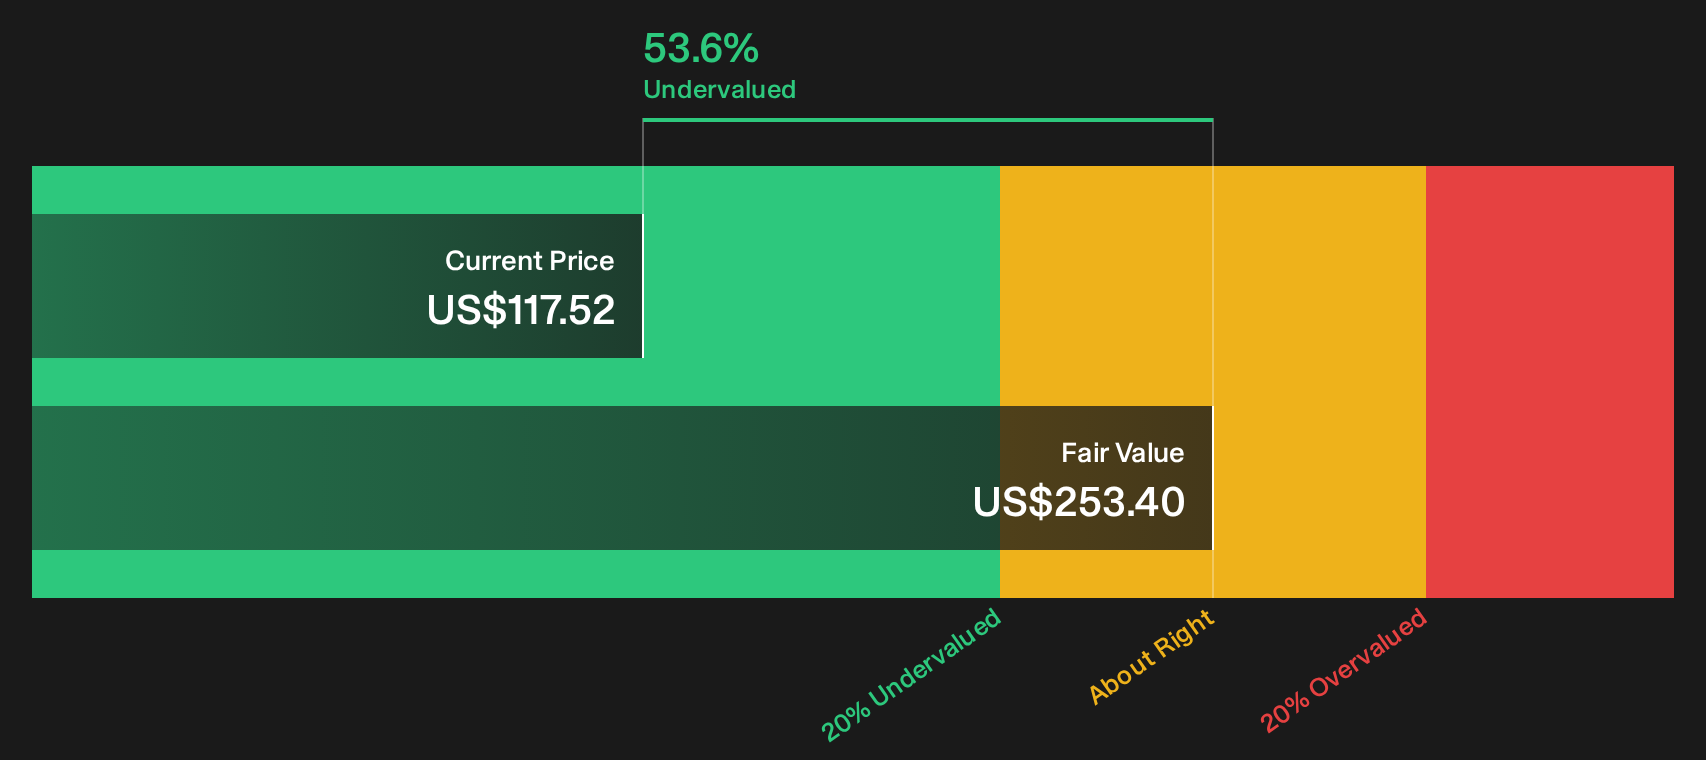
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Natural Resource Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Natural Resource Partners so far. If you want to move beyond the headline takeaways and judge the royalty story on your own terms, weigh both sides of the ledger with the 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Natural Resource Partners?
If Natural Resource Partners has your attention, do not stop here. Use this momentum to broaden your watchlist with fresh, high conviction ideas from the Simply Wall Street Screener.
- Target stronger downside protection by checking resilient businesses with low risk scores through the 32 resilient stocks with low risk scores.
- Hunt for potential value opportunities by reviewing financially healthy companies that appear mispriced using the 42 high quality undervalued stocks.
- Build a sturdier income stream by scanning for higher yielding payout opportunities with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com