


EN
Chesapeake Utilities (CPK) Rises On Earnings And Dividend But Is The Valuation Already Priced In
Chesapeake Utilities (CPK) just paired higher third quarter and year to date earnings with news of another quarterly cash dividend, a combination that keeps income and fundamental performance in clear focus for investors.
Recent trading suggests investors have been warming to Chesapeake Utilities again. The company has delivered a 7 day share price return of 4.52% and a 30 day gain of 10.63% at a last close of $141.69. A 3 year total shareholder return of 73.96% points to stronger longer term compounding, while the 1 year total shareholder return of 8.82% shows more moderate momentum this year.
Scan beyond Chesapeake Utilities and compare this earnings and dividend story with 32 resilient stocks with low risk scores that show similar resilience without taking on outsized risk.
After a sharp move to around $141.69 on the back of fresh results and another dividend, Chesapeake Utilities now sets up a familiar fork in the road. Investors may choose to commit at this level or wait for a potentially cheaper entry and risk missing it.
Most Popular Narrative: 4% Undervalued
On the most followed view of Chesapeake Utilities, a fair value of $147.75 sits a little above the recent $141.69 close. This puts the current move into context while highlighting how much depends on the capital plan actually turning into earnings.
Substantial capital investment in energy infrastructure modernization continues, with Chesapeake Utilities investing about US$262 million in the first half of 2026 and raising full year 2026 capex guidance to US$550 million to US$600 million. This increases regulated rate base and is expected to support higher future revenue and earnings.
See why 0 investors see Chesapeake Utilities as 4% undervalued.
Result: Fair Value of $147.75 (UNDERVALUED)
Still, the Chesapeake Utilities story hinges on flawless execution. Delays such as the WRU LNG project or heavier than expected funding needs could quickly challenge the current upside case.
Find out about the key risks to this Chesapeake Utilities narrative.
Another View: What Multiples Say About Chesapeake Utilities
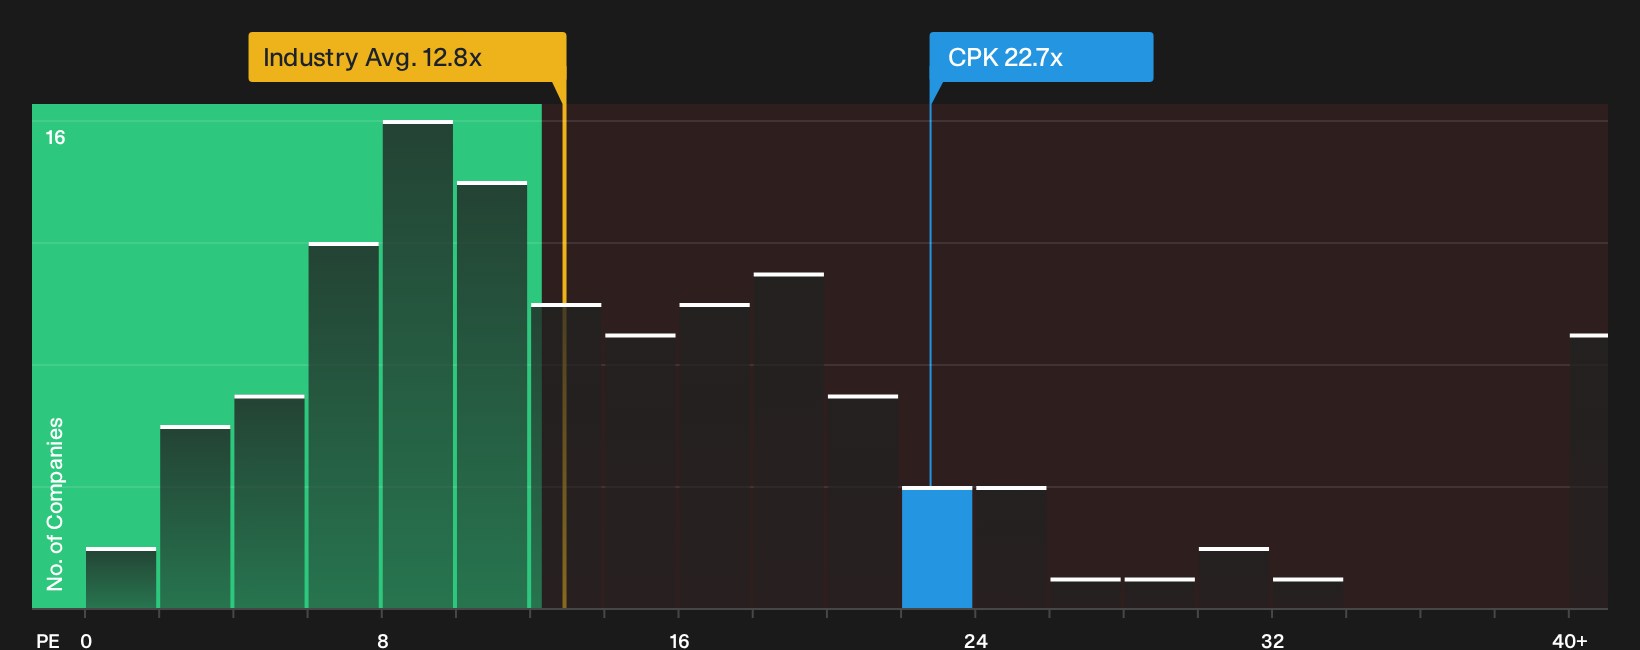
The first narrative paints Chesapeake Utilities as about 4% undervalued against a $147.75 fair value. A simple P/E cross check tells a tougher story. At roughly 22.7x earnings, CPK trades well above the global gas utilities average of 12.7x, the peer group at 17.4x and even its own 18.8x fair ratio. That gap points to less room for error in the buildout thesis, so the real question is whether you think the earnings path can justify paying this kind of premium.
See what the numbers say about this price in more detail in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Chesapeake Utilities so far. If you want to move before the next round of headlines, start with the full picture of risks and upside in the 2 key rewards and 2 important warning signs.
Looking for more Chesapeake Utilities sized ideas?
Do not stop with Chesapeake Utilities. Broaden your watchlist with fresh ideas that match your risk, income and quality preferences before the next move leaves you behind.
- Target potential mispricing by scanning a curated set of 42 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Strengthen your income stream by reviewing a hand picked pool of 6 dividend fortresses built around higher yields and robust cash generation.
- Protect your downside by focusing on resilience through our list of solid balance sheet and fundamentals (24 results) that keeps financial strength front and center.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com