


EN
Pershing Square (PS) Stock Looks Stretched On Its 108% Run
Pershing Square has seen its stock move sharply this year, which puts fresh focus on a simple question for investors who care about fundamentals: Is the current share price properly grounded in what the business is generating in sales today and what those revenues might support over time?
- The stock is up about 108.0% year to date, so anyone looking at Pershing Square now has to ask whether that kind of share price move is still in line with the scale of its sales.
- Recent comments from Bill Ackman on opportunities created by what he calls more speculative trading suggest Pershing Square can keep deploying capital into large, liquid holdings, which may support expectations for future fee income and related revenue.
- There is a second opinion on Pershing Square worth weighing. See what analysts think Pershing Square's shares could be worth.
The stock's next move may depend on whether the current market value can be squared with Pershing Square's sales once you put those figures alongside Fair Ratio.
If you want a second reference point alongside Pershing Square while this casino style trading theme plays out, start with a focused screen of 32 resilient stocks with low risk scores.
Does Pershing Square Look Pricey on Sales?
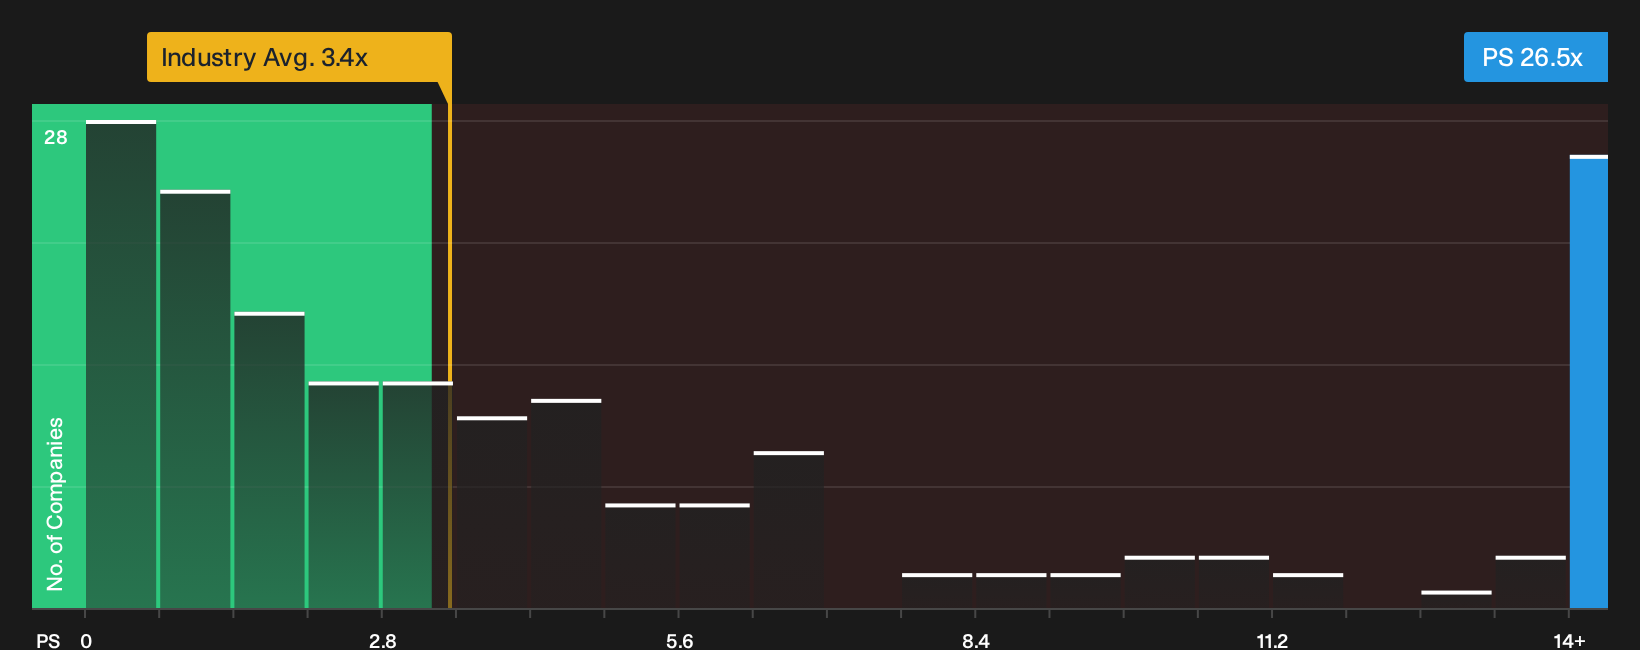
P/S tends to matter most for Pershing Square because the business model leans heavily on fee and related revenue rather than traditional manufacturing output. On that measure, the stock trades on a P/S ratio of about 26.5x, compared with roughly 3.4x for the broader Capital Markets group and a peer average near 2.2x. That is a very large gap for a simple sales multiple, so anyone running the numbers is really being asked to pay a high price for each dollar of current revenue.
The Fair Ratio model, which adjusts the P/S benchmark for Pershing Square's own margins, risk profile and size, also points to the shares screening overvalued on this metric. The distance between the two figures is wide enough that it reads more like a warning flag than a fine tuned target. Because of Bill Ackman's recent comments about "casino" style trading and the opportunity set it creates, the current valuation also embeds a lot of confidence that this fee base and deal pipeline will support the revenue implied by that premium. Explore the numbers behind Pershing Square's P/S valuation.
The Pershing Square Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/S puzzle leaves off. They spell out what would need to happen to Pershing Square's growth, margins and earnings for the share price to move meaningfully higher or lower than it is today. Each narrative links a fair value estimate to a specific mix of potential catalysts and risks so you can track over time which version of the Pershing Square story is actually unfolding on the Community page.
One of the top community narratives on Pershing Square: 5% undervalued
"The launch of Pershing Square Ventures as a permanent capital crossover vehicle targeting high growth private and pre IPO companies gives the firm access…"
Discover why this Narrative puts Pershing Square at 5% undervalued.
One more Pershing Square factor to weigh before acting on the valuation
Pershing Square’s pricing story is only part of the picture, because recent checks have also raised specific concerns that investors may want to weigh alongside the upside scenarios already in focus. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com