


EN
Earnings Beat May Change The Case For American Superconductor Stock
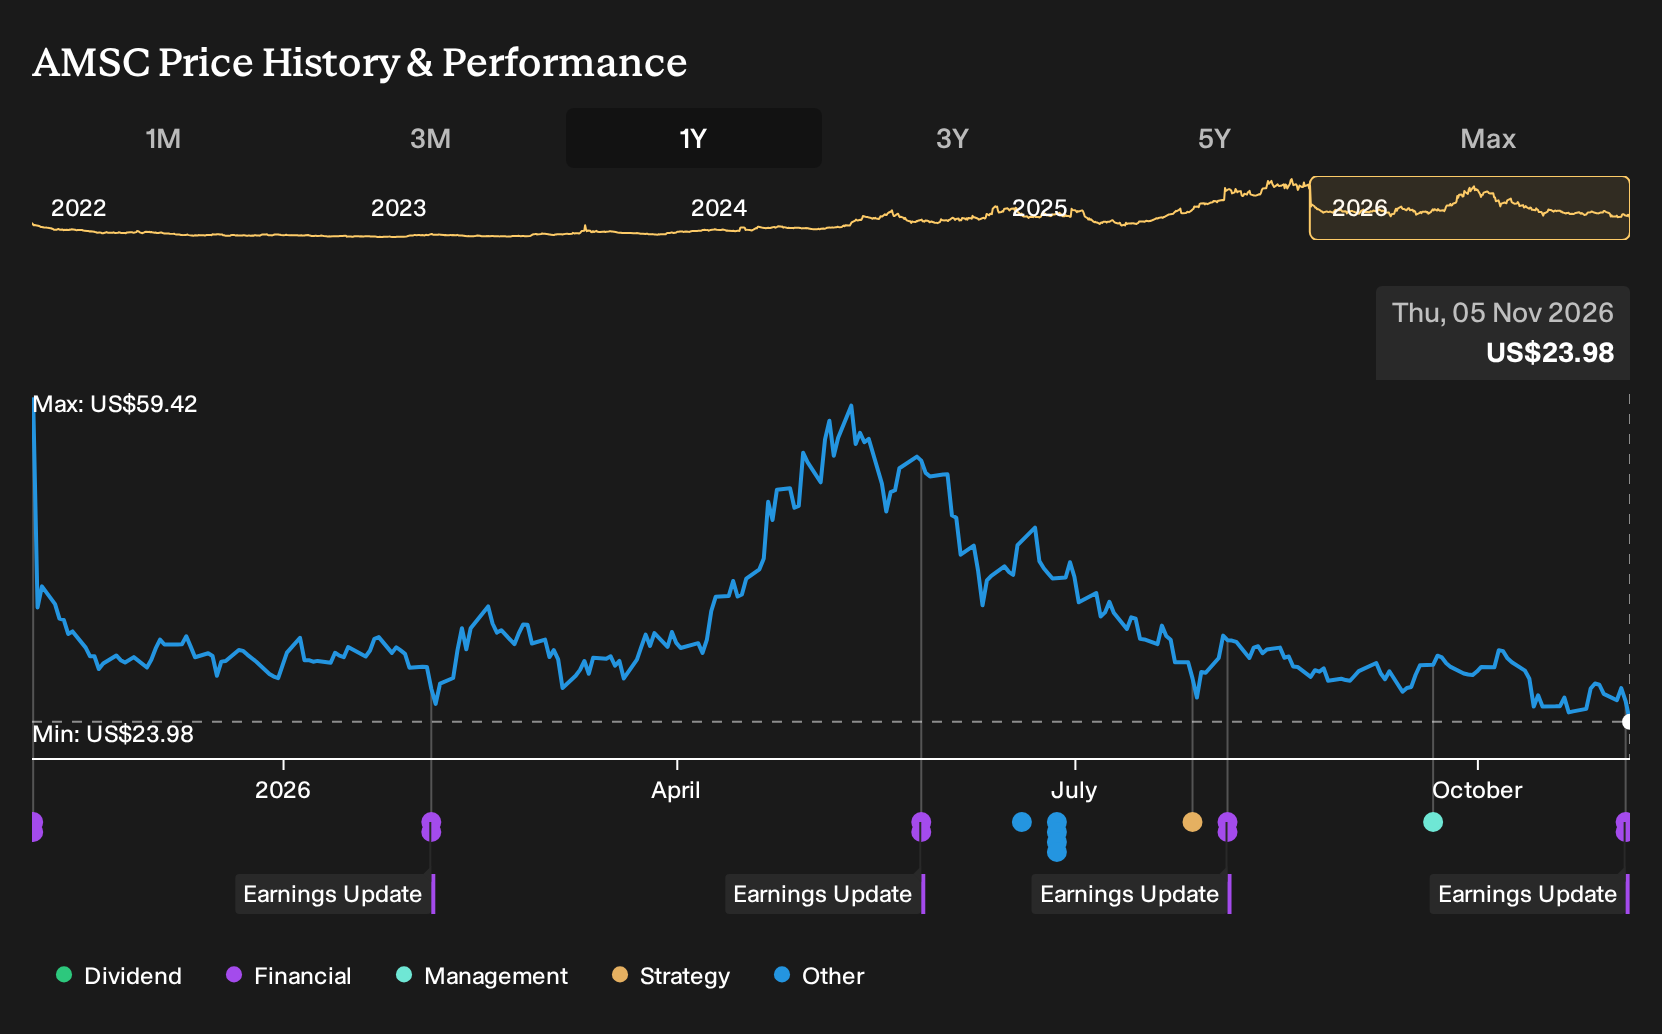
- American Superconductor reported second quarter 2026 revenue of US$94.04 million and net income of US$3 million, with adjusted earnings of US$0.19 per share.
- Management now expects third quarter 2026 revenue to exceed US$80 million and projects net income at or above breakeven on a per share basis.
- We will now look at how American Superconductor's revenue beat and profit profile could influence the investment narrative already in place.
Compare American Superconductor's earnings story with other grid and energy transition plays by reviewing the hand picked 40 power grid technology and infrastructure stocks that share similar revenue and profitability drivers.
American Superconductor Investment Narrative Recap
To own American Superconductor, you need to be comfortable with a grid and power quality story that leans on multi sector capex and a growing project pipeline, while accepting that quarterly earnings may swing around specific customers and large contracts. The latest quarter showed US$94.04 million of sales and US$3 million of net income, which supports the idea that the platform can produce recurring profit, even if EPS from continuing operations sits at US$0.06.
The bigger near term swing factor is how the higher cost base from expansion and integration interacts with any future step downs in orders. Management’s outlook for third quarter 2026, with revenue expected to exceed US$80 million and net income at or above breakeven, points to a business that is still absorbing growth investments and Brazilian ramp up, so the main risk remains margin pressure if volumes or pricing soften.
The most relevant update alongside this earnings print is American Superconductor’s guidance for the third quarter ending 31 December 2026. Management expects revenue above US$80 million and net income to be at or above breakeven on a per share basis, assuming no change in contingent consideration. That outlook matters because it frames how sustainable recent profitability might be as earlier pull forward orders wash through.
For you as a shareholder, the guidance links directly to the key catalysts and risks already flagged. A revenue level above US$80 million with at least breakeven earnings would show the company working through higher R&D and SG&A while it builds out Brazilian and transformer capacity. If future quarters land meaningfully below that kind of profile or margins weaken further, concerns about cost absorption, earnings quality and a possible valuation reset remain firmly on the table.
American Superconductor's current analyst narrative points to forecast revenue of US$529.1 million and earnings of US$1.9 million by 2029, built on an assumed 18.1% yearly revenue growth rate and an earnings decline of US$134.7 million from US$136.6 million today.
Uncover why American Superconductor's fair value indicates a 158% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the more cautious analysts focus on backlog risk rather than cost absorption. They see American Superconductor’s more than US$300m 12 month backlog as vulnerable to project timing, despite forecasting around US$530.6m of revenue and US$4.5m of earnings by 2029. That is a more pessimistic framing, and the fresh Q2 beat and guidance could eventually shift it. Readers should treat this as one of several viewpoints to explore.
Explore 4 other American Superconductor fair value estimates, including one that suggests it could be worth just $38.17.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your American Superconductor research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Superconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Superconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Superconductor?
Once you have formed a view on American Superconductor, it can help to compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, consider a curated set of under followed opportunities via 21 high quality undiscovered gems.
- If capital preservation sits near the top of your priority list, look at a carefully filtered pool of sturdier balance sheet candidates through the 32 resilient stocks with low risk scores.
- Those focused on balance sheet strength and fundamental support can scan a broader list of solid balance sheet and fundamentals (24 results) to cross check ideas already on the watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com