


EN
How Investors May Respond To Watsco (WSO) Mixed Q3 Earnings
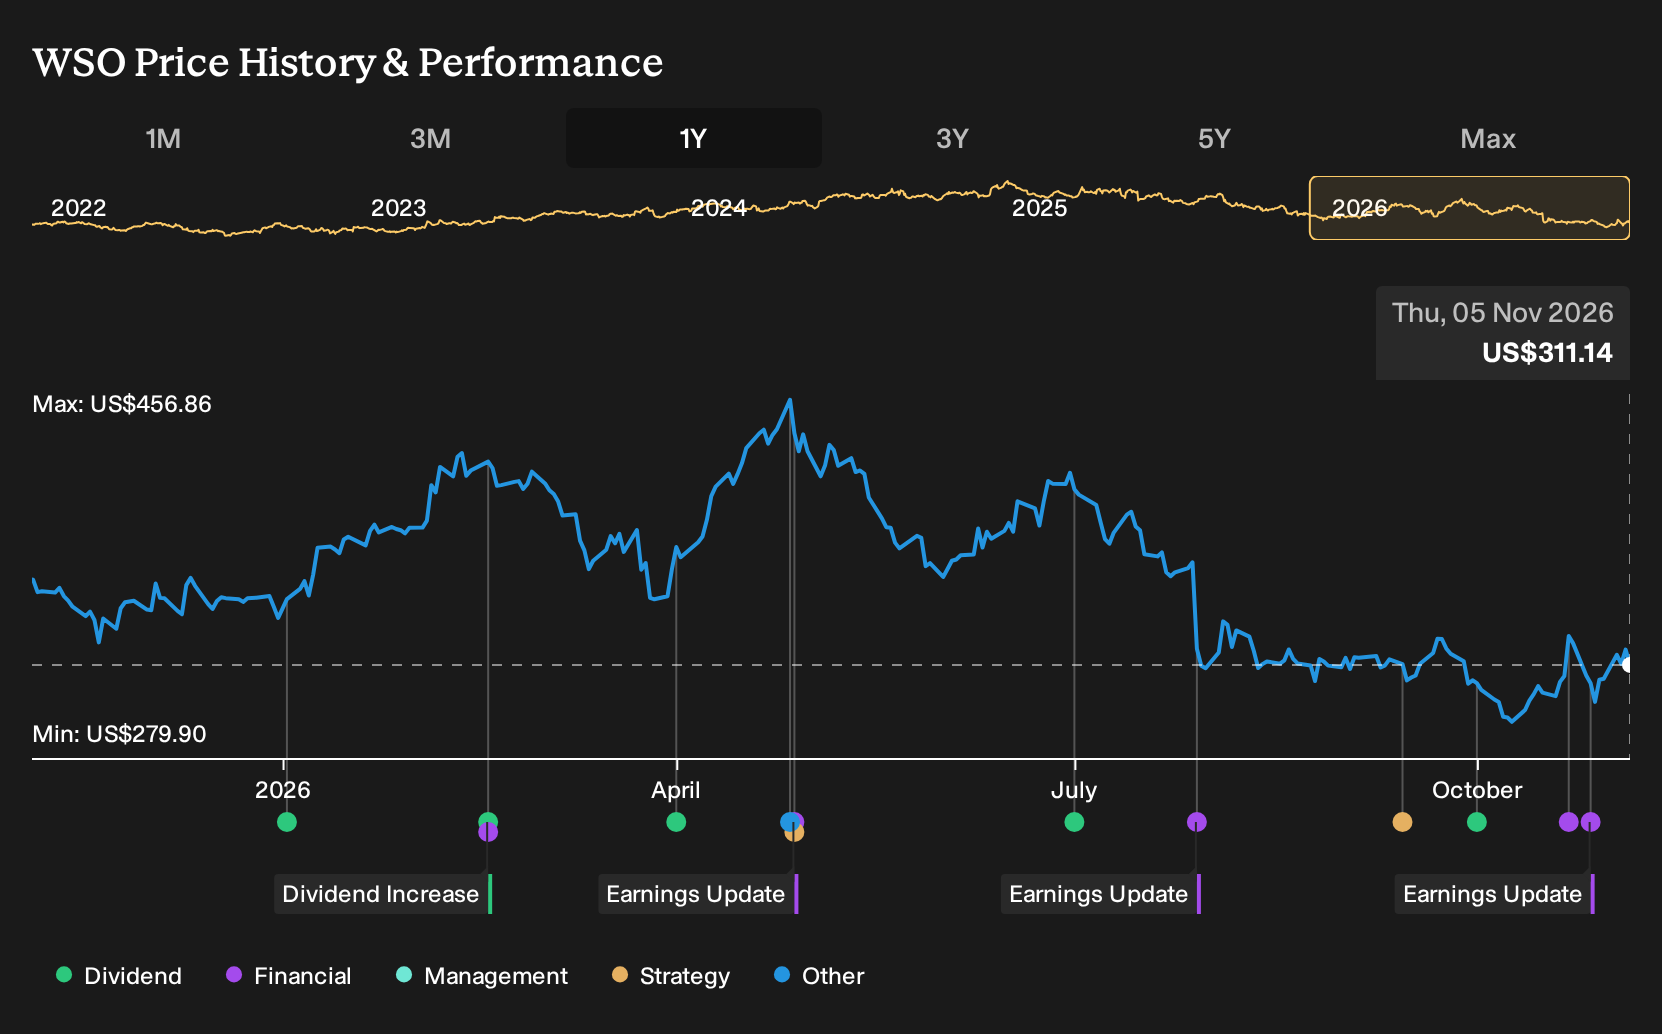
- Watsco reported third quarter 2026 sales of US$2,220.36 million and net income of US$155.37 million, with diluted EPS from continuing operations of US$3.77.
- Across the first nine months of 2026, Watsco showed higher sales alongside lower net income and diluted EPS, which highlights margin pressure and cost or pricing challenges within the distribution model.
- The focus now shifts to how Watsco's investment narrative reflects these mixed earnings, particularly the softer profits alongside higher third quarter sales.
Compare Watsco's margin squeeze with other distributors facing similar trade offs between higher sales and softer earnings by scanning our hand picked 42 high quality undervalued stocks.
Watsco Investment Narrative Recap
To be comfortable owning Watsco, you need to believe the distribution model can keep turning technology, e-commerce and higher efficiency HVAC into healthier margins over time. The latest quarter complicates that story. Sales reached US$2,220.36 million, yet net income and diluted EPS from continuing operations both sat below last year, which keeps gross margin pressure front and center.
The near term swing factor is whether pricing tools and mix shift can offset OEM pricing and A2L related cost friction. The biggest current risk is that these pressures linger into 2027 and keep net profit growth subdued, which could limit flexibility for dividends, technology investment and further acquisitions.
The third quarter 2026 results are the key reference point right now. Across the first nine months, Watsco reported US$5,858.23 million in sales and US$397.78 million in net income from continuing operations, with diluted EPS at US$9.72. Those figures compare to higher earnings in the prior period on lower revenue, which reinforces that execution on pricing and mix remains the core operational task.
That backdrop feeds directly into the existing catalyst list. Higher e-commerce penetration, broader use of OnCall Air and recently acquired distributors such as Jackson Supply and The Granite Group all rely on the distributor proving it can defend or rebuild margin while integrating more volume. If that balance between technology, scale and pricing discipline improves, the earnings profile implied by current forecasts becomes easier to underwrite.
Analysts currently frame Watsco's setup around revenue that is projected to reach US$9.5b and earnings of US$730.4m by 2029, which implies 8.7% yearly top line growth and an earnings increase of about US$293.7m from US$436.7m today.
Uncover how Watsco's fair value points to a 12% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
One bullish twist on Watsco focuses on SupplySync. The most optimistic analysts expected this tool and broader digital adoption to support around US$9.3b in revenue and US$638.0m in earnings by 2029. That is a much stronger story than consensus, and the latest earnings print may either reinforce or challenge that view once estimates are updated.
Explore 3 other Watsco fair value estimates, including one that suggests as much as 61% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Watsco research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Watsco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it possible to evaluate Watsco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Watsco?
If Watsco has sharpened your thinking about margins, balance sheets and cash generation, it can be useful to compare this story with other listed businesses that share some of the traits you care about most.
- If you value financial resilience and want to cut down on balance sheet surprises, start with a list of solid balance sheet and fundamentals (24 results) that already clear basic strength checks.
- If you prefer dependable income and want to see which companies combine yield with size and stability, scan this curated group of 6 dividend fortresses that might suit a dividend focused approach.
- If your priority is finding quality at a reasonable price with less emphasis on excitement and more on fundamentals, filter for 32 resilient stocks with low risk scores that score well on both risk and financial profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com