


EN
Grand Canyon Education (LOPE) Stock Still Looks Like A Bargain Following A 51% Run
Grand Canyon Education has seen its share price slide sharply in recent months, which puts a fresh spotlight on whether the current market value lines up with what the business is earning. After that kind of swing, the key issue for you as a shareholder or prospective buyer is how the stock now stacks up against its own profit engine.
- Over the past 5 years the stock has returned 50.9%, so a lot of long term gain now depends on whether earnings can still support the valuation that journey created.
- Management has been growing service revenue and operating income while expanding the stock repurchase program, which can support earnings per share and may influence how investors judge the price they are paying for those earnings.
- The analysts covering Grand Canyon Education have run their own numbers. See what analysts think Grand Canyon Education's shares could be worth.
The issue now is whether Grand Canyon Education's current share price is justified by the earnings the business generates today and is expected to produce over time.
If you want to test the same earnings question you are asking of Grand Canyon Education across a broader set of ideas, run those checks against 42 high quality undervalued stocks.
Does Grand Canyon Education Look Undervalued on Earnings?
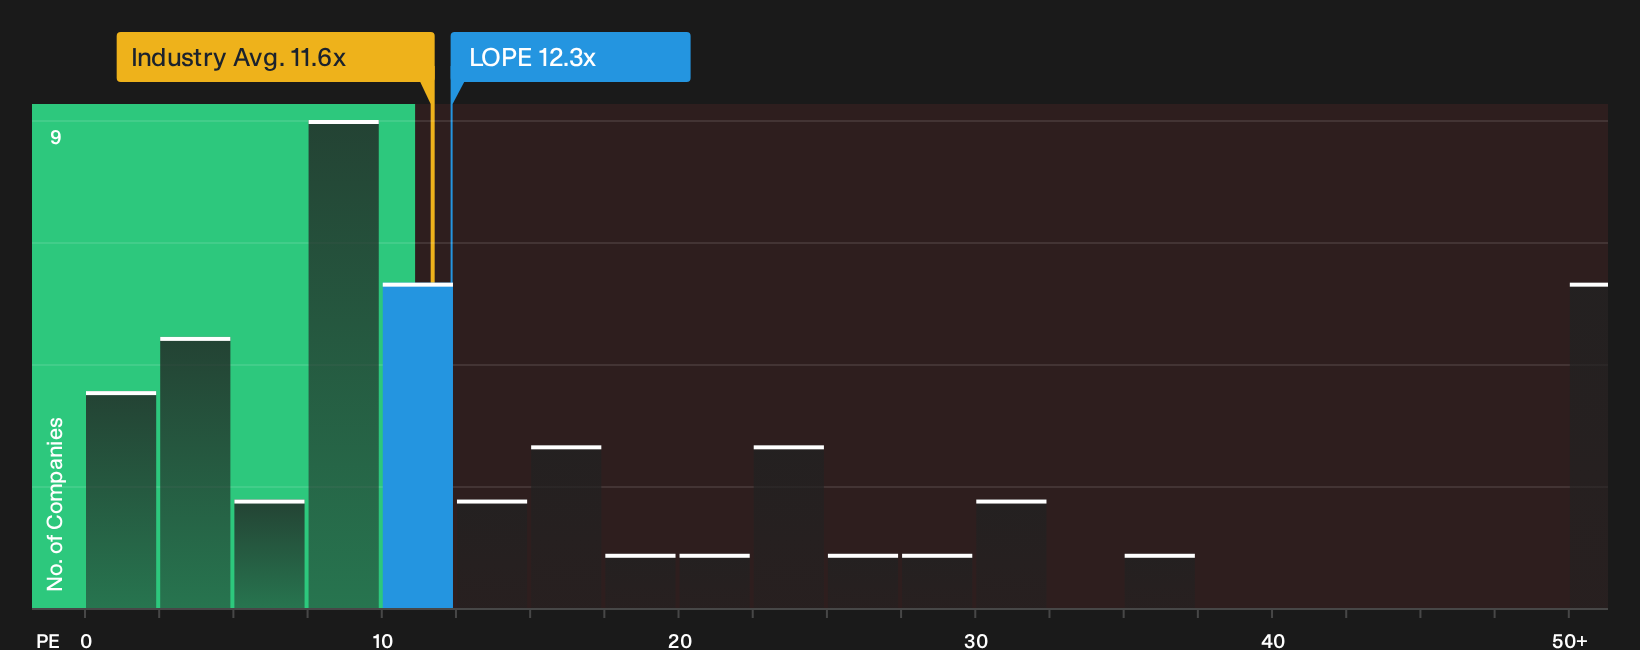
The P/E ratio fits Grand Canyon Education because earnings remain a key anchor for how investors weigh the service-heavy model. On this lens, the stock trades on roughly 12.3x earnings, compared with about 11.2x for peers and 11.6x for the wider Consumer Services group. That puts the valuation modestly above the sector on headline numbers, not at a stretch level but clearly not at the bottom of the pack either.
The fair P/E multiple implied by the valuation model sits above where the market currently prices Grand Canyon Education. This points to the shares trading at a discount to what its growth profile and risk mix would suggest. Because the latest update showed higher operating income and an expanded buyback authorization, the current P/E still leaves the stock valued below that tailored yardstick despite solid recent execution. Explore the numbers behind Grand Canyon Education's P/E valuation.
The Grand Canyon Education Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Grand Canyon Education valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or richer than it does today on the screen. Each scenario links a fair value estimate to a concrete storyline about Grand Canyon Education's potential catalysts and key risks, so you can observe over time which version appears to be unfolding in real life.
One of the top community narratives on Grand Canyon Education: 37% undervalued
"Direct partnerships with over 5,500 employers and the rollout of 20+ new career-aligned programs annually position GCE to capture sustained demand..."
Discover why this Narrative puts Grand Canyon Education at 37% undervalued.
One more Grand Canyon Education puzzle piece before you decide
Earnings multiples and recent execution tell only part of the story. The next clue comes from where professionals think this education services business could be a few years from now, and how that stacks up against today's price. Explore where analysts expect Grand Canyon Education to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com