


EN
Home Depot (HD), Why Is The Retailer Drawing Fresh Attention?
Home Depot (HD) jumped back into the spotlight after the U.S. midterm elections handed Democrats control of both chambers of Congress, as traders quickly linked potential housing affordability policies to the retailer’s renovation focused model.
Recent trading has been jumpy. After the post election surge, Home Depot’s share price has logged a 6.37% 7 day share price return and a 22.06% 30 day share price return, even though the year to date share price move is only 1.19% and the 1 year total shareholder return is down 2.5%. The 3 year total shareholder return of 31.29% and 5 year total shareholder return of 8.05% show how sentiment toward the retailer has swung over different time frames as investors weigh renewed housing policy hopes against ongoing cost and margin questions.
Scan beyond Home Depot and see how other renovation and housing sensitive retailers are setting up in the current policy backdrop with the hand picked 42 high quality undervalued stocks.
After a policy driven jump like this, the real tension for Home Depot investors is simple. Does the current price still leave enough upside to justify the housing and margin risks on the table?
Most Popular Narrative: 9% Undervalued
Against a last close of $349.94, the most followed Home Depot narrative pegs fair value at $385, which implies modest upside and puts more weight on execution than on election headlines.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors (“Pros”), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 17 investors see Home Depot as 9% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot story can crack if housing turnover stays weak for longer, or if lower margin distribution businesses continue to pressure profitability.
Find out about the key risks to this Home Depot narrative.
Another View: What Home Depot’s P/E Is Telling You
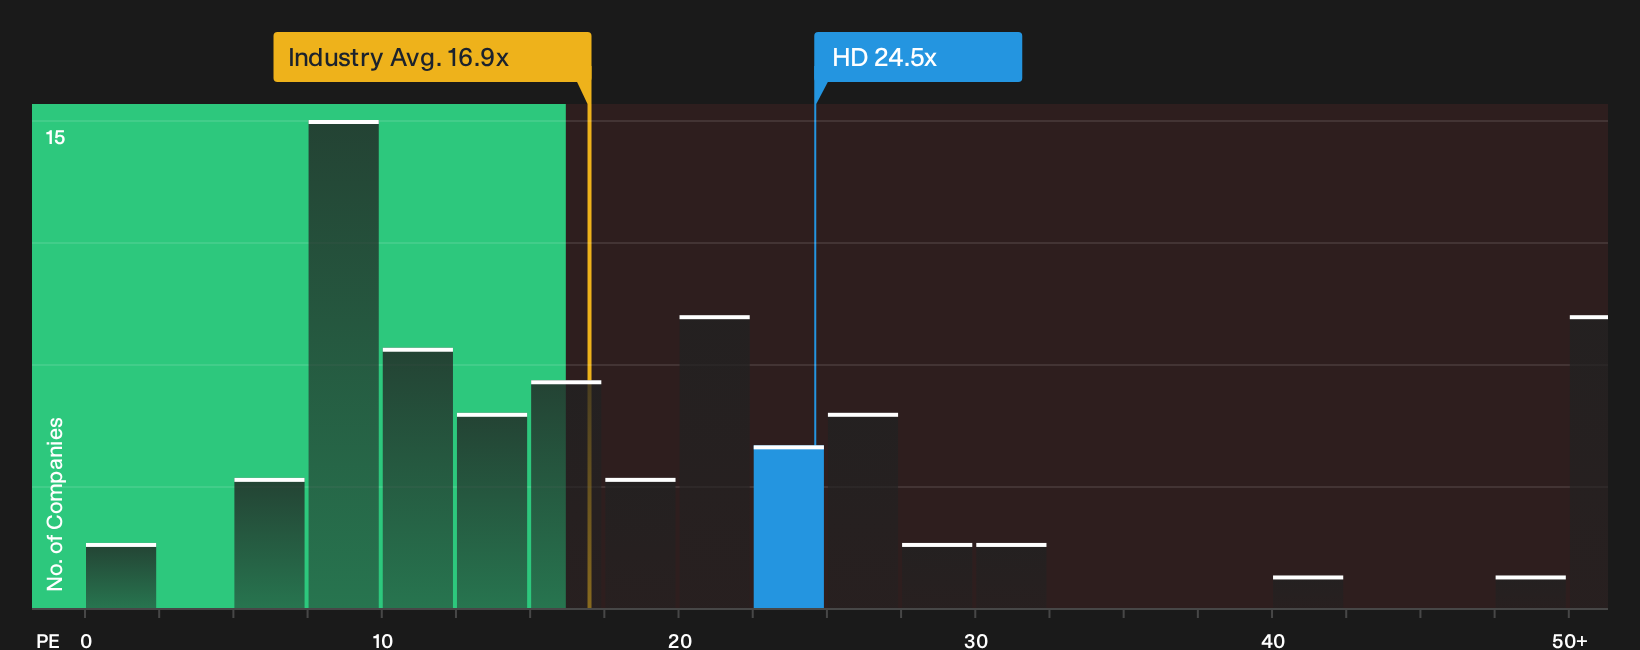
Chart the story using a different tool and the picture changes. On a P/E of 24.5x, Home Depot trades richer than the US Specialty Retail industry at 16.9x and above peer average at 22.8x, yet sits close to its fair ratio of 25.7x. Is that a tight margin of safety or a reasonable premium for quality?
Investors who anchor on earnings multiples rather than cash flow models may want to see what the numbers imply in more detail with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
With sentiment on Home Depot split between opportunity and risk, move quickly and compare the narrative with your own thresholds by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Home Depot?
If you only stop at Home Depot, you risk missing other setups that might fit your risk, income, and quality targets even better in the same session.
- Chase calculated upside by scanning the 21 high quality undiscovered gems that rarely show up on crowded watchlists but still bring solid underlying fundamentals.
- Prioritize resilience by filtering for a 32 resilient stocks with low risk scores that targets businesses with sturdier risk scores when market mood swings sharply.
- Build a sturdier core by running a list of solid balance sheet and fundamentals (24 results) that highlights companies with stronger financial footing to anchor your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com