


EN
ICU Medical (ICUI) Dropped, So What Is Drawing Fresh Attention?
ICU Medical (ICUI) is back in focus after third quarter 2026 results beat earnings and revenue estimates, with net income of US$26.8 million replacing a loss a year earlier.
ICU Medical shares have climbed, with a year to date share price return of 21.02% and a 1 year total shareholder return of 19.61%. However, momentum has cooled recently, with the 90 day share price return down 9.16% and the stock slipping 2.88% after the earnings release. This hints that expectations and perceived risk are resetting after a very strong 3 year total shareholder return of 104.68% and a weaker 5 year total shareholder return of 31.18%.
Scan ICU Medical’s earnings beat alongside other hospital-supplier stocks that are showing resilient cash flows and balance sheets with our curated list of solid balance sheet and fundamentals (24 results)
Bulls point to ICU Medical’s rebound in profitability and cleaner balance sheet. Bears see a stock that has already run hard and cooled on the latest print. Which story does the current valuation lean toward next?
Most Popular Narrative: 12% Undervalued
ICU Medical’s most followed narrative pegs fair value at $191.50, above the last close of $167.65, which frames the stock as undervalued on that model and puts management execution under a brighter spotlight.
Manufacturing network consolidations, portfolio optimization, and realization of integration synergies from the Smiths Medical acquisition are driving visible improvements in gross margin, while further benefits are expected once remaining plant transitions complete over the next year. Sustained gross margin expansion supports higher profitability.
See why 2 investors see ICU Medical as 12% undervalued.
Result: Fair Value of $191.50 (UNDERVALUED)
Still, the recall activity around infusion pumps and oncology kits, along with ongoing tariff pressure, could unsettle confidence in ICU Medical’s margin and cash flow story.
Find out about the key risks to this ICU Medical narrative.
Another View: ICU Medical Through The P/E Lens
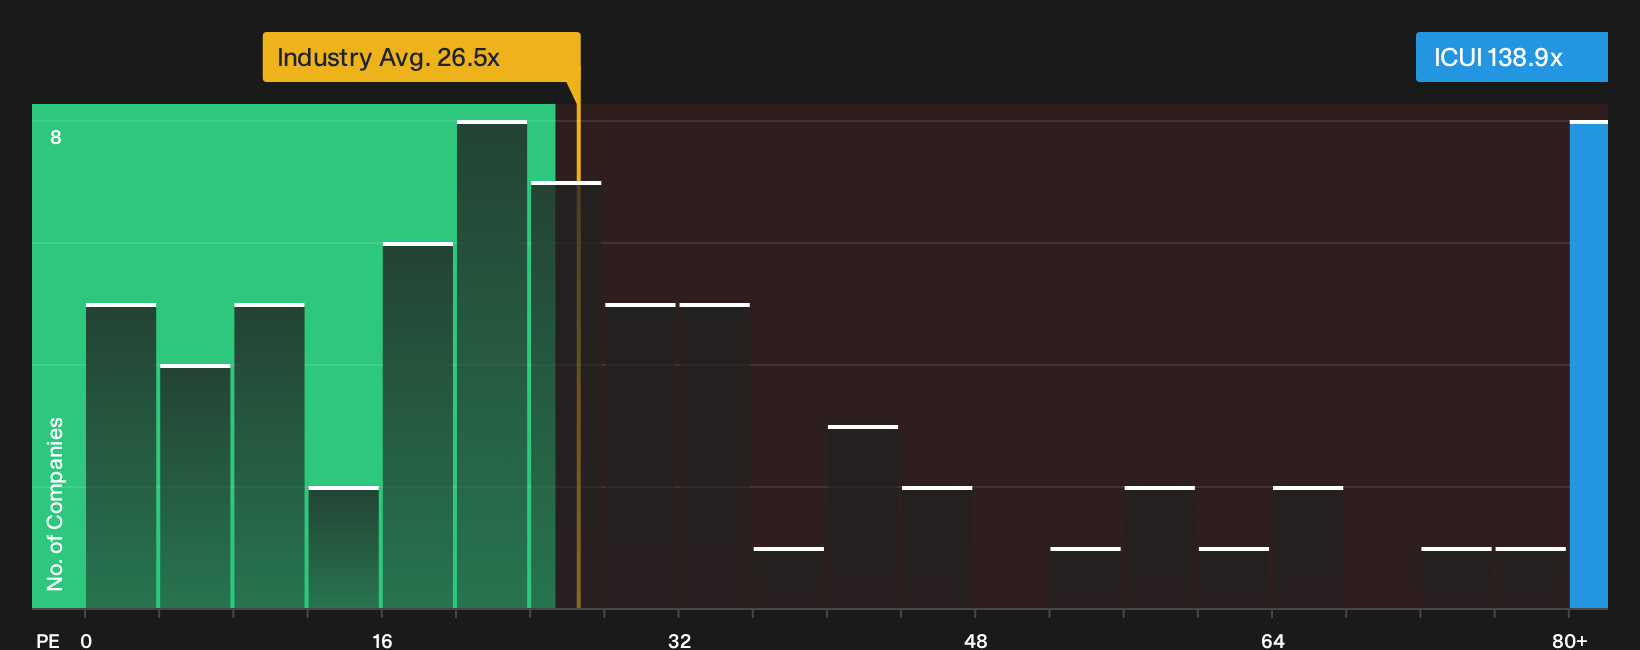
The earlier fair value work for ICU Medical leans on cash flow, yet the market is still pricing the shares on a very rich earnings multiple. ICUI trades on a P/E of 139.3x, while the US Medical Equipment industry sits at 25.3x and direct peers average 34.7x.
Simply Wall St’s fair ratio suggests that, based on regression analysis, a P/E closer to 32.9x is what the market could move toward over time. That is a wide gap between today’s valuation and where a more typical multiple might land, so how comfortable are you with that level of multiple risk if sentiment turns?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the ICU Medical story today. Take a closer look at the underlying data, weigh both the upside and the downside, then pressure test your thesis against our 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond ICU Medical?
If ICU Medical has sharpened your focus on quality, broaden your opportunity set and pressure test your portfolio with a few targeted screens before the next move.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) that filters for financially robust businesses.
- Hunt for mispriced quality by reviewing the 42 high quality undervalued stocks that surfaces stocks where fundamentals and valuation can look out of sync.
- Build a calmer ride through the cycle by using the 32 resilient stocks with low risk scores that highlights companies with lower risk scores and sturdier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com