


EN
Parker Hannifin (PH), What Is Drawing Fresh Attention To The Company?
Parker-Hannifin (PH) just posted record first quarter results, with sales near US$6b and higher earnings per share, while also lifting full year guidance and closing its Filtration Group acquisition.
Despite the record quarter and dividend affirmation on October 28, Parker-Hannifin’s recent share price momentum has cooled. The stock is down 9.4% over the past month and 16.9% over 90 days, while the 1-year total shareholder return is 7.9% and the 5-year total shareholder return is 189.8%.
Scan a hand-picked set of industrial leaders showing strong earnings and cash generation alongside Parker-Hannifin in the 42 high quality undervalued stocks.
Parker-Hannifin’s share price has slipped while earnings, guidance and the Filtration Group deal point in a different direction. Is this about the underlying business, or has sentiment simply swung too far?
Most Popular Narrative: 23% Undervalued
Parker-Hannifin’s most followed narrative pegs fair value at $1,163 per share, which sits above the recent $892.29 close and presents the recent pullback as a disconnect between price and projected cash generation.
The enlarged portfolio of longer-cycle, higher-margin businesses, including Aerospace, Engineered Materials and Filtration, now represents about 65% of pro forma sales and includes recently added filtration assets. This can increase the share of recurring and aftermarket revenue and support more stable earnings and cash generation across economic cycles.
See why 50 investors see Parker-Hannifin as 23% undervalued.
Result: Fair Value of $1,163 (UNDERVALUED)
Still, slower organic revenue growth around 3.2% and premium valuation expectations based on high P/E assumptions could quickly challenge this Parker-Hannifin upside story.
Find out about the key risks to this Parker-Hannifin narrative.
Another View On Parker-Hannifin’s Valuation
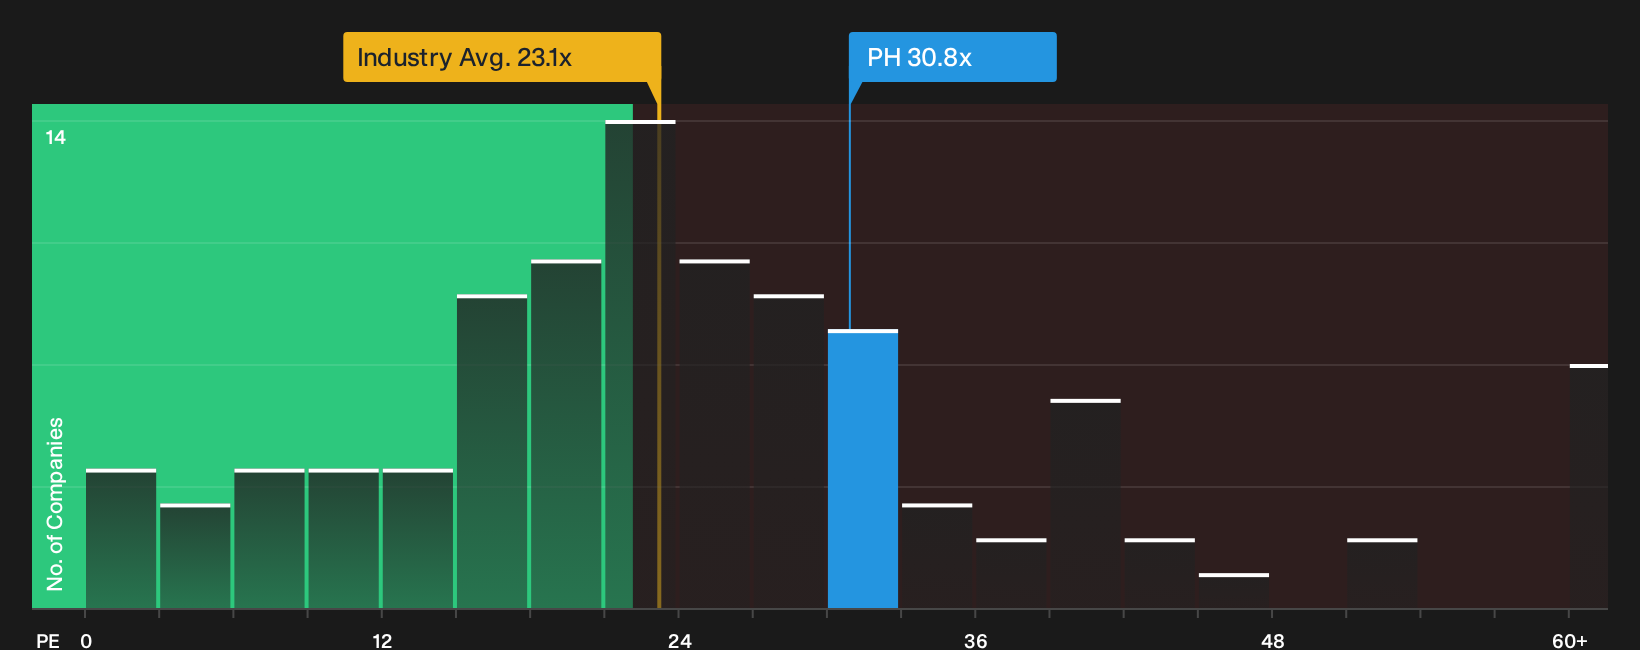
The first narrative leans on future cash flows. A simpler lens tells a different story. Parker-Hannifin trades on a P/E of 30.8x, while the fair ratio is 29.6x, the US Machinery industry averages 23.1x and peers sit near 22.6x. That premium suggests less margin for error than a pure DCF might imply. Which signal do you trust more when expectations are already this high?
See what the numbers say about this price in our valuation breakdown, then weigh how comfortable you are with paying well above sector and peer averages for Parker-Hannifin’s current earnings profile See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Parker-Hannifin is clearly split, so consider acting promptly and evaluate the data yourself before the mood shifts again, starting with the balance of 4 key rewards and 2 important warning signs.
Looking for more Parker-Hannifin style investment ideas?
If Parker-Hannifin has your attention, do not stop here. Broaden your watchlist with fresh opportunities that match your risk, income and quality preferences.
- Target potential upside by scanning a hand-picked set of high quality undervalued candidates with the 42 high quality undervalued stocks.
- Lock in income ideas by reviewing a focused pool of resilient payers through the 6 dividend fortresses.
- Dial down risk by filtering for companies with robust finances using the 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com