


EN
What Artivion (AORT)'s Easing Pricing Fears Means For Shareholders
- Artivion reported third quarter 2026 revenue of US$123.79 million and a net loss of US$7.93 million, with nine month revenue at US$365.88 million and a net loss of US$20.02 million.
- The mix of higher sales and a swing from profit to loss highlights pressure on Artivion's cost base and earnings quality as it scales.
- We will now see how Artivion's investment narrative could be shaped by easing drug pricing regulation after the recent election outcome.
See how Artivion compares with its sector peers by checking out a curated group of healthcare companies with resilient balance sheets through our list of solid balance sheet and fundamentals (24 results).
Artivion Investment Narrative Recap
To stay invested in Artivion, you need to be comfortable with a business that is growing its top line while still posting losses. The big belief is that products like On X valves, AMDS and the broader aortic portfolio can support demand even as hospitals watch costs closely. The short term swing from profit to loss keeps execution on pricing, mix and operating expenses in sharp focus.
The key near term catalyst is whether Artivion can keep expanding usage of its existing portfolio without letting costs absorb all of the additional revenue. The biggest current risk is that higher R&D, regulatory and selling expenses required to support this product set keep net income in the red, particularly with a leveraged balance sheet already limiting flexibility.
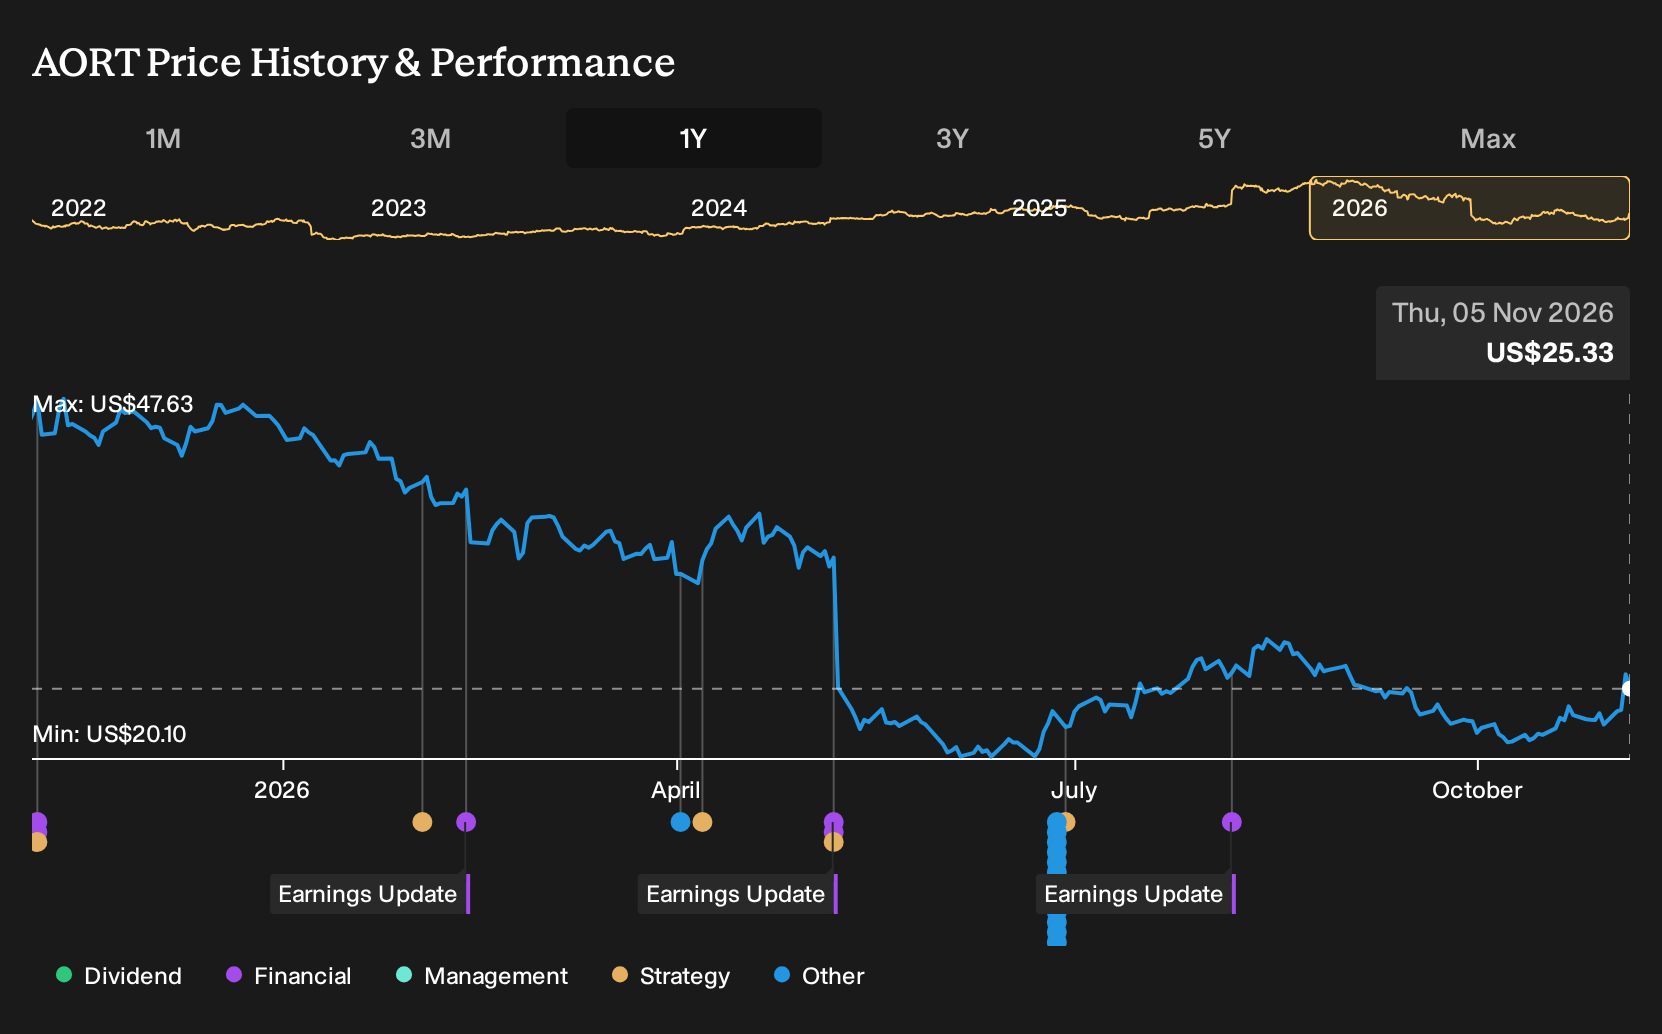
The latest quarterly result is the clearest data point to work with. Artivion reported third quarter 2026 revenue of US$123.79 million and a net loss of US$7.93 million. For the first nine months of 2026, revenue was US$365.88 million with a net loss of US$20.02 million. That combination of higher sales and fresh losses puts the near term earnings trajectory under scrutiny.
In practical terms, this earnings report links directly to the main catalyst investors watch, which is the path to consistent profitability while funding product launches and clinical programs. The move into a loss making position increases the importance of cost control, pricing resilience and regulatory execution across BioGlue, AMDS, NEXUS and other devices, particularly as hospital and payer cost pressure remains a structural risk.
Artivion's current earnings of US$11.7 million are set against analyst projections for US$619.8 million in revenue and US$44.7 million in earnings by 2029, which implies revenue expanding at 10.6% per year and profits rising by about US$33.0 million if that consensus plays out.
Uncover why Artivion's fair value indicates a 66% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Artivion’s regulatory pipeline front and center. Bullish analysts focused on approvals for products like NEXUS and Arcevo LSA and, before this earnings release, were modelling about US$650.4 million of revenue and US$49.3 million of earnings by 2029. The key takeaway is that opinions span a wide range, so consider using this latest loss as an opportunity to reassess which perspective you find most convincing.
Explore 2 other Artivion fair value estimates, including one that suggests as much as 116% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Artivion research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Artivion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Artivion's overall financial health at a glance.
Looking for more investment ideas beyond Artivion?
Once you have a view on Artivion, it can help to cross check that thesis against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter the market quickly so you can focus on groups of companies that match what you care about most.
- If you want stability to be the starting point, focus on businesses with stronger finances and check out this list of solid balance sheet and fundamentals (24 results).
- For investors hunting for mispriced quality, you can instead look at companies that pair robust fundamentals with attractive valuations and review this 42 high quality undervalued stocks.
- If reliable cash returns matter most to you, concentrate on income focused ideas and scan this 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com