


EN
Top 3 Japanese Growth Stocks To Watch In November 2026
Japanese growth stocks just went through a sharp reality check as AI related shares dragged the Nikkei down more than 6% in a single session. Sharp pullbacks like this often leave high quality growth companies trading at prices that do not fully reflect their long term plans. This article walks through three Japanese high growth opportunities that analysts and management still back with conviction.
The three Japanese growth ideas below are only a starting sample, as the full High Growth High Conviction screen surfaced 24 more companies with equally compelling narratives that are not covered here.
To see the complete picture and quickly identify which fast growing businesses fit your own risk and return preferences, head straight into the High Growth High Conviction screener to filter and analyze the highest conviction plays.
Union Tool (TSE:6278)
Overview: Union Tool designs and sells precision PCB drilling and routing tools and other cutting equipment that support electronics and semiconductor manufacturing worldwide.
Operations: Union Tool generates about ¥31,087 million in Asia and ¥30,974 million in Japan, with smaller contributions from Europe and North America.
Market Cap: ¥210.0 billion
Union Tool fits directly into the screener theme through its PCB drilling and routing tools tied to electronics and semiconductor assembly. Earnings are up 64.3% and margins are near 18.8%. Management is pursuing multi year factory expansion and upgraded sales guidance, so growth increasingly depends on how one unseen pressure shapes the economics of that new capacity.
That unseen pressure is exactly what the 3 key rewards and 1 important major warning sign is intended to capture, showing where Union Tool’s capacity bets could either compound or compress returns.

Sansan (TSE:4443)
Overview: Sansan runs a cloud platform that turns business cards and related activity into shared enterprise contact data, driving recurring SaaS revenue.
Operations: Sansan generates about ¥48,865 million from Sansan and Bill One, ¥7,143 million from Eight, and ¥446 million from other services, almost entirely in Japan.
Market Cap: ¥282.6 billion
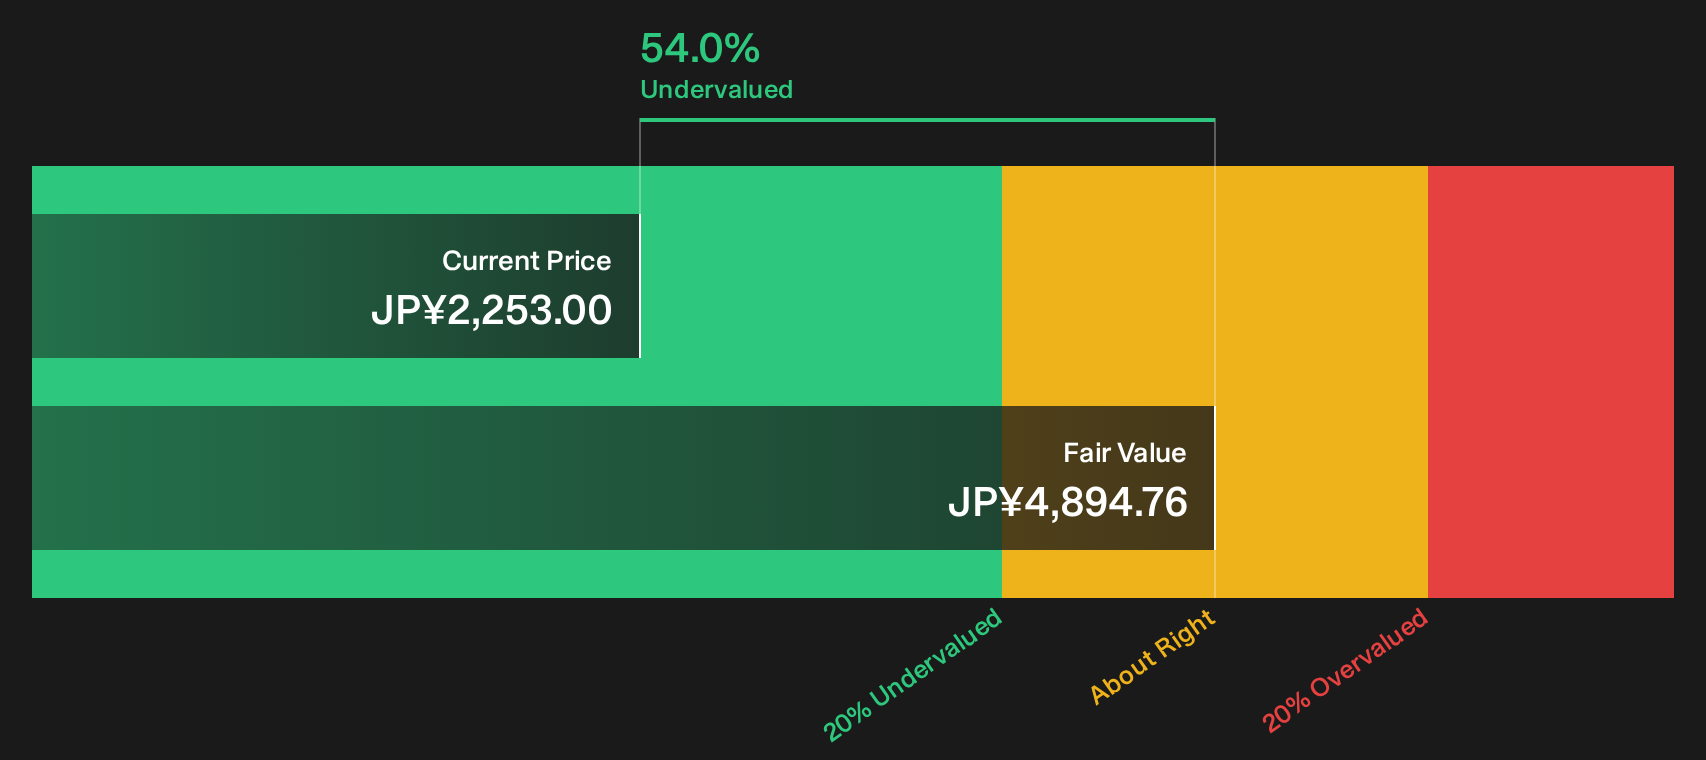
Sansan fits directly into the High Growth High Conviction theme through its contact management SaaS. It pairs forecast 23.4% annual earnings expansion with improving 14.3% net margins and trades at roughly a 54% discount to estimated fair value. The key question is what happens if that profitability trend stops moving in step with revenue growth.
If that margin and earnings rhythm ever decouples, the 3 key rewards and 1 important warning sign shows where Sansan’s growth story could either accelerate or quietly stall.
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor probe cards and wafer testing equipment, plus inspection tools for liquid crystal displays and body measurement.
Operations: Micronics Japan generates about ¥84,868 million from probe cards and ¥1,391 million from TE business, primarily across South Korea, Taiwan and Japan.
Market Cap: ¥348.9 billion
Micronics Japan is directly linked to the High Growth High Conviction theme through essential probe cards and wafer test gear, with trailing earnings up 89.4% and forecast revenue growth around 23% alongside roughly 21.7% margins and a 20.5% ROE. Investor interest centers on how this probe card demand cycle affects those returns if a single key assumption does not hold.
If that assumption breaks, the 2 key rewards and 2 important warning signs (1 is major!) shows where Micronics Japan’s test cycle could quietly flip from tailwind to stress test for returns.

Seeking Alternatives Before The Crowd?
Fresh themes move fast. Breakout stories gain momentum, laggards keep dropping and under the radar ideas do not stay quiet for long. Scan these curated lists and get in early.
- Spot sturdy businesses built to handle shocks by reviewing a curated list of solid balance sheet and fundamentals (23 results) while it still flies under most investors' radar.
- Explore dependable income opportunities by sifting through a focused 28 dividend fortresses before yield hunters catch up and affect the most attractive entry points.
- Track companies involved in the next energy buildout by checking the hand picked 16 nuclear energy infrastructure stocks while the theme is still forming and pricing remains in flux.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com