


EN
Earnings Revisions Might Change The Case For Investing In Annaly Capital Management Stock (NLY)
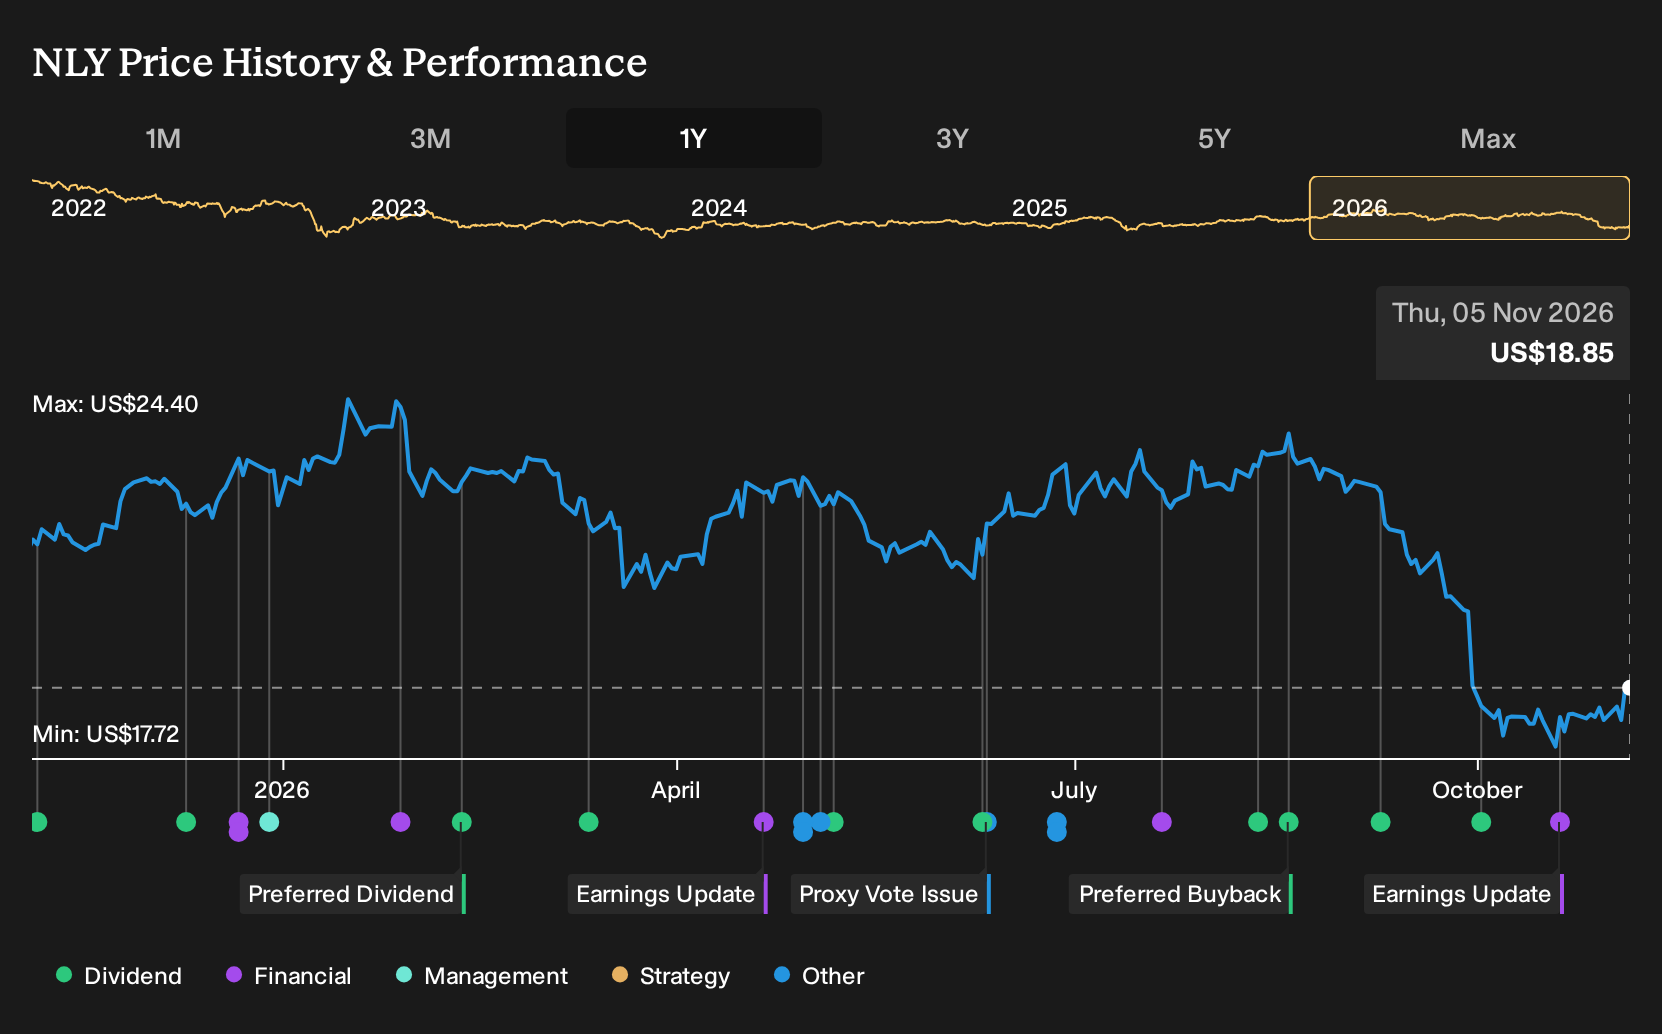
- Annaly Capital Management recently moved above its 20 day moving average while analysts raised earnings estimates for the current fiscal year, pointing to shifting expectations around its mortgage finance earnings power.
- This combination of technical strength and upgraded profit forecasts highlights how investors are reassessing the durability of Annaly's spread income and hedging approach, rather than focusing only on short term signals.
- We will examine how Annaly Capital Management's investment narrative is affected by this move above the 20 day moving average.
Scan how Annaly Capital Management compares with other high yield opportunities by reviewing our hand picked list of 6 dividend fortresses.
Annaly Capital Management Investment Narrative Recap
To own Annaly Capital Management, you need to be comfortable with a mortgage finance business that leans heavily on spread income, hedging and access to wholesale funding. The key near term swing factor is how agency MBS spreads and financing costs evolve, which directly affects net interest income across the Agency, Residential Credit and MSR segments.
The move above the 20 day moving average signals a shift in short term sentiment, but it does not materially change the fundamental catalyst or the main risk. Earnings still hinge on managing interest rate volatility, hedging costs and leverage, while the biggest vulnerability remains that debt and funding needs are not well covered by operating cash flow.
The most relevant data point tied to this price action is the recent set of upward revisions to Annaly Capital Management earnings estimates for the current fiscal year. Those changes reflect higher expectations around spread income and portfolio earnings power across Agency, Residential Credit and MSR, rather than any single transaction or capital move.
For you as a shareholder, the connection is straightforward. If the portfolio mix and hedging framework can support those higher earnings expectations while dealing with rate swings, then the recent technical strength looks aligned with the earnings outlook. If spreads compress again or hedging costs stay elevated, that same technical signal could quickly lose support from the underlying business.
Annaly Capital Management Forecasts Behind The Technical Signal
Annaly Capital Management's narrative projects US$2.7b revenue and US$2.3b earnings by 2029. This rests on analysts assuming 3.7% yearly revenue growth and an earnings increase of about US$0.4b from US$1.9b today.
Those headline numbers frame how much faith is being placed in the current playbook. Analysts are building in revenue growing at 3.7% a year over the next few years, while profit margins are expected to move from 78.5% today to 86.4% by 2029. For a mortgage finance vehicle that lives and dies by spread income, that margin shift matters more than the modest top line growth.
Earnings are at the center of the story. The consensus view looks for net income to move from US$1.9b today to US$2.3b by around 2029, with the most optimistic forecasts closer to US$2.5b. That roughly US$0.4b gap between current and expected earnings is what gives the recent move above the 20 day moving average some fundamental backing, because it ties short term price strength to a concrete profit hurdle rather than to trading noise.
Valuation assumptions tell you what needs to go right for Annaly Capital Management to justify those expectations. The consensus targets a P/E of 11.9x on the projected 2029 earnings, compared with 8.8x today and about 9.1x for the broader US mortgage REIT group. That implies not just higher earnings, but also a richer multiple, so the thesis relies on both the income statement and market perception working in favor of the stock.
On those forecasts, analysts see revenues at US$2.7b and earnings at US$2.3b in 2029. This anchors a consensus price target of US$24.0 per share. With the recent share price quoted at US$22.8, that target is only 5.0% higher. This suggests the average analyst view is that the security is roughly aligned with their base case. For you, that small gap means the debate is less about a big valuation disconnect and more about whether you accept the revenue, margin and P/E assumptions sitting behind the models.
Uncover why Annaly Capital Management's fair value indicates a 27% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$21.14 to US$33.02, so some members see Annaly Capital Management close to current pricing while others pencil in much higher figures. When you set those views against risks like prolonged interest rate volatility or wider mortgage spreads, you can test which scenarios you find most plausible. Opinions differ sharply, so explore several of these community perspectives before deciding how Annaly fits your portfolio.
Explore 2 other Annaly Capital Management fair value estimates, including one that suggests it could be worth just $21.14.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Annaly Capital Management research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Annaly Capital Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Annaly Capital Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Annaly Capital Management?
If Annaly Capital Management helps you frame what matters in a high yield mortgage finance play, broadening your watchlist can sharpen that framework even more. Use the Simply Wall St Screener to spot other opportunities that fit different risk and income profiles, then compare them against what you see in Annaly.
- For investors focused on stability first, review a 32 resilient stocks with low risk scores that may better align with a capital preservation mindset.
- If balance sheet strength is a priority, scan our list of solid balance sheet and fundamentals (24 results) to see which companies pair financial resilience with consistent fundamentals.
- When you want growth potential that is not already crowded, consider a 21 high quality undiscovered gems that highlights underfollowed businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com