


EN
Is Public Storage (PSA) Fairly Valued After Raising Full Year Guidance And Dividends?
Public Storage (PSA) just paired a raised full year outlook with fresh dividends on both its common and preferred shares, giving investors new information on income potential and management’s current view of the business.
Public Storage’s raised guidance and fresh dividends arrive after a strong run, with a 1-month share price return of 19.12% and a year to date share price gain of 31.75% that points to building momentum. The 3-year total shareholder return of 55.81% shows how income and price gains have combined over time as investors reassess both growth potential and risk around the updated outlook.
Scan for other real estate income plays showing similar guidance shifts and fresh dividend signals with our hand picked 6 dividend fortresses.
The sharp move in Public Storage after refreshed guidance and new dividends pulls forward a lot of optimism. Does it make more sense to commit at today’s price, or to wait for a calmer entry once the valuation math is clear?
Most Popular Narrative: 3% Overvalued
Public Storage closed at $340.50 against a widely followed fair value view of $329.00. The latest guidance and dividend moves are being weighed against a narrative that still sees the stock as slightly ahead of that fair value based on a 7.67% discount rate.
Large portfolio additions, including the US$10.5b acquisition of National Storage Affiliates and the US$1.2b purchase of Public Storage Canada, are expected to provide scale benefits, targeted synergies, and new market exposure that can support future NOI and FFO per share.
Expansion of PS Next and PS4.0 initiatives, such as high digital adoption, AI assisted customer service, and machine learning based staffing that has reduced field labor hours and payroll expense, is expected to support operating efficiency and margin resilience as the platform matures.
See why 43 investors see Public Storage as 3% overvalued.
Result: Fair Value of $329 (OVERVALUED)
Still, integration risk around the US$10.5b National Storage Affiliates deal and pressure in weaker Sunbelt markets could quickly challenge the current Public Storage narrative.
Find out about the key risks to this Public Storage narrative.
Another View: Cash Flow Lens On Public Storage
The fair value narrative built around a $329 price target and valuation ratios says Public Storage is a bit ahead of that mark. A second lens tells a different story. The SWS DCF model estimates future cash flows point to a value of $410.96, which presents PSA as undervalued on that basis.
The gap between a $329 fair value view and a $410.96 cash flow estimate leaves a practical question for investors. Which signal deserves more weight, the earnings based target or the long term cash flow math, when considering the level of risk associated with PSA at $340.50?
Look into how the SWS DCF model arrives at its fair value.
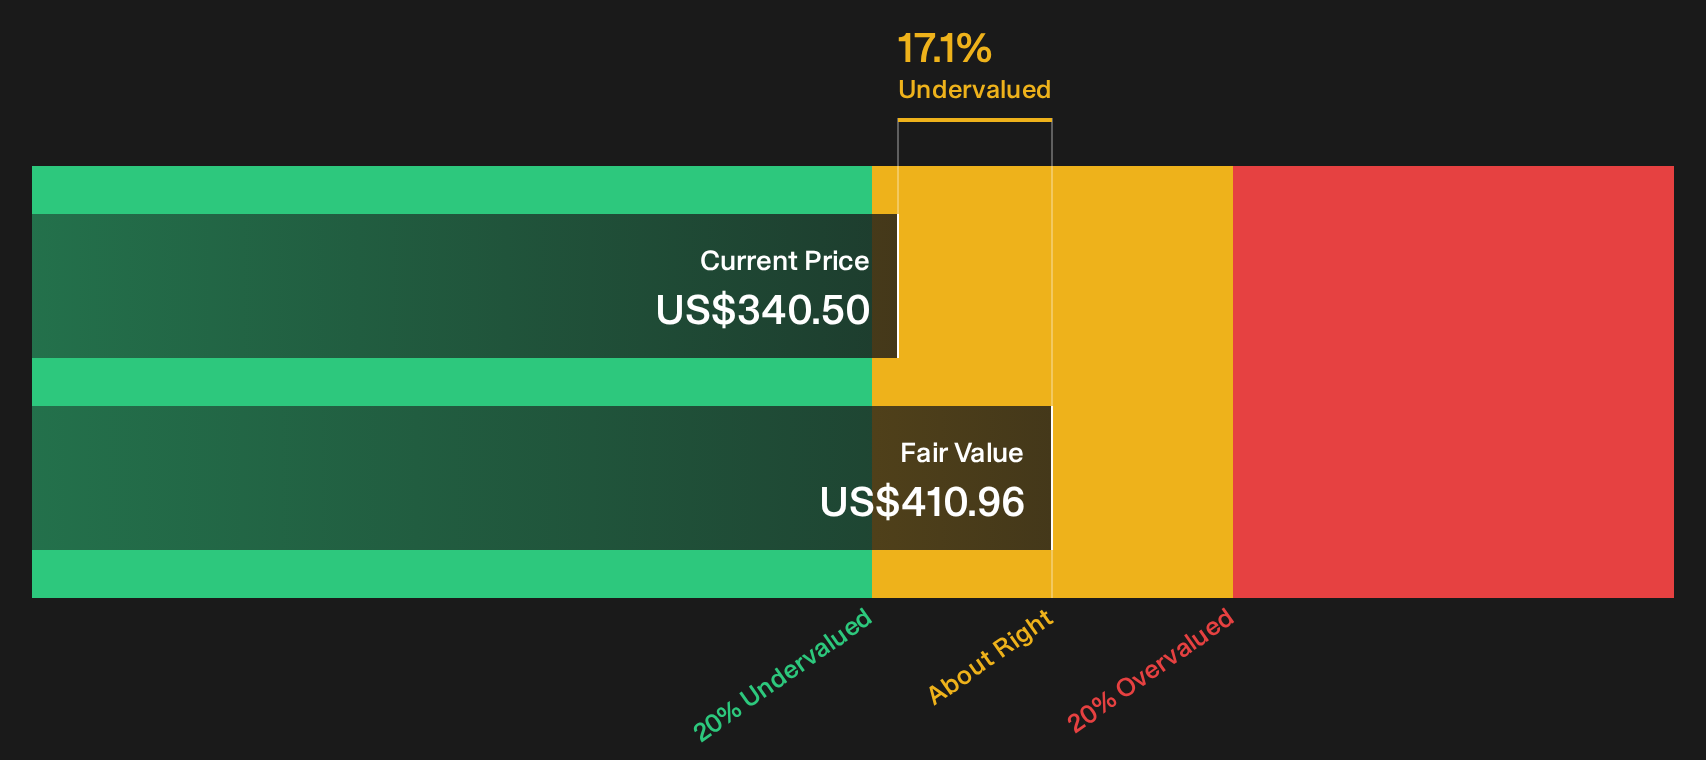
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Public Storage for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Public Storage leave you torn between potential upside and downside, consider quickly reviewing the full picture and weighing both sides using 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Public Storage?
Do not stop at Public Storage. Fresh opportunities often appear where pricing, quality, and risk come together, and a focused stock search can surface ideas you may otherwise miss.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations using the 42 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with robust balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by searching for lesser known quality opportunities across the market with the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com