


EN
Is Datadog (DDOG) A Bargain After Soft Guidance Hit Its Valuation?
Why Datadog’s strong quarter rattled the stock
Datadog (DDOG) beat third quarter expectations on both earnings and revenue, then unsettled investors with fourth quarter guidance that pointed to roughly flat sales and softer operating margins despite solid customer metrics.
The guidance spelled out revenue of US$1.19b to US$1.20b for the coming quarter and US$4.515b to US$4.525b for 2026 as a whole. That outlook framed the entire market reaction more than the headline beat did.
That cautious outlook hit a stock that had already pulled back sharply, with a 1 day share price return of down 7.48% and a 7 day move of down 25.79%. This comes even though the year to date share price return is up 30.52% and the 3 year total shareholder return is up 68.45%, so recent momentum is clearly fading after a strong multi year run.
Recent headlines around Datadog now focus less on the Q3 beat and more on how flat near term guidance, heavier investment in AI tools like Scout 1.0 and Bits, and concentration in large customers are feeding into a 30 day share price return of down 35.65% and a 1 year total shareholder return of down 8.70% as investors reassess both growth potential and risk.
Compare Datadog’s post earnings reset with other software names by screening for 53 AI infrastructure stocks that could see sentiment swing just as sharply on their next guidance update.
Datadog appears to be a high quality platform business based on this quarter, yet the share price has dropped sharply. Has the recent reset finally left the stock at a sensible valuation?
Most Popular Narrative: 40.3% Undervalued
Datadog last closed at $174.60 while the most followed narrative pegs fair value at about $292 per share. The story hinges on whether that gap is justified by AI and platform economics or closed by execution risk and customer concentration.
Customer movement toward autonomous operations and AI assisted development, highlighted by Bits AI and a roadmap for AI driven detection, investigation and remediation, can increase reliance on Datadog telemetry and analytics and support premium pricing, revenue growth and potentially higher operating margins.
See why 179 investors see Datadog as 40% undervalued.
Result: Fair Value of $292 (UNDERVALUED)
Still, a single nine figure customer already trimming usage, along with ongoing insider selling around US$320m in stock, could quickly challenge the optimistic Datadog narrative.
Find out about the key risks to this Datadog narrative.
Another way to look at Datadog’s valuation
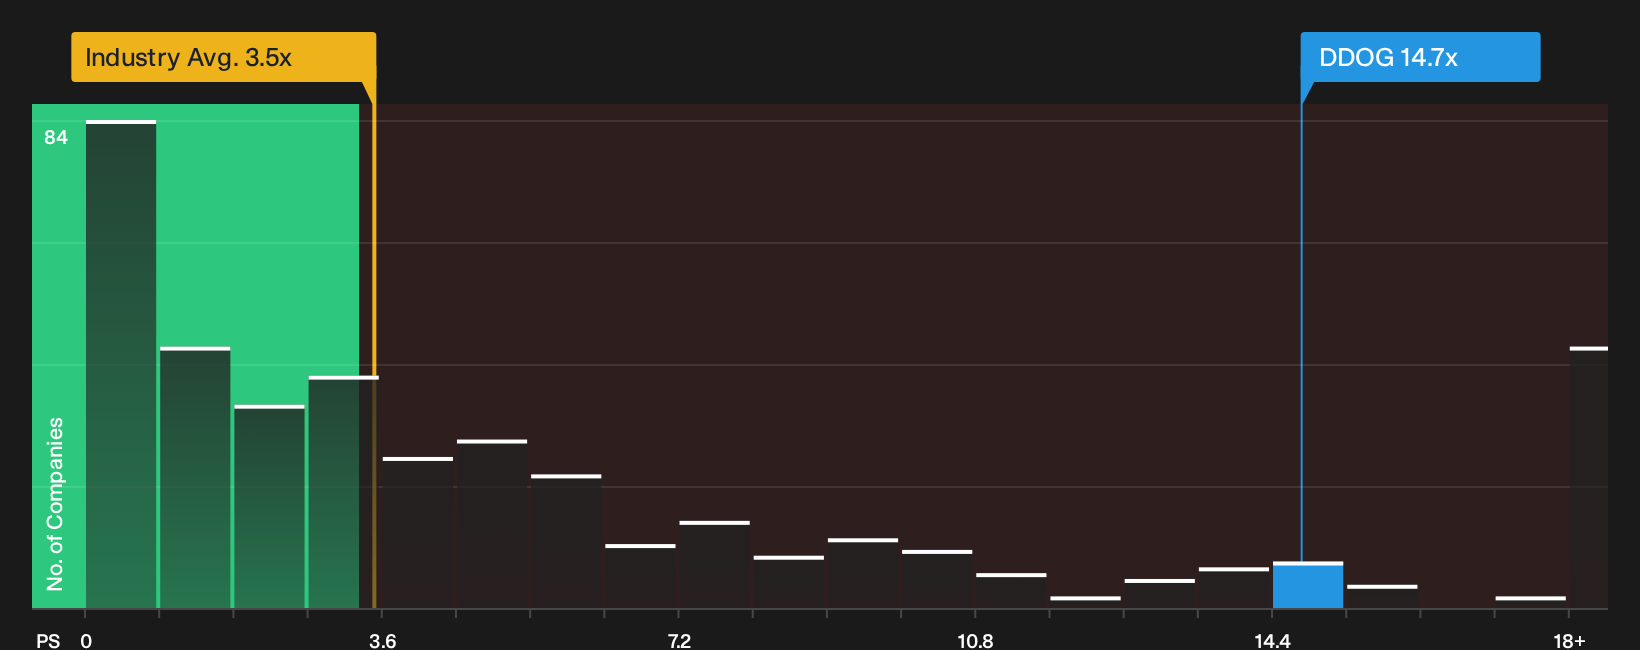
The fairness check using P/S paints a very different picture for Datadog. The stock trades at about 14.7x sales, while the US Software group sits nearer 3.5x and close peers average 7.8x. The fair ratio is 13.3x. That gap points to richer expectations and raises the question: How much execution miss would it take for the multiple to drift toward that fair ratio level?
To see how the current pricing stacks up against the underlying numbers and expectations, take a closer look at our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on Datadog so far. If you want to move quickly and form your own take, start with the balance of 4 key rewards and 2 important warning signs
Looking for more Datadog style investment ideas?
If Datadog has you rethinking your watchlist, broaden your view with a few targeted screens that surface very different kinds of opportunities before the crowd spots them.
- Target potential mispricing by scanning a curated 42 high quality undervalued stocks that combine solid fundamentals with a price that does not fully reflect them.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (24 results) that can better handle pressure when conditions get tougher.
- Get ahead of the market by reviewing a 21 high quality undiscovered gems that have quality metrics but limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com