


EN
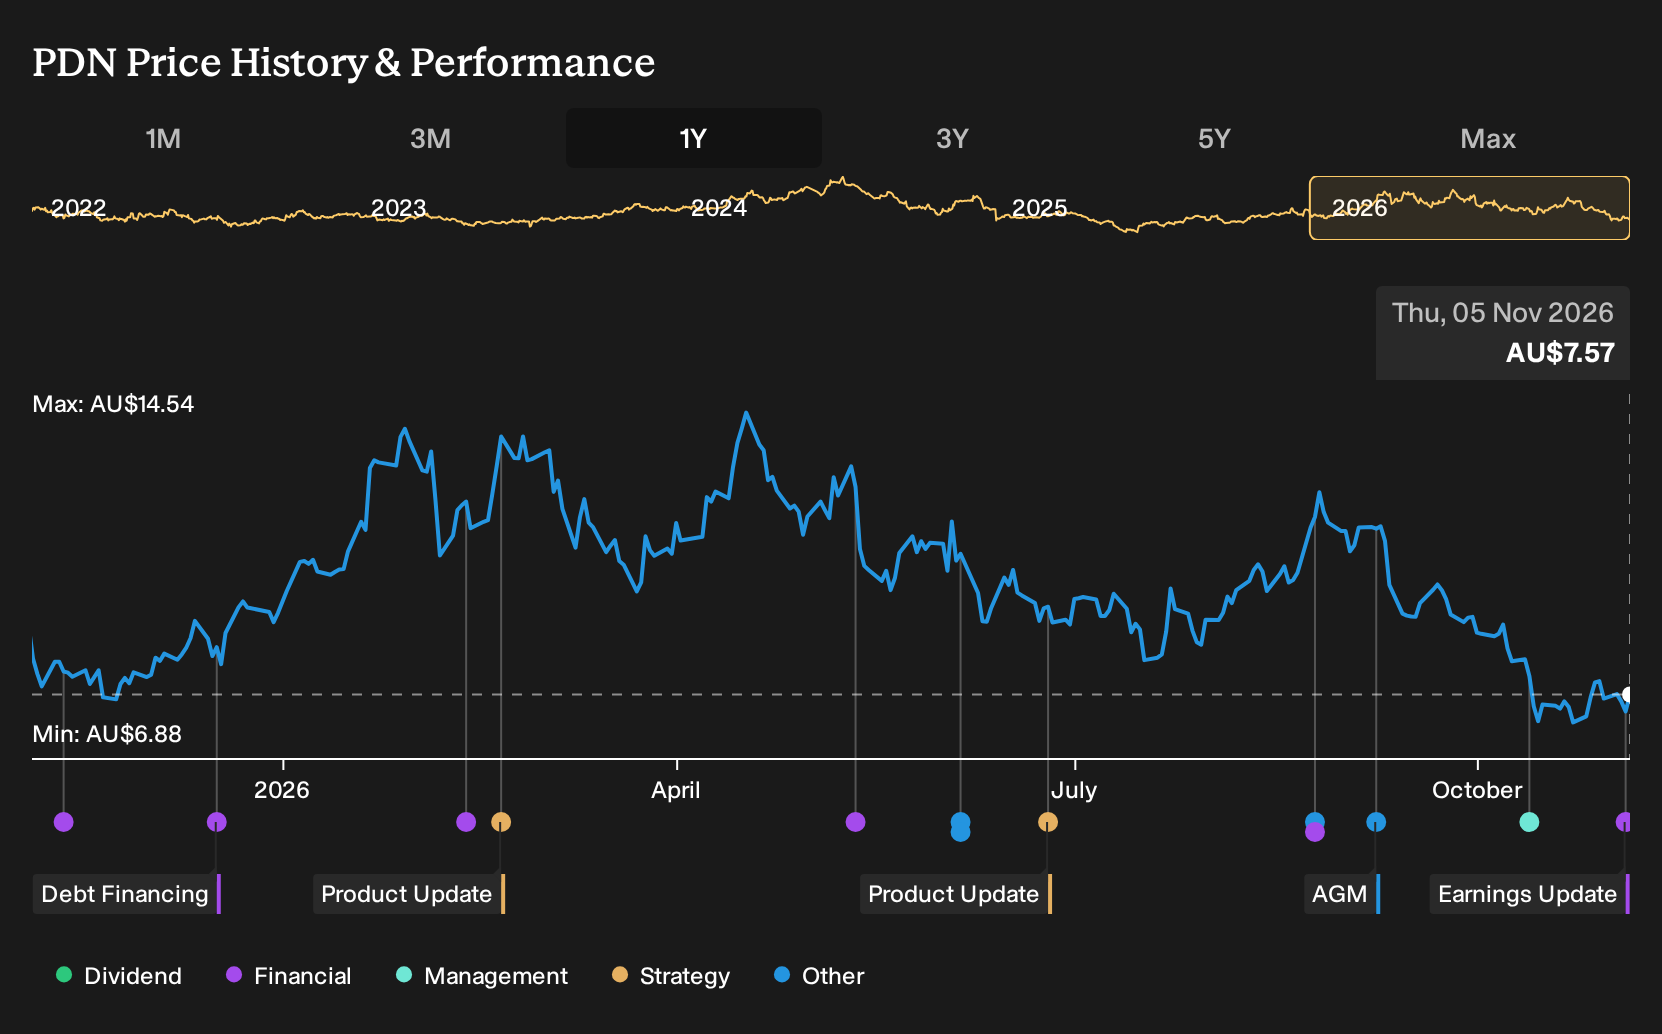
Why Paladin Energy Stock Is Up 5.9% And What's Next After Earnings Profit Swing
- Paladin Energy reported first quarter 2026 sales of US$92.38 million and net income of US$4.29 million, with basic earnings per share from continuing operations of US$0.0095.
- The swing from a prior net loss to profit, supported by published interim reports and project updates, reflects changes in execution across Paladin Energy’s uranium assets.
- We will now look at how Paladin Energy's investment narrative could be influenced by the sharp uplift in quarterly sales and profitability.
Scan how Paladin Energy’s latest uranium earnings shift compares with peers by reviewing our hand picked 16 nuclear energy infrastructure stocks in the wider nuclear infrastructure space.
Paladin Energy Investment Narrative Recap
To own Paladin Energy, you have to be comfortable with a uranium producer that is still bedding down Langer Heinrich while pouring money and effort into Patterson Lake South. The latest quarter moves the story from concept to execution. Higher quarterly sales and a swing to profit show the producing asset can support the development pipeline when operations cooperate.
The key short term catalyst remains cost and recovery performance at Langer Heinrich. That is where cash flow for future projects is earned. The biggest risk stays the same: any prolonged cost pressure at the mine or fresh delays in Canadian permitting for Patterson Lake South could narrow the runway implied by today’s project plans.
The unaudited Condensed Interim Financial Report and Management’s Discussion and Analysis for the three months to 30 September 2026 is the announcement that matters most here. It ties the US$92.38 million in sales and US$4.29 million in net income to actual site execution at Langer Heinrich and to how management is pacing spend across the portfolio.
For you as a shareholder or prospective investor, that disclosure sits right alongside the ongoing development of Patterson Lake South. Progress there, including its reported all in sustaining cost metrics and planned output profile, remains central to the long term uranium thesis around Paladin Energy. Any change in timing, capital intensity or operating assumptions in future updates will likely feed straight into how the recent profitability shift is interpreted.
What The Current Analyst Playbook Implies For Paladin Energy
Paladin Energy sits at an awkward but interesting point in its uranium story. The latest quarter puts real profit on the table, while the consensus models ask you to think several years ahead to a very different earnings profile.
Analysts looking out to 2029 are building their case on a set of punchy assumptions. They pencil in revenue growth of 20.4% a year for the next 3 years, margin expansion from 1.8% today to 25.6%, and earnings climbing from US$5.3 million to US$135.8 million with earnings per share of US$0.30. That would be a very large uplift in profit in absolute terms, even before you consider the most optimistic forecasts at US$311.3 million and the most cautious near US$67.9 million.
Drive the valuation work in those reports and you find it lines up around a shared reference point. By 2029, the consensus case links forecast revenue of US$530.8 million and earnings of US$135.8 million to a P/E multiple of 39.6x, using a discount rate in the 7.2% range and assuming the share count rises by a little over 3% per year in the near term. For you, the question is how comfortable you are with a future P/E that sits well above the 15.6x currently quoted for the wider AU oil and gas group, given the execution and permitting steps still ahead.
Paladin Energy's narrative projects US$530.8 million revenue and US$135.8 million earnings by 2029. This rests on revenue growing 20.4% per year and earnings rising by about US$130.5 million from US$5.3 million today.
Uncover how Paladin Energy's fair value indicates a 68% potential upside to its current price that could narrow quickly if sentiment toward Paladin Energy shifts.
Exploring Other Perspectives
One bullish twist on Paladin Energy focuses on Patterson Lake South turning into a low cost workhorse. The most optimistic analysts were already sketching out 2029 earnings near US$305.9 million on US$603.0 million revenue before this quarter’s US$92.38 million sales print. You can treat this quarter as fresh input and compare several competing stories.
Explore 8 other Paladin Energy fair value estimates, including one that suggests as much as 153% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Paladin Energy research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Paladin Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Paladin Energy's overall financial health at a glance.
Looking for more investment ideas beyond Paladin Energy?
If Paladin Energy has sharpened your interest in uranium and related infrastructure, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles.
- If you want potential mispricing with quality to back it up, scan our 5 high quality undervalued stocks to find companies that balance strong fundamentals with market pessimism.
- If resilience and capital protection matter most to you, filter for companies in the 6 resilient stocks with low risk scores and see which businesses score well on financial strength and risk metrics.
- If you are hunting for compelling stories the market may not be watching closely, check out the 14 high quality undiscovered gems to explore companies that pair solid balance sheets with under-the-radar profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com