


EN
Dynatrace (DT) Lifted Guidance And Buybacks, Is It Still Below Fair Value?
Dynatrace (DT) just paired a higher full year 2027 revenue outlook of US$2.33b to US$2.34b with fresh Q2 results and a new US$1b share repurchase authorization.
Despite the raised guidance and fresh partnership activity, the recent trading action has been harsh, with a 1 day share price return that declined 6.58% and a 7 day move down 28.34% as investors reassess near term expectations. Over a longer stretch, momentum looks mixed, with a year to date share price return of 3.19% but a 1 year total shareholder return that declined 5.12%. This hints that enthusiasm around Dynatrace has cooled compared with earlier years, even as buybacks and guidance updates reshape the story.
Scan how other observability and AI infrastructure players are reacting to similar guidance and buyback stories with our hand picked 53 AI infrastructure stocks for comparison.
The sharp pullback now leaves Dynatrace trading well below recent levels, even as buybacks and guidance remain in play. Does that reset already reflect the risks, or does it make more sense to remain patient for a deeper entry before crunching the valuation?
Most Popular Narrative: 32% Undervalued
Against Dynatrace's last close at $43.70, the most followed narrative pegs fair value nearer $64.41, so the recent slide has widened the gap that valuation work is trying to explain.
The move toward value based, consumption driven pricing continues with Dynatrace Platform Subscription contracts showing platform consumption growth well over 20% compared with ARR growth of about 16% to 17%, and a heavy DPS renewal mix expected in the second half of fiscal 2027, which can translate sustained consumption into higher net retention, ARR expansion, and operating leverage over time.
See why 54 investors see Dynatrace as 32% undervalued.
Result: Fair Value of $64.41 (UNDERVALUED)
Still, the bullish Dynatrace narrative could be tested if revenue trails software peers or if the Arize integration drags on margins without delivering meaningful ARR uplift.
Find out about the key risks to this Dynatrace narrative.
Another View: What Dynatrace's P/E Is Telling You
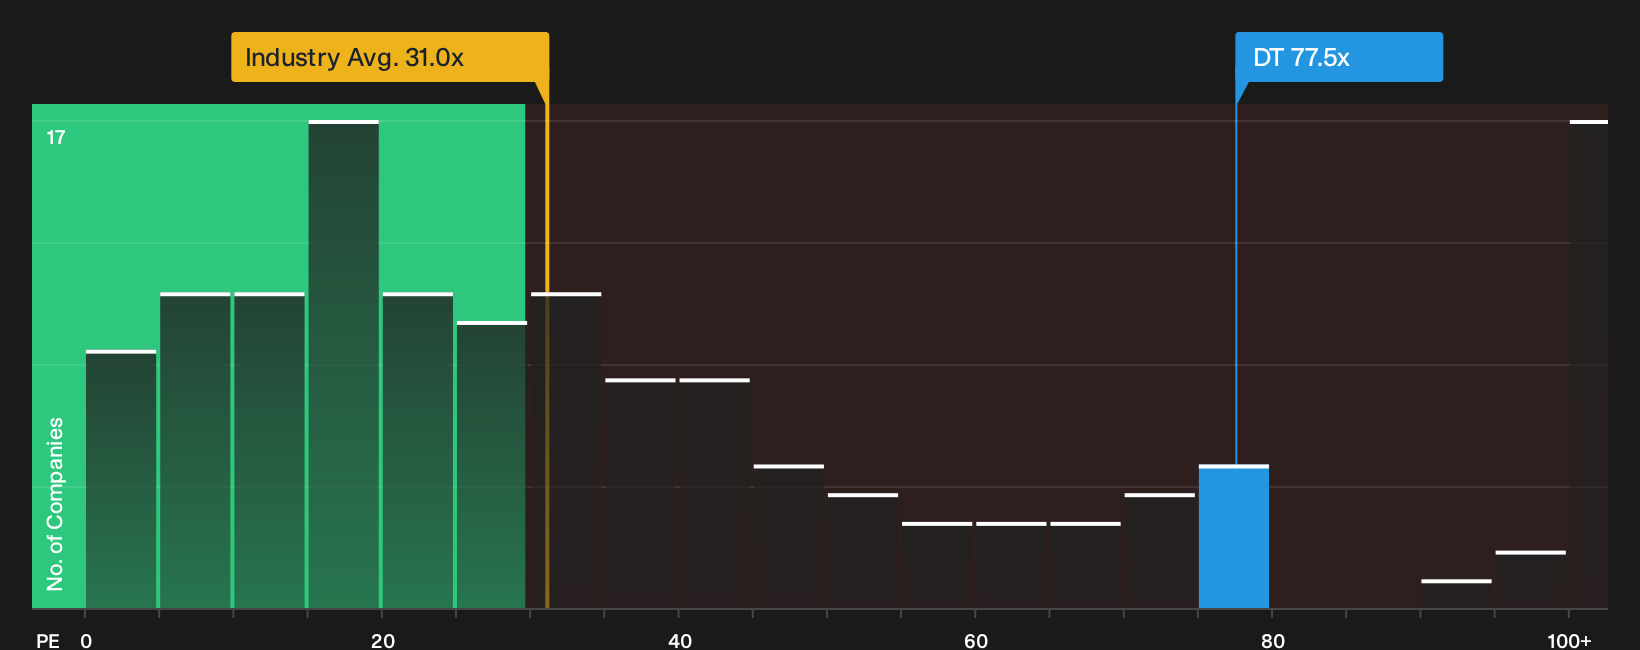
That SWS fair value of $71.97 based on future cash flows points to upside, yet the current P/E of 77.5x paints a different picture. The US Software industry sits nearer 30.2x, peers average 44.6x, and Dynatrace's fair ratio is 45.8x. Is the premium a cushion or a valuation air pocket?
To see how that gap between current P/E, peer levels, and the fair ratio could evolve as expectations reset, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Dynatrace can feel confusing, so move fast enough to review the numbers, stress test the story, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Dynatrace?
Do not stop at Dynatrace. Use this pullback as a prompt to widen your watchlist and pressure test fresh opportunities across quality, income, and overlooked potential.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) to filter for financial strength first.
- Hunt for potential value opportunities by reviewing the 42 high quality undervalued stocks filtered using cash flow quality and balance sheet support.
- Build a watchlist of potential income pillars with the 6 dividend fortresses which focuses on higher yields and payment durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com