


EN
Is Arista Networks (ANET) Undervalued On Record Q3 Results And Q4 Guidance?
Arista Networks (ANET) just put fresh numbers on the table, pairing record third quarter 2026 results with new fourth quarter revenue guidance of US$3.9b to US$4.0b that gives investors more concrete targets to track.
Despite the strong Q3 story, Arista Networks’ share price has come under pressure, with the stock down 10.8% over the last day, 13.6% over the past week and 26.1% over the past month. That pullback sits against a 19.1% year to date share price return and very large 3 and 5 year total shareholder returns. This suggests recent selling pressure reflects a reset in expectations and perceived risk rather than a break in the longer term performance record.
Scan beyond Arista Networks and identify other AI infrastructure players with notable recent moves using the hand-picked 53 AI infrastructure stocks.
The question is whether Arista Networks’ sharp pullback after strong Q3 numbers already builds in enough risk, or if patience for an even cheaper entry still makes more sense once you crunch the valuation.
Most Popular Narrative: 6% Undervalued
The narrative fair value of $169.91 sits above Arista Networks’ last close at $159.16. This puts the current slide against a slightly higher anchor and turns the spotlight onto what is driving that gap.
Arista reported Q3 revenue of $3.66 billion, up 58.5%, and forecast Q4 revenue between $3.9 billion and $4 billion. The headline is strong. One table in the 10-Q adds a detail worth holding next to it.
See why 1 investors see Arista Networks as 6% undervalued.
Result: Fair Value of $169.91 (UNDERVALUED)
Still, the Arista Networks narrative leans heavily on deferred revenue trends and large customer acceptances, so another deferred balance drop or weaker Q4 signings could quickly challenge it.
Find out about the key risks to this Arista Networks narrative.
Another View: Arista Networks Through The P/E Lens
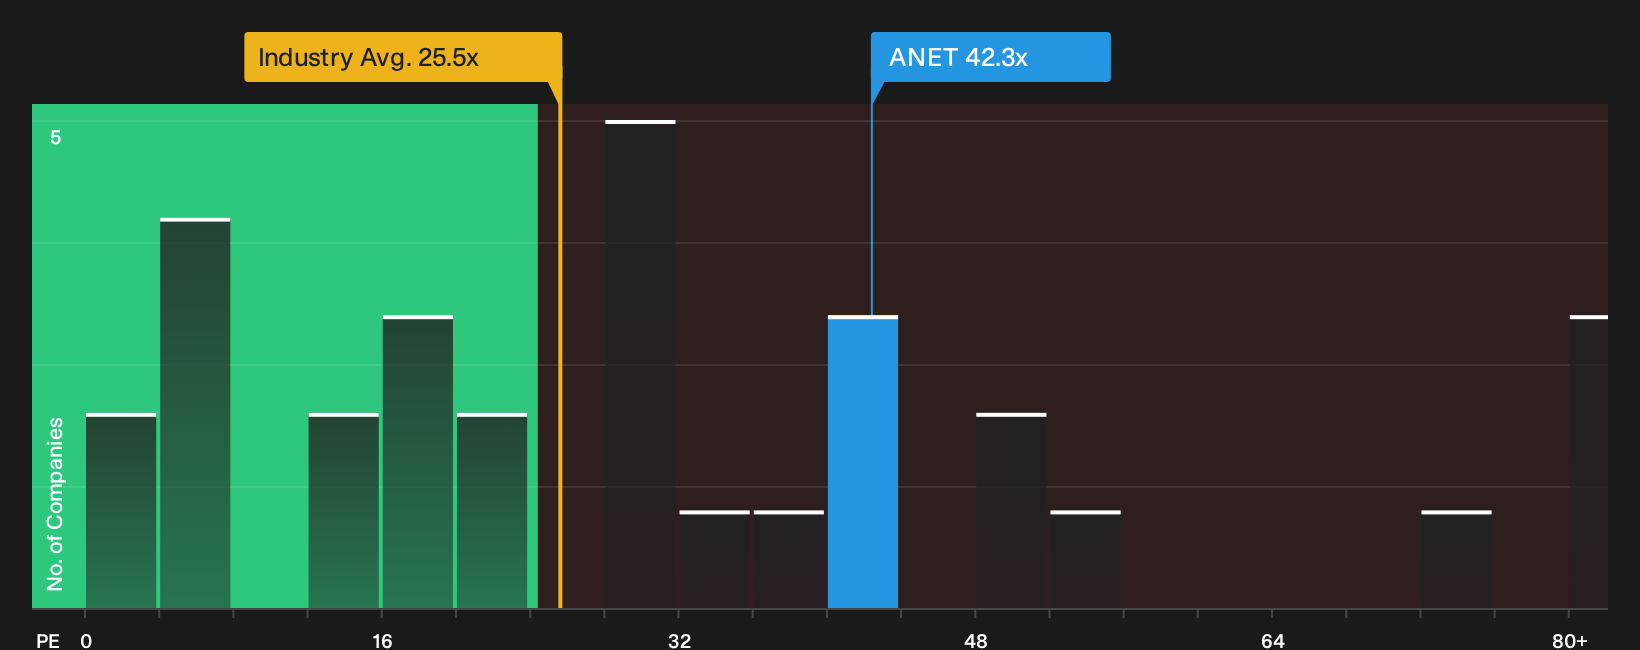
That narrative fair value of $169.91 leans on cash flows and contract visibility. The P/E picture tells a different story. At 42.3x earnings versus 25.5x for the US Communications group and a 35x fair ratio, Arista Networks carries a premium that raises valuation risk if expectations cool.
For investors comparing Arista Networks to peers, the question becomes whether its growth and profitability profile justifies paying above both the industry average and the fair ratio, or whether patience for a less demanding entry price feels more appropriate.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mixed tone around Arista Networks match your own read of the situation, or feel off once you look at the details yourself? Act quickly, stress test both the caution and the optimism, then weigh up the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Arista Networks?
Do not stop your research with Arista Networks when a few targeted stock lists could surface opportunities that better match your risk tolerance and income goals.
- Prioritise resilience and reduce guesswork by reviewing a 32 resilient stocks with low risk scores that filters for businesses with sturdier fundamentals and lower overall risk scores.
- Target financial strength first and let potential upside follow by scanning a list of solid balance sheet and fundamentals (24 results) that screens for robust balance sheets and consistent fundamentals.
- Hunt for potential mispricing and widen your opportunity set by working through a 42 high quality undervalued stocks that highlights companies with strong cash flows trading on compressed valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com