


EN
ZENKOKU HOSHOLtd (TSE:7164) Climbed, What Is Behind The Latest Attention?
ZENKOKU HOSHO Ltd (TSE:7164) has announced a new share buyback program, authorizing repurchases of up to 4,000,000 shares for ¥8,000 million through March 31, 2027, with the stated aim of improving capital efficiency and shareholder payouts.
The buyback news comes after a gradual uptick in ZENKOKU HOSHO Ltd's shares, with a 1-month share price return of 3.87% and a 1-day gain of 3.53%. The 3-year total shareholder return of 48.58% suggests stronger long term momentum compared with the recent year to date performance.
Explore additional potential buyback and capital return ideas alongside ZENKOKU HOSHO Ltd by reviewing our curated list of 19 high quality undervalued stocks.
ZENKOKU HOSHO’s buyback and recent uptick in the share price put you at a fork in the road. Is today’s valuation already fair, or is patience the better entry point?
Price-to-Earnings of 12.6x: Is it justified?
On simple valuation maths, ZENKOKU HOSHO Ltd trades on a P/E of 12.6x, which screens as slightly expensive compared with both its own fair ratio and peer group references.
The P/E ratio links the current share price to annual earnings per share, so it shows how much investors are paying for each unit of profit. For a credit guarantee business like ZENKOKU HOSHO, this matters because profits tie closely to lending cycles, credit quality, and funding structure, so the multiple reflects how confident the market is in those earnings streams.
Here, the current P/E of 12.6x is described as expensive versus an estimated fair P/E of 12.5x. This is a marginal gap but still flagged as above the level the market could move towards. At the same time, the stock is called good value compared with the broader JP Diversified Financial industry average P/E of 13.7x. This suggests investors are not paying a premium relative to that wider peer set even though earnings growth forecasts are more modest than the market and sector.
Explore the SWS fair ratio for ZENKOKU HOSHOLtd.
Result: Price-to-Earnings of 12.6x (ABOUT RIGHT)
Still, the credit guarantee focus leaves ZENKOKU HOSHO exposed if lending volumes soften or if credit quality weakens and guarantees are called more heavily.
Find out about the key risks to this ZENKOKU HOSHOLtd narrative.
Another View: SWS DCF Says The Market Is Harsh
The P/E picture around ZENKOKU HOSHO Ltd looks roughly in line with peers. However, the SWS DCF model presents a very different perspective. At ¥3,140 the shares are described as trading 48.1% below an estimated future cash flow value of ¥6,055.7, which highlights a sizeable valuation gap that investors need to interpret for themselves.
Look into how the SWS DCF model arrives at its fair value.
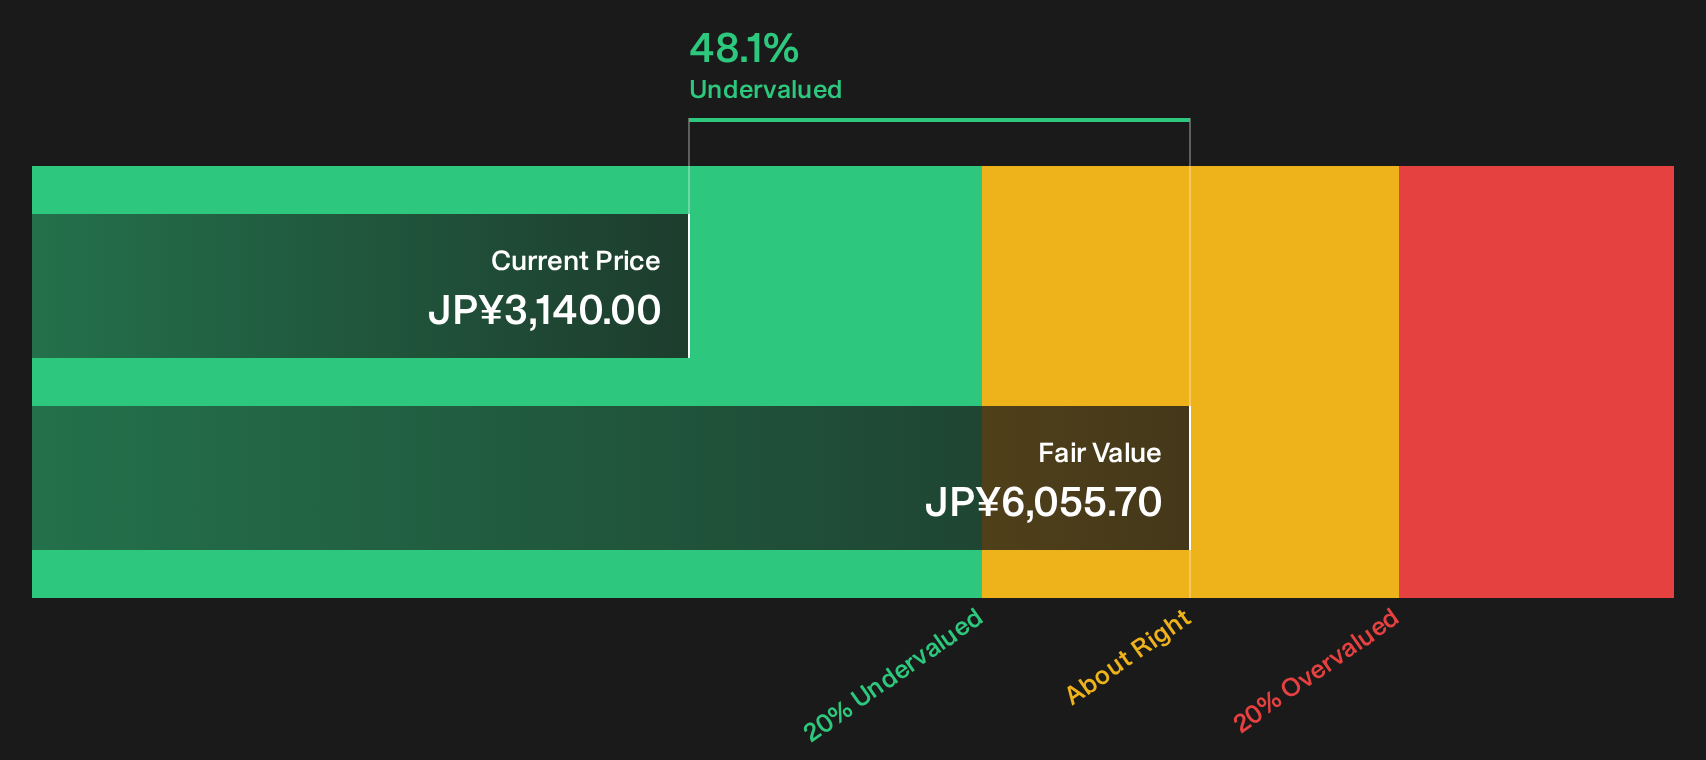
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ZENKOKU HOSHOLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ZENKOKU HOSHO Ltd’s valuation and buyback can feel confusing, so move quickly to review the underlying data and form your own take on both the upside and the weak spots. For a concise overview of what the market currently sees as the main positives and the key concerns, start with these 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond ZENKOKU HOSHO?
If ZENKOKU HOSHO Ltd has sharpened your focus on valuation and capital returns, do not stop here. Broader idea generation often reveals opportunities that may be better aligned with your goals.
- Target resilient compounding by reviewing companies in our 28 dividend fortresses that focus on higher yields with an emphasis on durability.
- Hunt for potential mispricing by exploring the 74 high quality undiscovered gems that highlight businesses with solid fundamentals that many investors may still be overlooking.
- Dial down potential downside by scanning the 22 resilient stocks with low risk scores and focusing on businesses that score better on overall risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com