


EN
Buyback Plan Could Be A Big Moment For Healthcare Realty Trust Shares
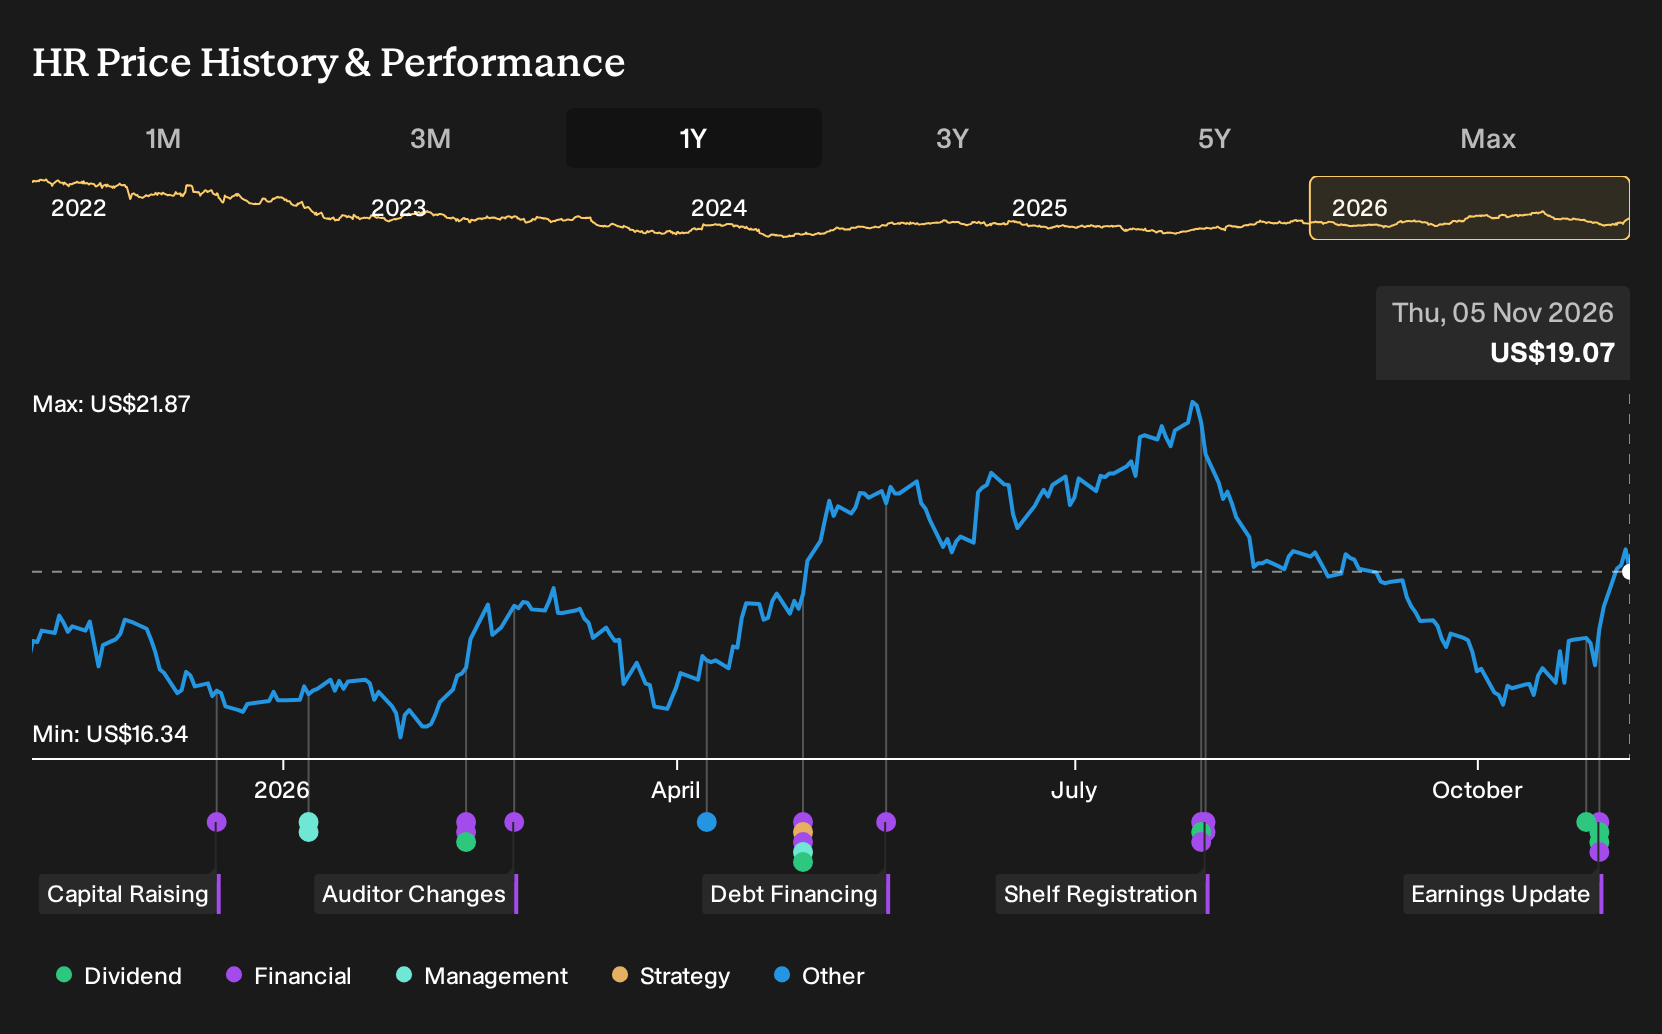
- Healthcare Realty Trust reported third quarter 2026 revenue of US$286.64 million and a net loss of US$15.76 million, while affirming a US$0.24 per share dividend and outlining a new share repurchase program of up to US$500 million alongside completed prior buybacks.
- The combination of a smaller loss, a steady dividend, and a new repurchase authorization reflects management’s focus on capital returns and operating discipline despite softer sales figures.
- Now the focus turns to how Healthcare Realty Trust's investment narrative aligns with these earnings results and the sizeable new buyback authorization.
Healthcare Realty Trust Investment Narrative Recap
To own Healthcare Realty Trust, an investor needs to be comfortable with a real estate platform that is still reporting losses but is leaning on stable outpatient medical demand and its HR 2.0 model to support occupancy and rent. The latest quarter showed revenue of US$286.64 million and a net loss of US$15.76 million, which means the story still hinges on execution, not clean profitability.
The key short term catalyst remains the firm’s ability to convert its redevelopment, joint venture pipeline, and leasing spreads into higher NOI and FFO while interest costs stay manageable. The main risk sits around capital intensity and financing, because elevated tenant improvements and future refinancing needs could keep earnings under pressure even if operational metrics hold up.
The most relevant piece of news for that thesis is the fresh US$500 million share repurchase authorization that runs to October 25, 2027. Management has already completed US$149.84 million of buybacks under the prior plan, retiring 2.44% of shares, which reflects a willingness to return capital even while reporting losses.
For you as a shareholder, the new Healthcare Realty Trust program matters because it interacts directly with the operating backdrop. If the HR 2.0 operating model, redevelopment yields, and joint ventures deliver the cash flow analysts expect, buybacks can reduce the share count and increase any future improvement in per share metrics, while misexecution or higher interest expense would make that capital return choice more demanding on the balance sheet.
Healthcare Realty Trust's narrative projects US$1.2b revenue and US$62.7 million earnings by 2029. This assumes 1.8% yearly revenue growth and an earnings increase of about US$152 million from current earnings of a US$89.6 million loss.
Uncover why Healthcare Realty Trust's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit between about US$21.08 and US$32.48 per share, which already shows how far retail opinions on Healthcare Realty Trust can stretch. When you also factor in the affirmed US$0.24 dividend, the new US$500m buyback plan, and ongoing losses, it becomes clear why views can diverge sharply. If you want a fuller picture, compare these community forecasts with your own assessment of refinancing risk, redevelopment outcomes, and sector demand before deciding where you sit in that spectrum.
Explore another Healthcare Realty Trust fair value estimate, including one that suggests it could be worth just $21.08.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Healthcare Realty Trust research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Healthcare Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Healthcare Realty Trust's overall financial health at a glance.
Looking For More Ideas Beyond Healthcare Realty Trust?
If you want to stress test your view on Healthcare Realty Trust and build a broader watchlist around it, cast a wider net using the Simply Wall St Screener. Comparing this REIT with other income, quality, and lower risk candidates can sharpen your decision making and help you spot patterns that do not show up when you only focus on a single ticker.
- If you want potential upside with a margin of safety, scan for mispriced opportunities using our 42 high quality undervalued stocks that pair strong fundamentals with appealing valuations.
- If capital preservation and steadier profiles matter most to you right now, line up candidates through the 32 resilient stocks with low risk scores and see which businesses score well on resilience.
- If you prefer to focus on balance sheets that can support reinvestment and shareholder returns, filter for financially robust companies with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com