


EN
Cogent Biosciences (COGT) Could Be 89% Undervalued On Wider Third Quarter Losses
Cogent Biosciences (COGT) is back in focus after reporting third quarter 2026 results, with net loss widening to US$111.43 million and nine month loss reaching US$305.18 million, both above the prior year figures.
The latest third quarter loss arrived as the share price pulled back, with Cogent Biosciences falling 6.07% on the day and 30.22% over 90 days, even though the 1 year total shareholder return is up 99.60% and the 3 year total shareholder return is more than 3x. This points to strong long term gains but fading recent momentum linked to higher perceived risk.
Scan 21 high quality undiscovered gems, which, like Cogent Biosciences, sit at the sharp end of high-risk clinical development and can move quickly when sentiment around trial results or cash burn shifts.
After a 99.60% one-year gain followed by a 30.22% slide in 90 days, Cogent Biosciences now faces a sharper question: Is the real upside still ahead, or did most of it already happen on the way up?
Preferred Price-to-Book of 11x: Is it justified?
Valuation on Cogent Biosciences is currently framed by a rich price-to-book multiple, with the stock trading around $29.58 and carrying a P/B ratio of 11x. That figure already implies a lot of optimism compared with both peers and the broader US Biotechs group.
The price-to-book measure compares the market value of the equity to the accounting value of net assets on the balance sheet. For early-stage drug developers with little or no revenue, investors often lean on P/B because earnings based metrics are not yet meaningful and most of the value rests on future trial outcomes rather than current cash flows.
In Cogent Biosciences' case, that 11x P/B is described as expensive relative to the US Biotechs industry average of 1.7x and is also higher than the peer group average of 10.8x. The market is therefore assigning a premium valuation to the pipeline and management's execution, even though the business is still loss making and reported net income of a $377.18m loss with less than $1m in revenue.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-book of 11x (OVERVALUED).
Still, the story around Cogent Biosciences can change quickly if trial timelines slip, or if ongoing net losses pressure the balance sheet and future funding options.
Find out about the key risks to this Cogent Biosciences narrative.
Another View: SWS DCF Says Cogent Biosciences Is Deeply Undervalued
The P/B multiple paints Cogent Biosciences as expensive, yet the SWS DCF model points in the opposite direction. At a share price of $29.58 versus an estimated future cash flow value of $268.29, the stock is described as trading about 89% below that modelled value. This flags a very different kind of risk for investors to weigh. If the market is this far away from a cash flow based estimate, is the gap signalling opportunity or over optimism in the assumptions behind the model?
Look into how the SWS DCF model arrives at its fair value.
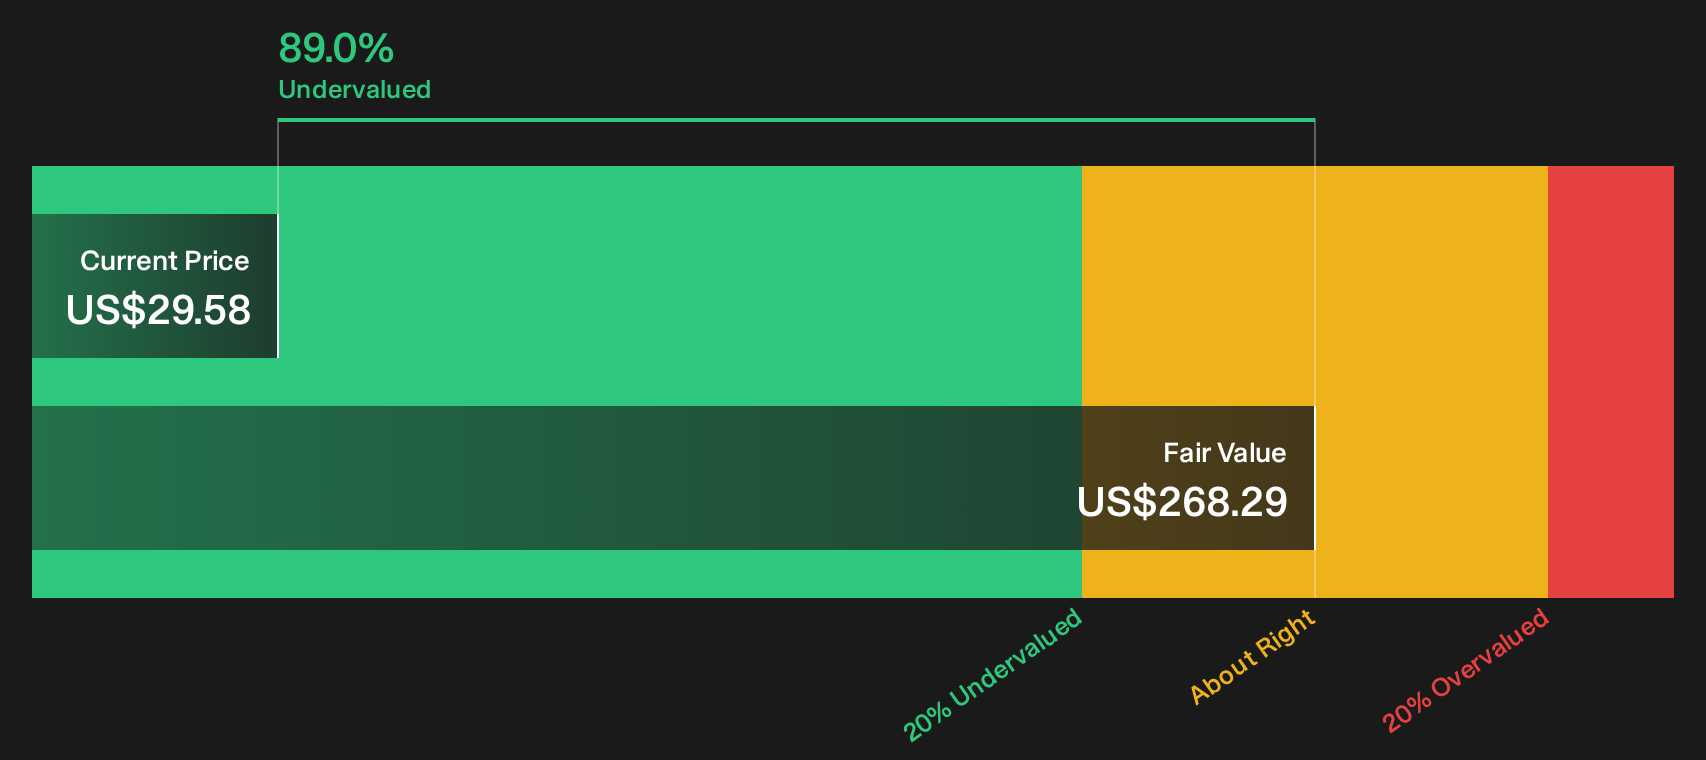
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cogent Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Cogent Biosciences can feel unsettling for any holder, so move quickly, review the underlying data for yourself, and weigh both the potential upside and the downside captured in these 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Cogent Biosciences?
If Cogent Biosciences has your attention, do not stop there. Broaden your watchlist with other targeted ideas before the next round of market moves leaves you reacting late.
- Target resilient balance sheets and steady fundamentals with a focused list of solid balance sheet and fundamentals (24 results) that can help you stress test your portfolio strength.
- Hunt for mispriced opportunities by scanning a curated 42 high quality undervalued stocks that filters for quality first so you are not just chasing cheap tickers.
- Prioritise sleep-at-night holdings through a hand picked 32 resilient stocks with low risk scores that aims to keep shocks and nasty surprises to a minimum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com