


EN
Innoviva (INVA) Stock Could Be Undervalued On Third Quarter Results
Innoviva has given shareholders a mixed ride, with the stock retreating over the past year after a strong multi year gain, which raises a clear question for you as an investor. Is the current US$19.24 share price adequately grounded in the company’s earnings power, or has recent enthusiasm run ahead of what the income statement supports?
- The stock has risen 42.8% over the past 3 years, putting real weight on whether that climb is still well supported by Innoviva's profit generation.
- Recent progress in its specialty therapeutics platform, including new products and broader clinical backing, can shape expectations for future earnings and the cash those profits may generate.
- The analysts covering Innoviva have run their own numbers. See what analysts think Innoviva's shares could be worth.
The issue now is whether Innoviva's current market value is appropriately aligned with what its earnings suggest the business is worth.
To see how Innoviva compares in this earnings story with other opportunities, place it alongside companies in the 42 high quality undervalued stocks
Does Innoviva Look Undervalued on Earnings?
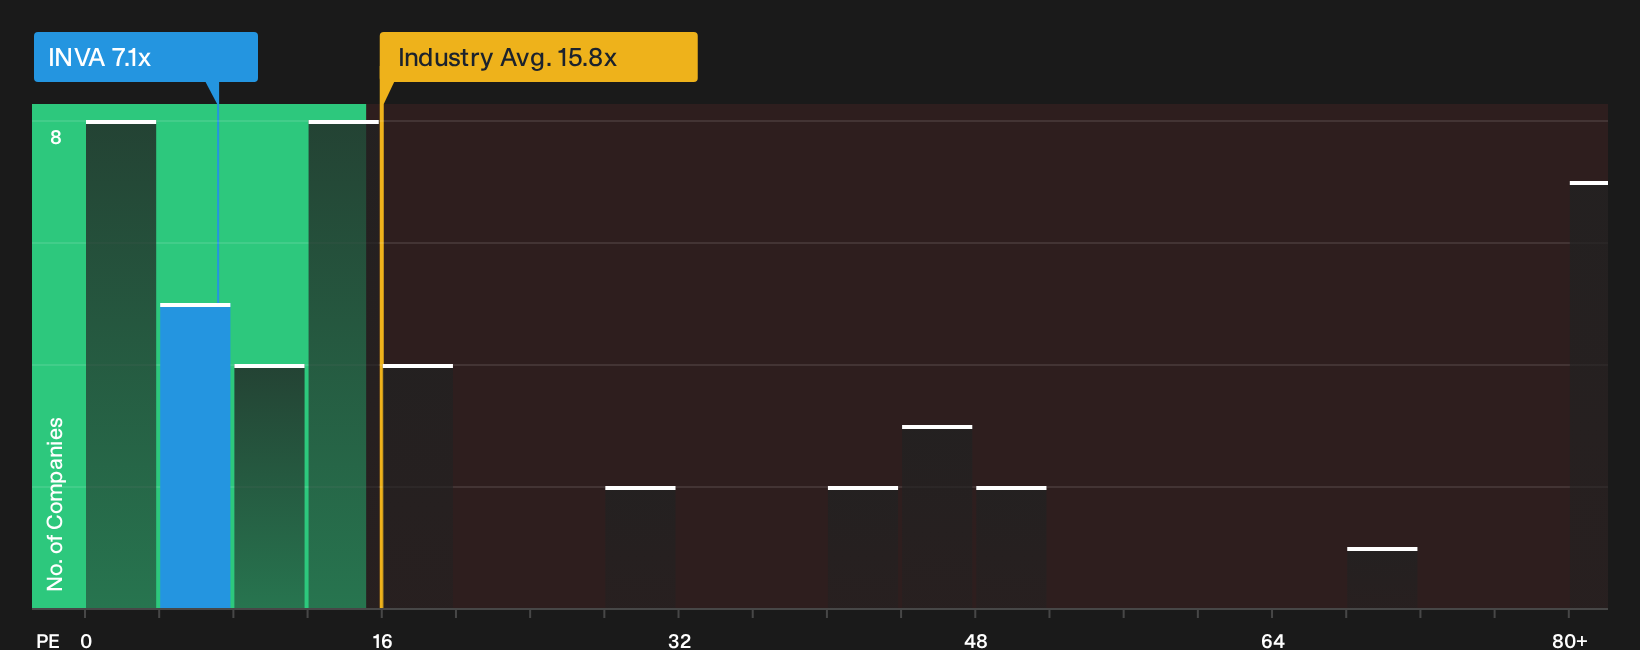
The P/E ratio is a useful lens for Innoviva because earnings and cash generation sit at the center of the story for a royalties plus specialty therapeutics business. At the current price, Innoviva trades on a P/E of 7.1x, compared with roughly 15.8x for the wider Pharmaceuticals industry and about 35.8x for the peer group in this framework. Relative to the tailored fair multiple implied by the valuation model, the stock changes hands at a lower P/E than you would expect given its mix of margins, growth profile, size and risk.
Because the third quarter 2026 update highlighted continued progress in the Innoviva Specialty Therapeutics platform and named concrete products like NUZOLVENCE and XACDURO, the subdued 7.1x earnings multiple still prices Innoviva at a discount to both sector norms and these modelled expectations. That gap suggests the market is assigning a relatively cautious value to the existing earnings stream, leaving you to decide whether the current business performance justifies a higher or lower bar for what the stock should be worth. Explore the numbers behind Innoviva's P/E valuation.
The Innoviva Narrative: What Would Justify Today's Price?
Innoviva's valuation story opens the door to Simply Wall St Narratives, which set out the specific paths on growth, margins and earnings that would need to play out for the stock to be worth meaningfully more or less than today, and sit within the Community page for this business. Where a single ratio or valuation model gives you one number, these scenarios describe the future that number relies on so you can watch how the real world lines up over time.
Bulls and bears looking at Innoviva are reading the same data yet reaching very different conclusions on what the current price reflects.
Bull case: 45% undervalued
"The current valuation implies that the market is assigning limited value to Innoviva’s expected approximately $1b in future respiratory royalties, its growing IST revenue base, and its healthcare investments…"
Discover why this Narrative puts Innoviva at 45% undervalued.
Bear case: 7% overvalued
"The current pricing of Innoviva stock implies that the market is already assigning a rich value to the roughly $1 billion expected respiratory royalty stream and is crediting a high success and monetization rate for Innoviva Specialty Therapeutics, Armata, Nortiva Bio, and other healthcare assets…"
Explore why this Narrative puts Innoviva at 7% overvalued.
Before you act on Innoviva's valuation, there is one more angle to check
Price tags only tell part of the story, and for Innoviva the research screen has flagged specific caution signals that deserve a look alongside the earnings math. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com