


EN
Solventum (SOLV) Stock May Look Reasonable Following Raised Guidance
Solventum has delivered a strong run in the past year, so the key issue now is whether the current share price lines up with what its earnings can reasonably support. With the stock moving on both performance and headlines, the question for you is how much of that story is already embedded in today's valuation.
- Solventum has returned 31.5% over the past 12 months, which puts more pressure on its earnings to justify where the stock now trades.
- Recent results showed lower sales alongside stronger adjusted earnings per share and higher full year earnings expectations, which can influence how investors weigh the durability and quality of Solventum's profit base.
- Your read on Solventum is one view; the desks covering it have another. See what analysts think Solventum's shares could be worth.
The stock's next move may depend on whether Solventum's current earnings base and outlook are strong enough to support the valuation implied by today's share price.
If you want to test the same earnings-driven valuation question you are asking of Solventum across a wider watchlist, take a look at 42 high quality undervalued stocks.
Is Solventum Still Cheap on Earnings?
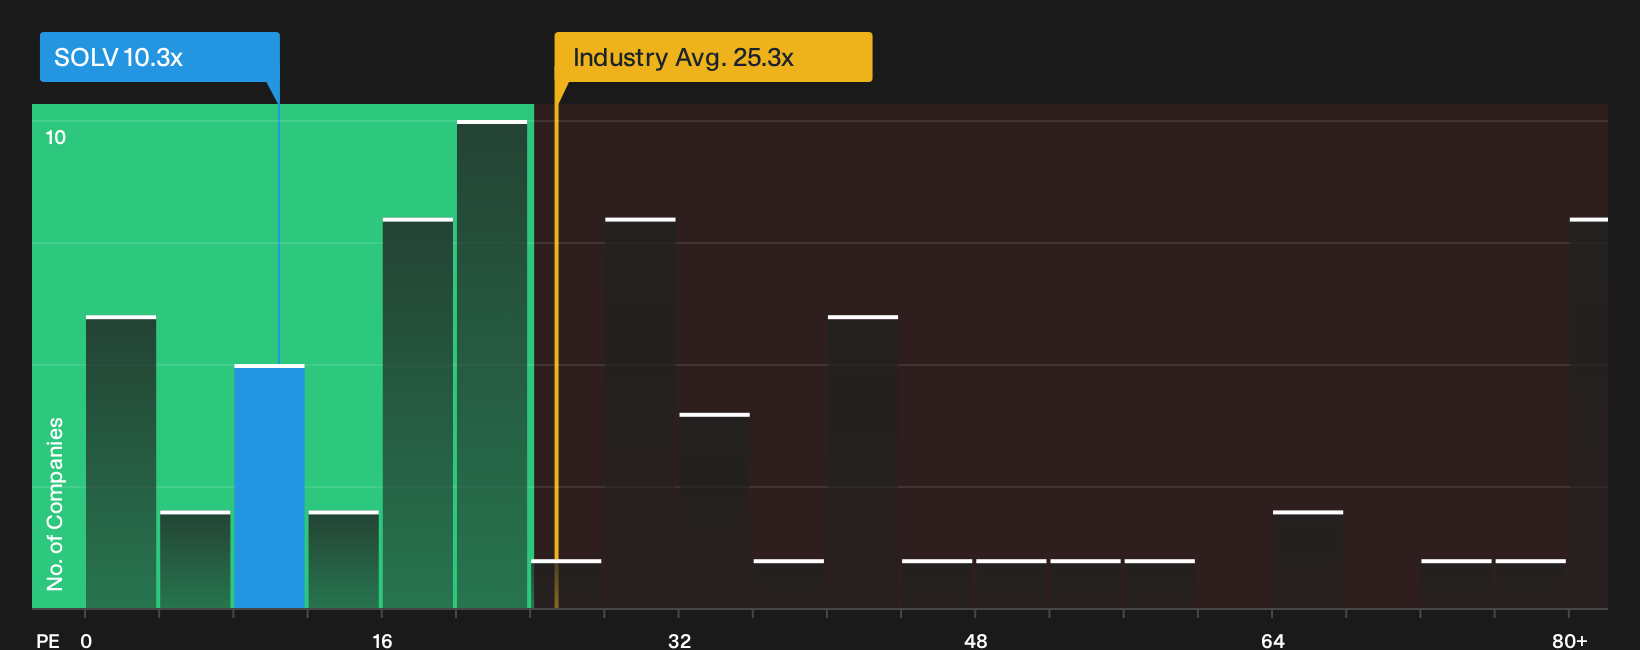
The P/E ratio is a useful anchor for Solventum because recent earnings are a key focus after the spin-off. On this measure, the stock trades at about 10.3x earnings, compared with roughly 25.3x for the wider Medical Equipment group and around 31.6x for direct peers. That is a wide gap for a business that shares many of the same end markets as its sector.
The valuation model that blends Solventum's growth profile, margins, scale and risk points to a higher P/E than where the shares change hands today, which implies the current multiple sits below what that framework would suggest for the business. Because adjusted EPS guidance for 2026 was raised after the Q3 beat, the low P/E does not solely reflect weaker expectations in the near term and instead leaves you weighing whether the market is applying a heavier discount than the company's earnings track record and outlook might justify. Explore the numbers behind Solventum's P/E valuation.
The Solventum Narrative: What Would Justify Today's Price?
Narratives for Solventum pick up where the P/E question leaves off by spelling out what sort of future growth, profitability and earnings profile would need to play out for the stock to be worth materially more or materially less than today. They sit on Simply Wall St's Community page, and each one treats Solventum's fair value as a thesis about how the business might develop that you can revisit over time, rather than a one-off snapshot.
Bullish and bearish community views on Solventum are both clear, yet they point in opposite directions on what the current price implies.
Bull case: 8% undervalued
"Execution of the five growth driver strategy around underpenetrated, clinically differentiated products such as Tegaderm CHG and V.A.C. therapy, with management pointing to multibillion dollar opportunities and current usage in less than 20% of indicated cases in some areas…"
Discover why this Narrative puts Solventum at 8% undervalued.
Bear case: 22% overvalued
"Management frames autonomous coding in revenue cycle management as a major opportunity. Fully pursuing it, however, requires significant, concentrated AI investment that may strain Solventum’s capital allocation inside a medtech focused portfolio and limit future free cash flow if spending rises faster than the revenue contribution from new software capabilities…"
Explore why this Narrative puts Solventum at 22% overvalued.
One more Solventum check before you decide what the price really tells you
Price ratios and community narratives only go so far, because separate research checks on Solventum have raised specific concerns that sit outside the earnings debate and deserve their own look. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com