


EN
When Will Corline Biomedical AB (publ) (STO:CLBIO) Breakeven?
We feel now is a pretty good time to analyse Corline Biomedical AB (publ)'s (STO:CLBIO) business as it appears the company may be on the cusp of a considerable accomplishment. Corline Biomedical AB (publ) develops, manufactures, and markets heparin based solutions to enhance kidney transplantation, cell therapies, and regenerative medicine applications in Sweden. The kr336m market-cap company posted a loss in its most recent financial year of kr15m and a latest trailing-twelve-month loss of kr12m shrinking the gap between loss and breakeven. Many investors are wondering about the rate at which Corline Biomedical will turn a profit, with the big question being “when will the company breakeven?” We've put together a brief outline of industry analyst expectations for the company, its year of breakeven and its implied growth rate.
Corline Biomedical is bordering on breakeven, according to some Swedish Pharmaceuticals analysts. They expect the company to post a final loss in 2026, before turning a profit of kr34m in 2027. The company is therefore projected to breakeven just over a year from now. How fast will the company have to grow each year in order to reach the breakeven point by 2027? Working backwards from analyst estimates, it turns out that they expect the company to grow 200% year-on-year, on average, which signals high confidence from analysts. If this rate turns out to be too aggressive, the company may become profitable much later than analysts predict.
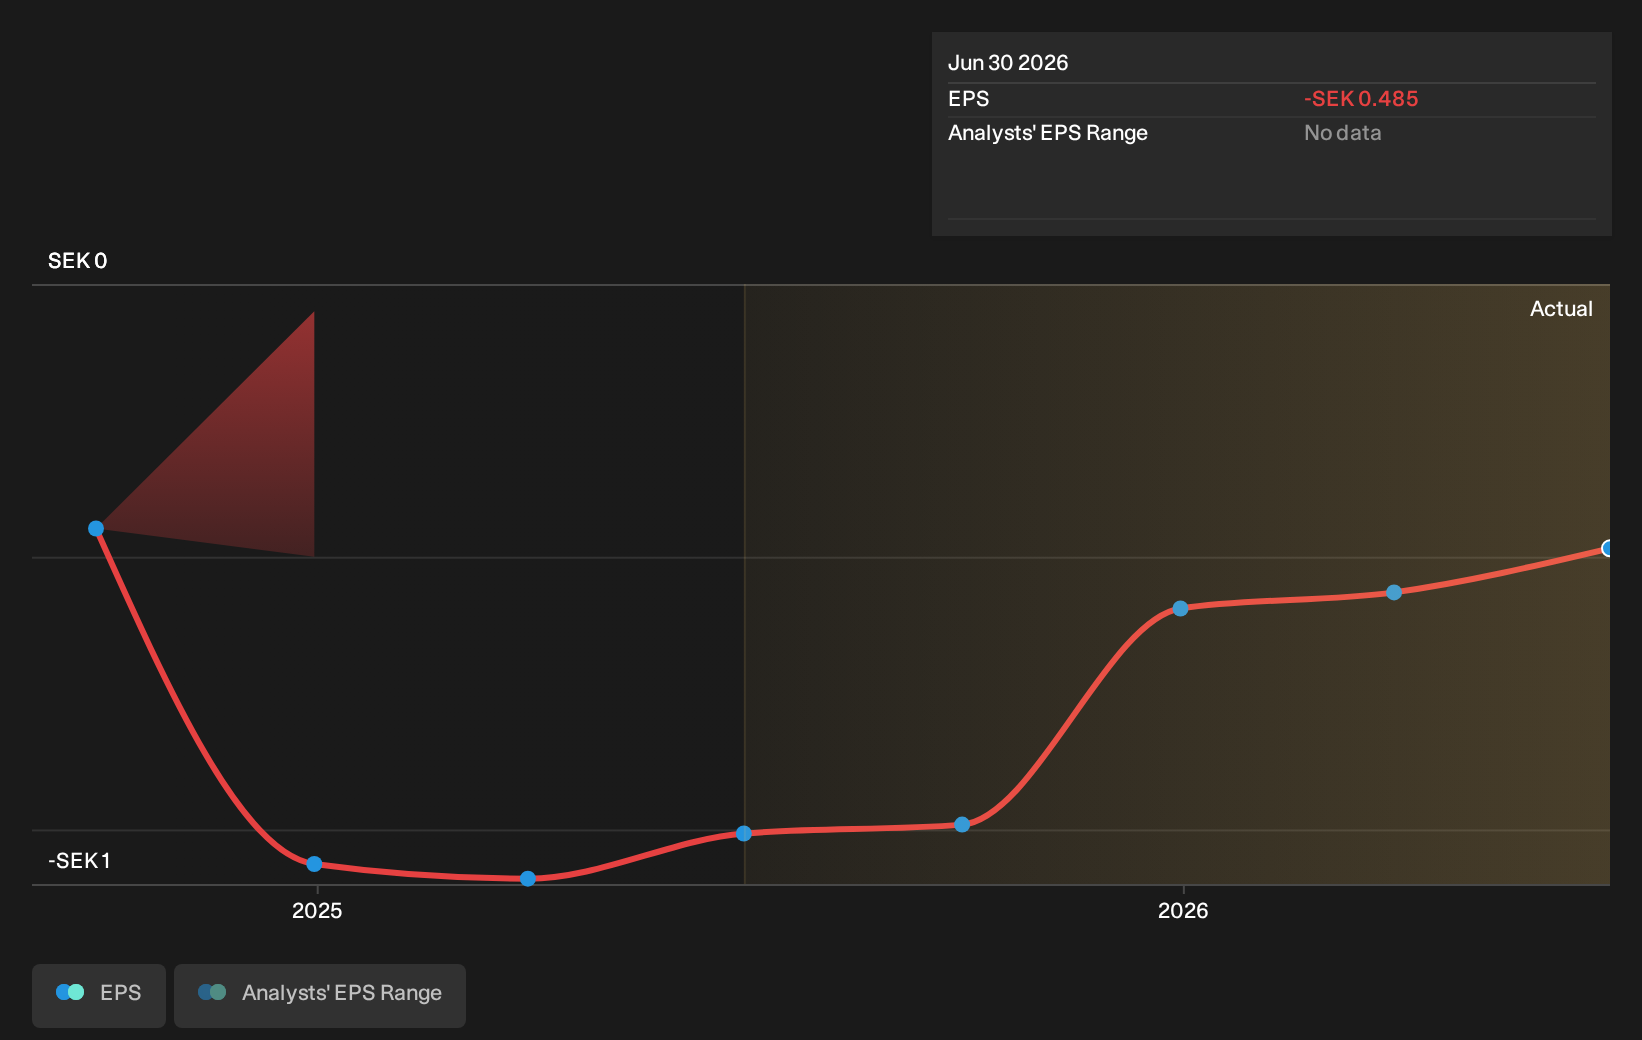
Given this is a high-level overview, we won’t go into details of Corline Biomedical's upcoming projects, though, keep in mind that typically a pharma company has lumpy cash flows which are contingent on the drug and stage of product development the business is in. This means, large upcoming growth rates are not abnormal as the company is beginning to reap the benefits of earlier investments.
See our latest analysis for Corline Biomedical
One thing we’d like to point out is that Corline Biomedical has no debt on its balance sheet, which is quite unusual for a cash-burning pharma, which usually has a high level of debt relative to its equity. The company currently operates purely off its shareholder funding and has no debt obligation, reducing concerns around repayments and making it a less risky investment.
Next Steps:
This article is not intended to be a comprehensive analysis on Corline Biomedical, so if you are interested in understanding the company at a deeper level, take a look at Corline Biomedical's company page on Simply Wall St. We've also put together a list of essential factors you should further research:
- Historical Track Record: What has Corline Biomedical's performance been like over the past? Go into more detail in the past track record analysis and take a look at the free visual representations of our analysis for more clarity.
- Management Team: An experienced management team on the helm increases our confidence in the business – take a look at who sits on Corline Biomedical's board and the CEO’s background.
- Other High-Performing Stocks: Are there other stocks that provide better prospects with proven track records? Explore our free list of these great stocks here.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.