


EN
Is Patrick Industries (PATK) Undervalued After Weaker Quarterly Earnings?
Patrick Industries (PATK) has investors’ attention after its latest quarterly update, where third quarter sales remained close to last year’s level, while net income and earnings per share moved lower.
That profit squeeze has been playing out in the share price. Despite a 24.71% 30 day share price return and a 10.55% gain over the past week that pushed Patrick Industries to about $83, the stock is still down 24.74% on a year to date share price basis, while the 1 year total shareholder return has slipped 18.69% even after strong 3 and 5 year total returns above 70%, which signals that recent momentum is rebuilding after a weaker stretch driven by concern over earnings pressure.
Compare Patrick Industries' recent profit pressure with a curated group of companies that pair solid cash generation and balance sheets in our 42 high quality undervalued stocks.
After that sharp rebound in Patrick Industries, the real question now is whether the recent swing already priced in most of the opportunity, or if the valuation still points to meaningful upside ahead.
Most Popular Narrative: 18% Undervalued
Against Patrick Industries' last close at $83.11, the most followed narrative pegs fair value closer to $100.82, which frames the recent rebound as only a partial catch up rather than a full rerating.
The planned merger with LCI Industries, targeting $150 million in annual run rate cost synergies on a pro forma base of about $8.1b in revenue and roughly $1b of adjusted EBITDA, provides a potential path to higher operating efficiency and earnings power as procurement, supply chain and overhead costs are combined.
See why 2 investors see Patrick Industries as 18% undervalued.
Result: Fair Value of $100.82 (UNDERVALUED)
Still, soft RV demand and elevated working capital that ties up cash could easily pressure the Patrick Industries narrative if those trends persist or worsen.
Find out about the key risks to this Patrick Industries narrative.
Another View: Patrick Industries Through A P/E Lens
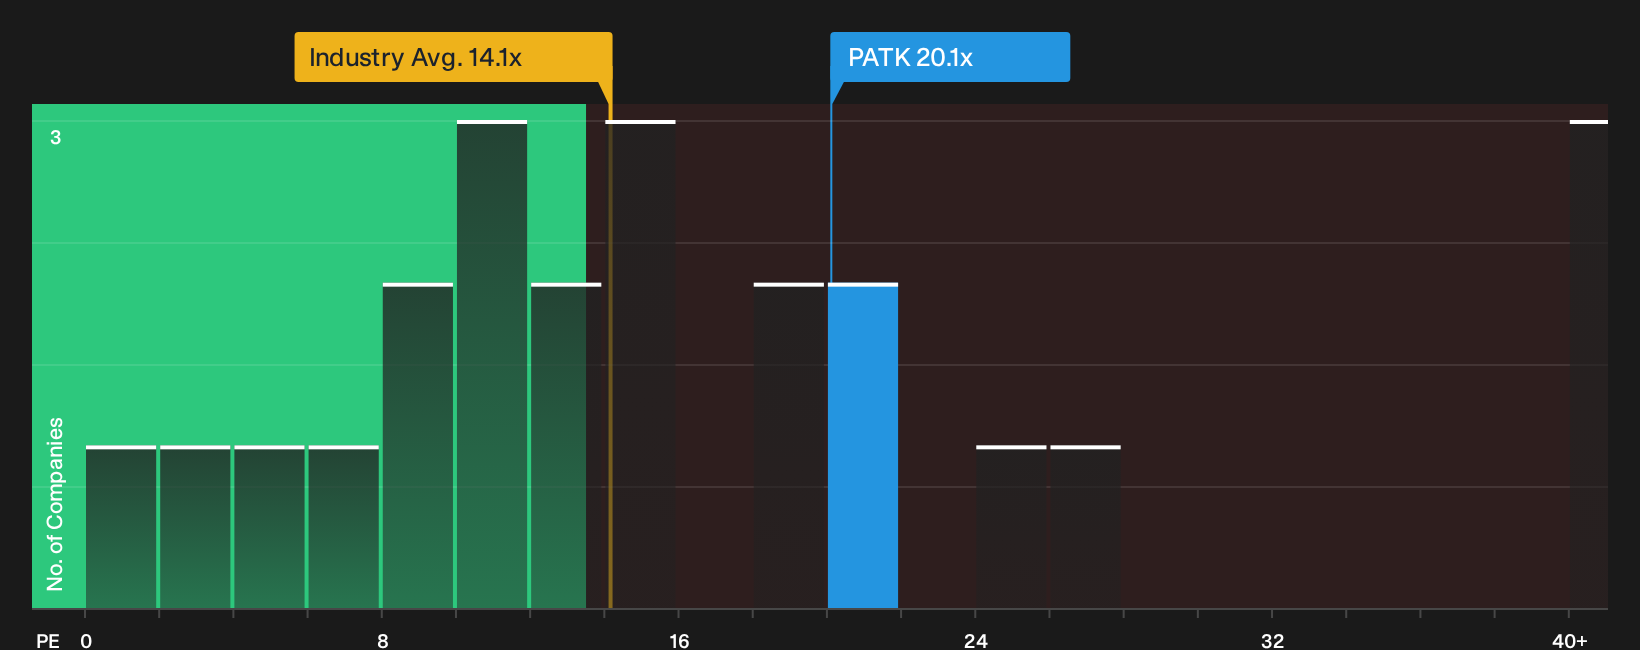
The 18% undervalued fair value narrative looks very different when Patrick Industries is evaluated through its P/E ratio. The stock trades on 20.1x earnings, compared with 14.1x for the US Auto Components industry, 12.7x for peers, and a fair ratio of 15.1x.
This gap suggests that investors are already paying a clear premium for Patrick Industries. If the share price moved closer to the 15.1x fair ratio or industry averages, that would imply less scope for upside and more risk of multiple compression if expectations were to slip.
To see how that premium ties back to the underlying numbers, it is worth going through the valuation breakdown in more detail with the See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how Patrick Industries compares with its sector on earnings, review the latest
Next Steps
Mixed signals around Patrick Industries often create strong opinions. Move quickly, review the numbers yourself, then weigh up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Patrick Industries?
Do not stop at Patrick Industries. Fresh opportunities sit across the market, and a quick screen could surface ideas that fit your goals far better.
- Target income first and filter for companies that prioritise reliable payouts with the 6 dividend fortresses.
- Hunt for under-covered potential by checking the 21 high quality undiscovered gems that pair quality fundamentals with less attention from the crowd.
- Prioritise capital preservation and cut down on unpleasant surprises by scanning a 32 resilient stocks with low risk scores tailored to resilient balance sheets and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com