


EN
LeMaitre Vascular Stock In Focus After Updated Guidance And Dividend
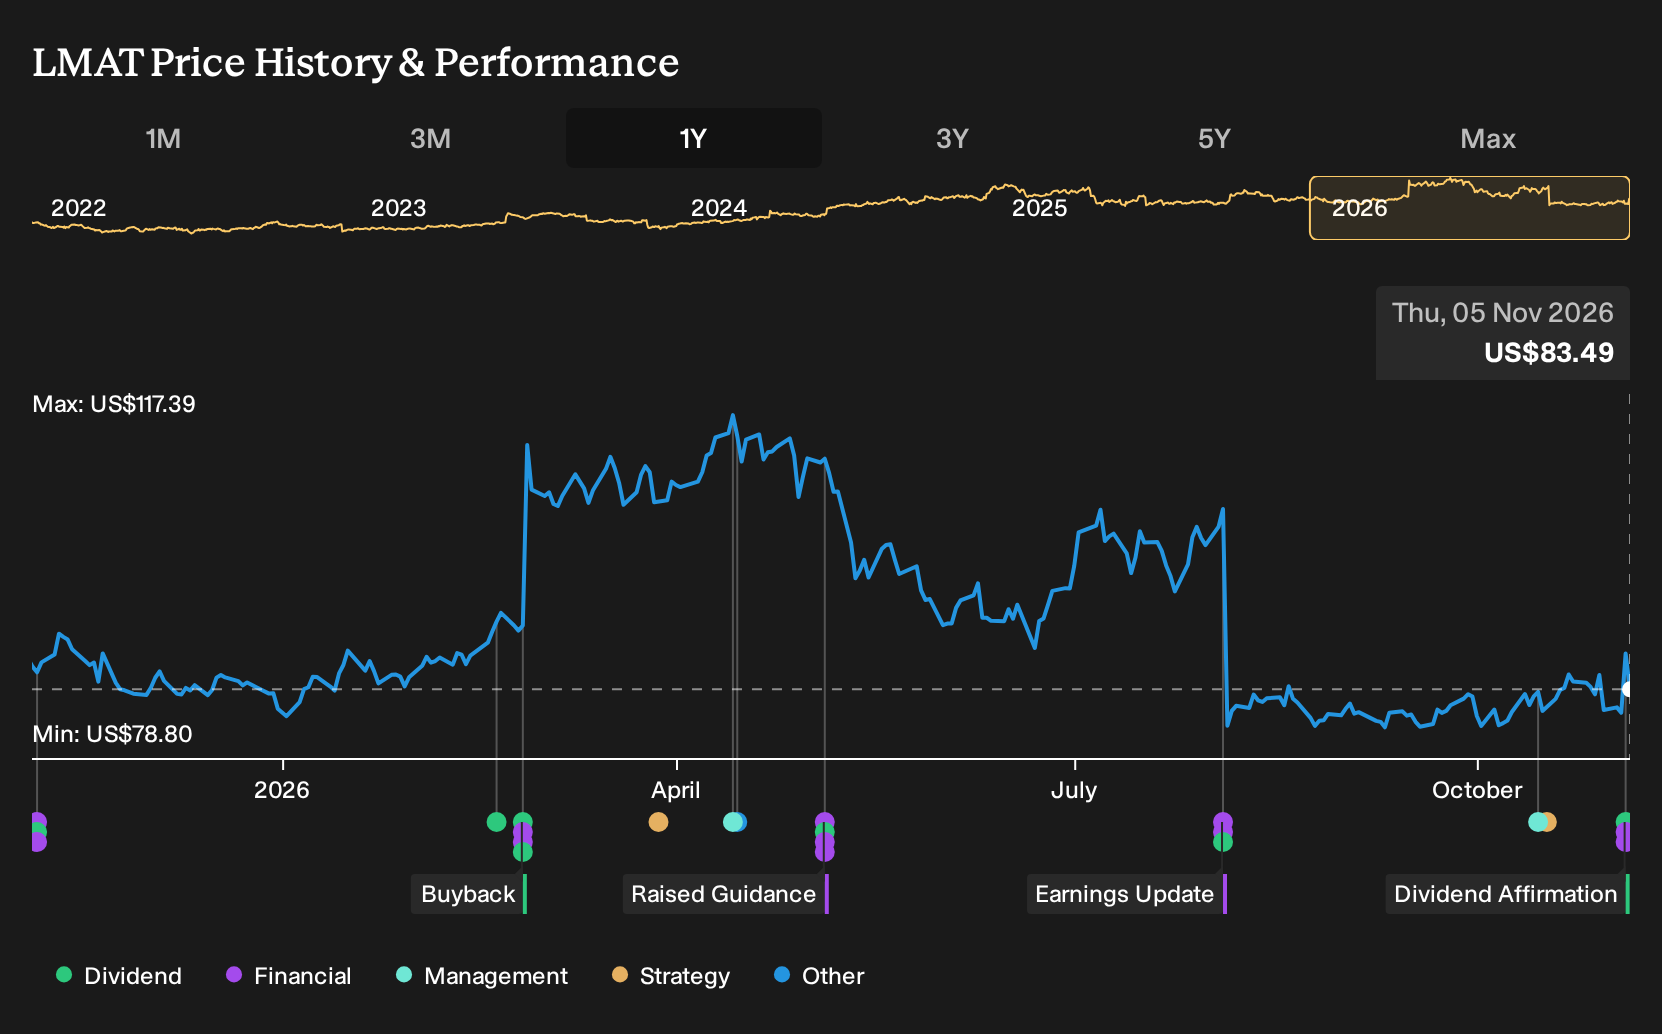
- LeMaitre Vascular reported third quarter 2026 sales of US$67.97 million and net income of US$15.02 million, alongside updated guidance for fourth quarter and full year 2026 and approval of a US$0.25 quarterly dividend payable in December.
- The mix of higher sales with lower quarterly earnings per share, together with management’s full year outlook and dividend decision, gives a clearer view of how LeMaitre Vascular is balancing growth investment, profitability and capital returns.
- We will now look at how LeMaitre Vascular’s updated full year 2026 earnings guidance could reshape the investment narrative around the business.
Compare LeMaitre Vascular’s mix of growth, earnings power and dividends with a hand-picked 42 high quality undervalued stocks that shares a similar level of financial discipline and balance between reinvestment and shareholder payouts.
LeMaitre Vascular Investment Narrative Recap
To own LeMaitre Vascular, you need to believe the business can keep growing its vascular portfolio while protecting margins through pricing, mix and the logistics buildout. The latest quarter shows that trade off clearly. Sales stepped up, but quarterly EPS from continuing operations softened, so execution on cost and mix looks like the key short term catalyst.
The main risk still sits around operational hiccups rather than demand. Prior guidance trims showed how quickly FX, regional disruptions or tissue constraints can affect earnings. The new full year 2026 outlook frames those pressures, but does not radically change the near term risk reward balance.
The most relevant update here is the new 2026 guidance. Management is now pointing to full year sales of US$247.7 million to US$276.8 million and EPS of US$2.77 to US$2.82. That range provides a yardstick to judge how well LeMaitre Vascular converts its strong nine month sales and net income so far into year end performance.
For catalysts, that guidance ties directly to execution on Artegraft growth, the tissue supply ramp and the direct distribution rollout. Any signs that FX, regulatory work or product availability pull actual results away from the guided ranges would speak directly to the biggest current risk, which is operational slippage rather than end market demand.
LeMaitre Vascular's current analyst story points to revenues of US$339.3 million and earnings of US$84.3 million by 2029, based on an assumed 8.9% yearly revenue growth rate. This would mean earnings rising by about US$18.6 million from the US$65.7 million reported today to reach the consensus forecast in that same year.
Uncover why LeMaitre Vascular's fair value indicates a 28% potential upside to its current price and why this gap could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Artegraft as the key swing factor. Before this latest LeMaitre Vascular earnings release, the bullish camp was using roughly US$354.4 million of 2029 revenue and US$88.5 million of earnings to justify higher targets. That is a very different story. Use this quarter as a fresh reference point, and compare several viewpoints before deciding what makes sense to you.
Explore 4 other LeMaitre Vascular fair value estimates, including one that suggests there could be as much as 58% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your LeMaitre Vascular research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for LeMaitre Vascular. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate LeMaitre Vascular's overall financial health at a glance.
Looking For More Investment Ideas Beyond LeMaitre Vascular?
If this LeMaitre Vascular update has sharpened your view on quality, income and risk, you can use that same playbook to scan a wider pool of opportunities with the Simply Wall St Screener. Start with clear filters, then let the data surface stocks that actually fit your approach rather than forcing a story to match a ticker.
- If you care most about resilient businesses with measured risk, filter for lower volatility profiles and steady fundamentals using our 32 resilient stocks with low risk scores.
- If you are income focused and looking for stronger cash returns than LeMaitre Vascular's US$0.25 quarterly payout, while still keeping an eye on balance sheet strength, then shortlist ideas with the 6 dividend fortresses.
- If you prefer to hunt for underfollowed opportunities where quality and fundamentals matter more than headlines, then build your watchlist from the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com