


EN
Nokia Oyj (HLSE:NOKIA) Dropped, So What Is Behind The Latest Attention?
AT&T’s recent test of a direct-to-device satellite handoff, supported by Nokia Oyj (HLSE:NOKIA), placed the Finnish network supplier at the center of a closely watched connectivity experiment for everyday smartphones.
Nokia Oyj’s recent satellite handoff role comes at a moment when momentum in the share price has cooled in the short term. The stock is down 7.51% on a 1-day basis and 28.70% over 30 days, even as the year-to-date share price return is 23.93% and the 3-year total shareholder return is 129.10%. This suggests that longer term holders have experienced very different conditions compared with those focusing only on the past few weeks.
Scan other telecom and AI infrastructure players with similar satellite and 5G ambitions using our hand picked shortlist of 53 AI infrastructure stocks alongside Nokia Oyj.
The recent slide in Nokia Oyj’s share price can signal doubts about the business or just a sharp swing in mood. Which story do the current valuation markers actually support next?
Most Popular Narrative: 55% Undervalued
Nokia Oyj last closed at €6.85, while the most widely followed narrative on the stock puts fair value at €15.16. That gap is large enough that investors are asking whether the market is missing something in Nokia Oyj’s cash flows and AI push.
Nokia delivered a strong second quarter, reporting revenue of €4.815 billion and earnings per share of €0.07, supported by growing demand for AI and cloud-related solutions. The company is also expanding its presence in the defense sector through AI-powered tools for 5G networks, creating additional opportunities to diversify revenue and strengthen long-term growth prospects.
See why 14 investors see Nokia Oyj as 55% undervalued.
According to TheTurntTomato, this story of AI and cloud demand underpins a valuation that sits well above both the current share price and a recent DCF view. That discounted cash flow estimate points to €14.58 per share using a 7.68% discount rate, still well ahead of where Nokia Oyj trades today.
The valuation case in that narrative leans on an earnings outlook that analysts expect to rise and a revenue profile forecast at 6.4% per year, alongside a business that reported €20.8b in annual sales and €785m in net income. Supporters of this view see the current quote as not just below a single fair value line but below several different takes on future cash generation.
Result: Fair Value of €15.16 (UNDERVALUED)
Still, Nokia Oyj relies heavily on telecom spending cycles and on execution in AI and defense. Delayed customer budgets or weaker product uptake could challenge this upbeat storyline.
Find out about the key risks to this Nokia Oyj narrative.
Another View: Nokia Oyj Through The P/E Lens
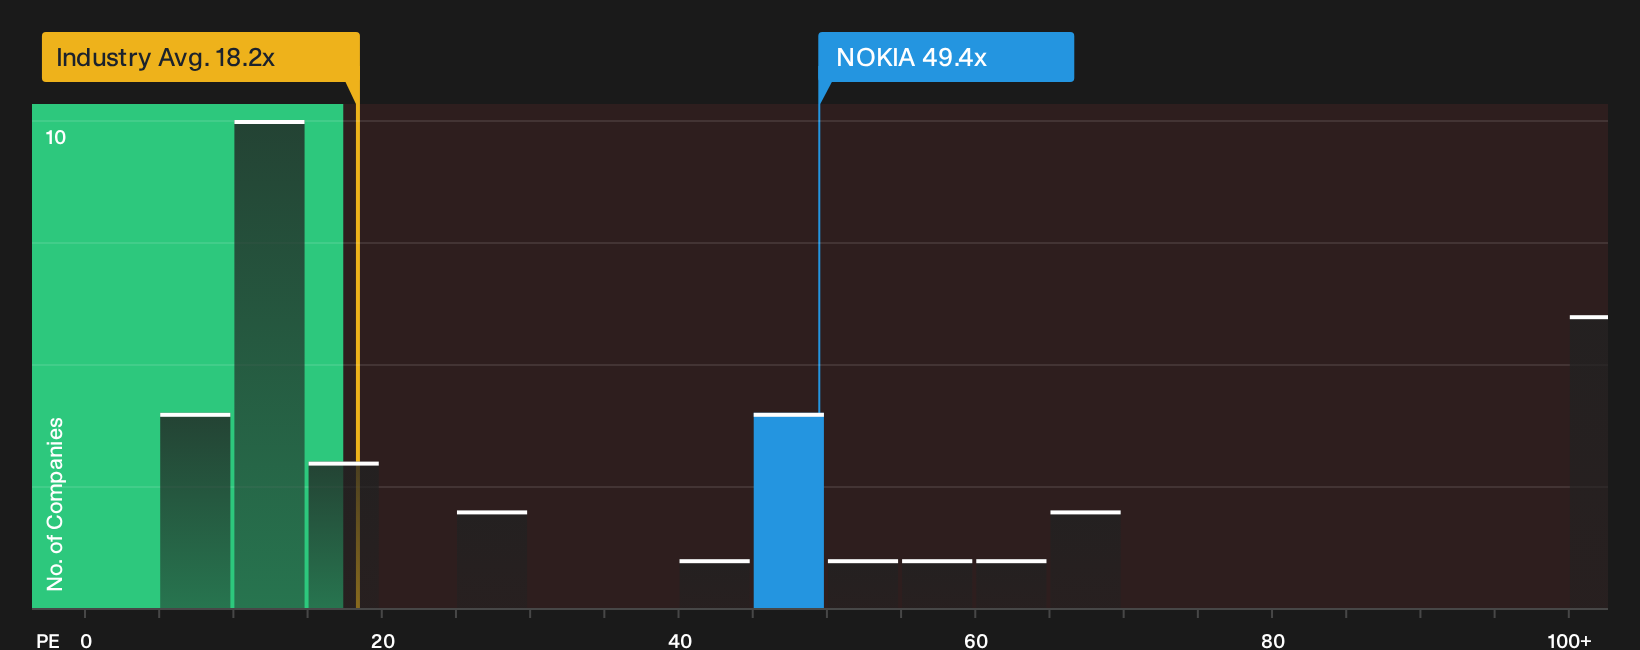
A second check on Nokia Oyj using the P/E ratio tells a very different story to the undervalued DCF and user narrative. The current P/E of 49.4x sits well above both European communications peers at 18.2x and the 29x peer group average, and it also exceeds the 41.9x fair ratio that the market could move towards. That kind of premium can point to higher valuation risk if earnings or sentiment slip, so how comfortable are you paying more than sector and fair ratio benchmarks for the same stream of profits?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nokia Oyj can feel messy, so move quickly to test the upside story against the red flags and form your own stance with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Nokia Oyj?
You have Nokia Oyj on your radar. Now widen the lens and use the Simply Wall Street Screener to spot other opportunities before they move without you.
- Target resilience first by checking companies on our 215 resilient stocks with low risk scores that aim to balance potential returns with tighter risk profiles.
- Hunt for quality at a discount through the 211 high quality undervalued stocks, where stronger fundamentals and pricing gaps often sit side by side.
- Build income potential into your watchlist with the 215 dividend fortresses and see which payouts look more durable on the numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com