


EN
Cytokinetics (CYTK) Stock Looks Hard To Judge On Book Value
Cytokinetics has had a mixed run in recent years, with a strong multi year gain sitting alongside a weaker stretch in 2026. That puts a spotlight on whether the current share price lines up with the business’s book value. With fresh trial data, ongoing regulatory work and expanding commercial activity all in play, the question is how much of that story is already captured in the stock’s accounting base.
- Over the past 3 years the share price has climbed 68.0%, which raises the issue of how that move compares with the value recorded on Cytokinetics’ balance sheet.
- Recent progress in heart disease treatments and regulatory filings can shift expectations for future revenue and funding needs, which are both key to how investors weigh the stock against its reported equity value.
- The analysts covering Cytokinetics have run their own numbers. See what analysts think Cytokinetics's shares could be worth.
The issue now is whether Cytokinetics’ current market price is well supported by its book value once you strip the story back to the balance sheet.
If you want a second reference point alongside Cytokinetics when weighing book value against recent news and price swings, a focused screen of 32 resilient stocks with low risk scores can help you build a calmer comparison set.
Putting Cytokinetics in Context on Book Value
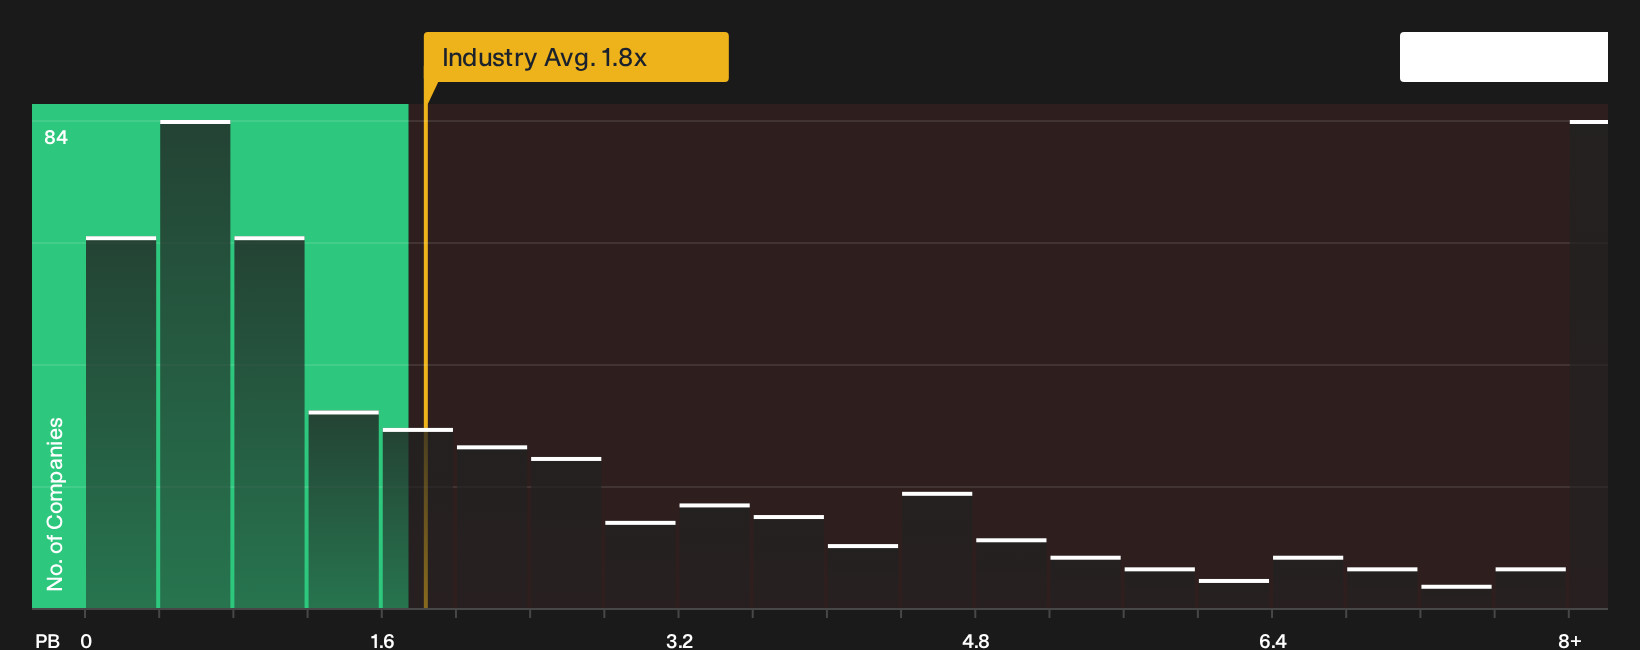
The P/B ratio is usually a useful way to think about Cytokinetics because a lot of the story still runs through the balance sheet rather than current earnings. For this stock the figure is unusual. The reported P/B is -24.1x, which comes from the business having a book value that has moved below zero, so there is no positive equity base to anchor the metric.
Because shareholder equity is negative, that P/B reading does not tell you whether the share price is high or low on a typical asset basis, and it cannot be lined up cleanly against other biotechs with positive book value. The strong Q3 2026 update, with higher MyCorzo revenue and ongoing trial and regulatory activity, means investors are effectively leaning on expectations around future cash generation and approvals rather than today’s accounting capital when they price Cytokinetics. To judge where the valuation really sits, you need to weigh the pipeline, cash runway and potential deal or funding scenarios instead of relying on this single multiple. With this multiple ruled out, take a closer look at what Cytokinetics's balance sheet and debt position show instead.
The Cytokinetics Narrative: What Would Justify Today's Price?
Narratives pick up where Cytokinetics' awkward P/B ratio leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the equity to be worth materially more or less than today's price, and they live on Simply Wall St's Community page. Instead of stopping at a single valuation output, Narratives break down the operating assumptions that sit underneath it so you can track over time whether the real world still matches that picture.
One of the top community narratives on Cytokinetics: 32% undervalued
"The main thing that has to go right is that Cytokinetics converts early MYQORZO uptake and aficamten’s first-in-class nHCM data, plus upcoming regulatory and guideline milestones, into a durable commercial HCM franchise..."
Discover why this Narrative puts Cytokinetics at 32% undervalued.
An unresolved question for Cytokinetics: who is selling and why
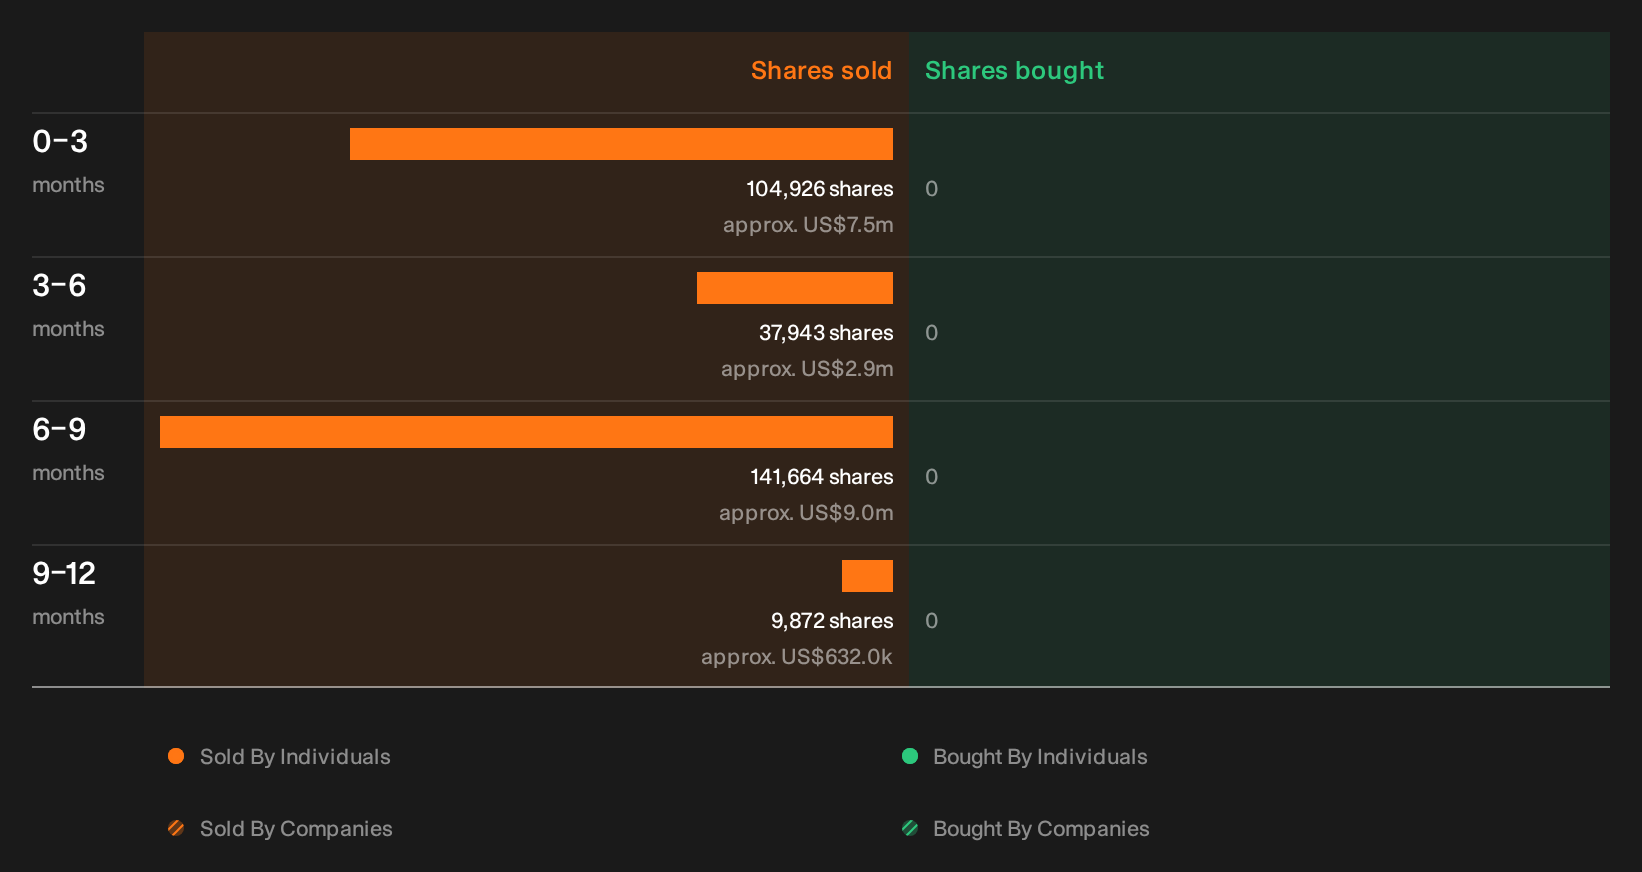
One important angle still sits off to the side. Recent checks have picked up insider share sales, and the identities, sizes and possible meanings of those trades are left for you to scrutinise. See the recent insider selling flagged for Cytokinetics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com