


EN
OneSpaWorld Holdings (OSW) Lifts Guidance And Payouts, Is The Valuation Still Attractive?
Why OneSpaWorld’s Latest Earnings Matter For Investors
OneSpaWorld Holdings (OSW) just packed several shareholder focused moves into a single update. Fresh quarterly earnings, higher full year revenue guidance, a 25% dividend lift, and a larger buyback now sit on the table.
The business reported third quarter revenue of US$276.53 million and net income of US$28.24 million, alongside new expectations for 2026 sales between US$1.033b and US$1.038b and a bigger capital return plan.
OneSpaWorld Holdings has ridden a strong wave of optimism, with a 30 day share price return of 31.96% and a year to date share price gain of 48.84%. The 3 year total shareholder return of 184.90% points to momentum that predates this quarter’s earnings, guidance lift, dividend increase, and fresh buyback authorization.
Scan beyond OneSpaWorld Holdings and see how it compares with other shareholder friendly businesses returning cash through dividends and buybacks in our curated list of 6 dividend fortresses.
For OneSpaWorld, that sharp rerating now forces a simple test: Are investors finally catching up to the underlying cruise and resort wellness engine, or has sentiment sprinted ahead of what the current valuation supports?
Most Popular Narrative: 6% Undervalued
Against a last close of $30.72, the most followed narrative pegs OneSpaWorld Holdings at a fair value of $32.60, which points to a modest valuation gap that hinges on how the cruise wellness thesis plays out.
The main factor is that medi-spa services, AI tools across the fleet and rising prebooked service volumes continue to translate into higher revenue per guest and better margins without offsetting cost pressures.
Current pricing of OneSpaWorld shares implies the market is not fully crediting the company for its embedded cruise fleet growth, faster-growing medi-spa offering and capital-light cash generation, which supports the view that the stock is undervalued and the setup is positive.
See why 6 investors see OneSpaWorld Holdings as 6% undervalued.
Result: Fair Value of $32.60 (UNDERVALUED)
Still, the OneSpaWorld story can change quickly if cruise traffic is disrupted or if resort and product weakness offsets shipboard medi spa momentum.
Find out about the key risks to this OneSpaWorld Holdings narrative.
Another View On What OneSpaWorld’s Price Is Saying
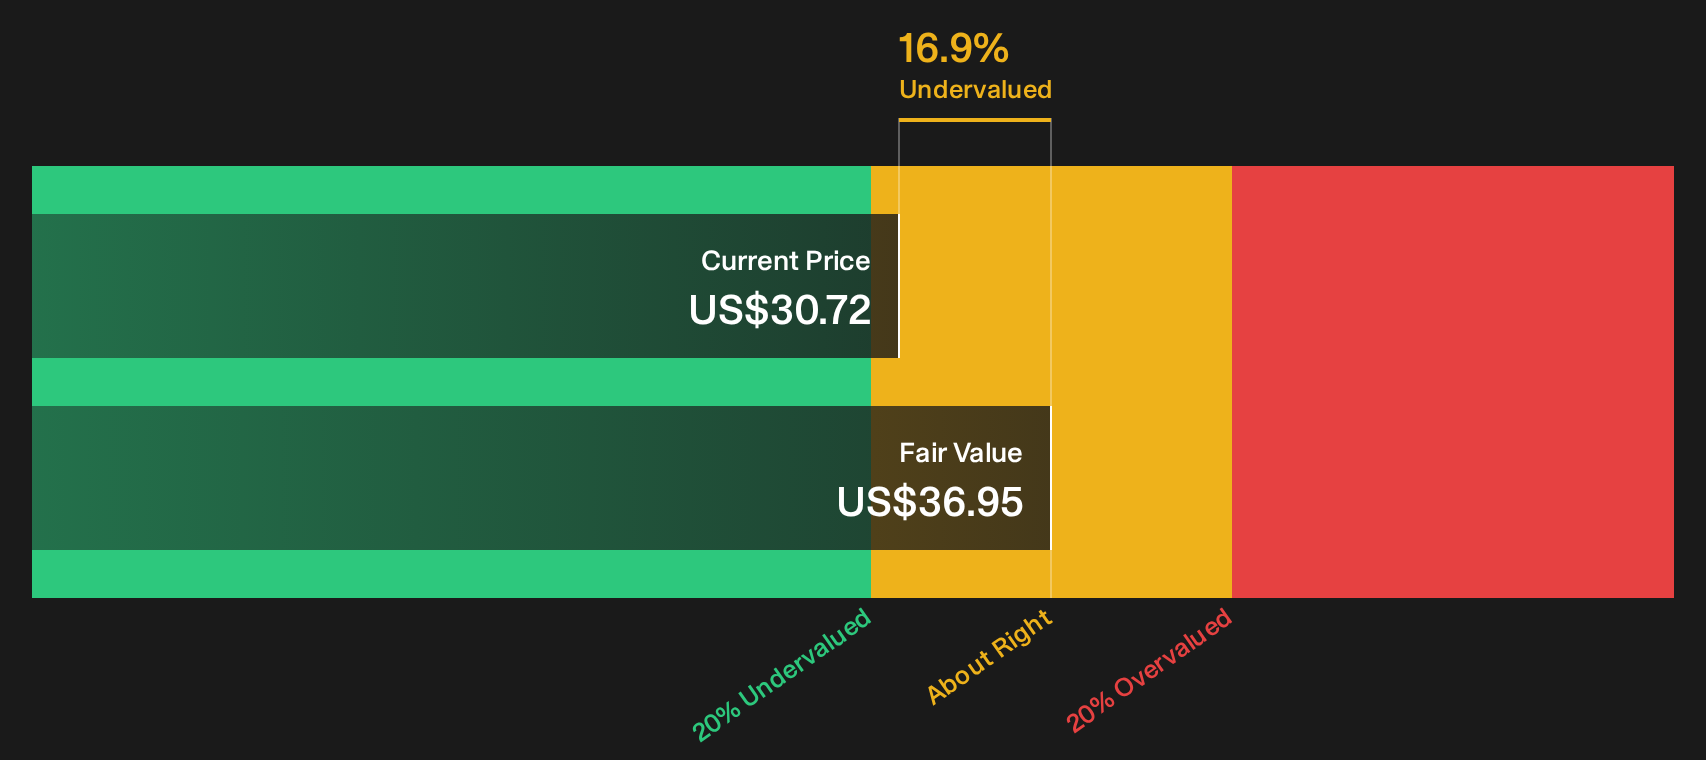
The story so far leans on cash flow and analyst fair value estimates that place OneSpaWorld Holdings at $32.60 per share, with a DCF based future cash flow value at $36.95, both pointing to undervaluation. The price tag tells a different story once earnings multiples enter the frame.
On a P/E of 36.2x, OneSpaWorld trades at more than double the US Consumer Services sector on 12.2x and sits well above its own fair ratio of 20.6x. That gap suggests investors are already paying up for quality and growth. The question is whether your assumptions justify that premium or lean more toward the cash flow case.
Look into how the SWS DCF model arrives at its fair value. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and caution around OneSpaWorld Holdings feels finely balanced, treat it as your cue to review the underlying data, weigh the key risks against the potential upsides, and ground your own judgment in both. To see the full spread of risk flags and upside drivers that other investors are focused on, take a closer look at the 3 key rewards and 1 important warning sign.
Looking For More OneSpaWorld Style Investment Ideas?
If OneSpaWorld Holdings has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target durable, cash rich businesses by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and still support long term plans.
- Spot potential value candidates early by running through a curated 42 high quality undervalued stocks before enthusiasm pushes expectations and prices higher.
- Strengthen your income stream by reviewing a focused 6 dividend fortresses that highlights companies returning meaningful cash to shareholders.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com