


EN
Fluor Stock In Focus After Data Center Deal And Venezuela Partnership
- Fluor recently secured full notice to proceed on a fourth grinding line for Sierra Gorda in Chile, signed an EPC contract for three TeraWulf data center buildings in Kentucky, and agreed an MOU with Venezuelan firm Inelectra to pursue energy, petrochemical, and industrial work in Venezuela.
- These wins point to Fluor leaning into complex mining, power hungry data infrastructure, and higher risk international energy work. Taken together, they test how its asset light, reimbursable heavy model handles execution risk, local partners, and capital discipline across very different end markets.
- We will now look at how Fluor's investment narrative is influenced by these EPC awards, with particular attention to the TeraWulf data center contract.
Fluor Investment Narrative Recap
To own Fluor, you need to believe the firm can turn its large backlog and prospect pipeline into steadier earnings under its asset light, reimbursable heavy model. The immediate swing factor is execution quality on complex work, because the business is still working through unprofitable projects and guidance has already been revised once.
The biggest near term risk remains fresh cost pressure or field productivity issues on lump sum and hybrid EPC jobs, which could hit margins and cash generation. These new awards add volume and diversification, but do not clearly change that core risk reward equation in the short term.
The TeraWulf EPC contract in Kentucky is the clearest operational test tied to current catalysts. Management has been focusing on electricity hungry data infrastructure and gas fired power, and this data center work fits directly into that theme. It also supports the goal of turning a large prospect list into real, revenue producing projects.
Contract terms matter here. Fluor is responsible for cost overruns up to a percentage of its profit, so execution discipline is important for margins and cash flow, especially while the company is still unprofitable on a net income basis. Early works already underway should give investors some insight into risk management and how effectively Fluor prices and controls newer, power intensive data center builds.
Fluor's analyst narrative points to revenues of US$19.7b and earnings of US$497.9m by 2029, which implies revenue expansion of 8.3% a year and an earnings swing of about US$2.5b from a current loss of US$2.0b to the forecast profit level.
Discover how Fluor's fair value indicates a 37% potential upside to its current price, which could close sooner than you expect.
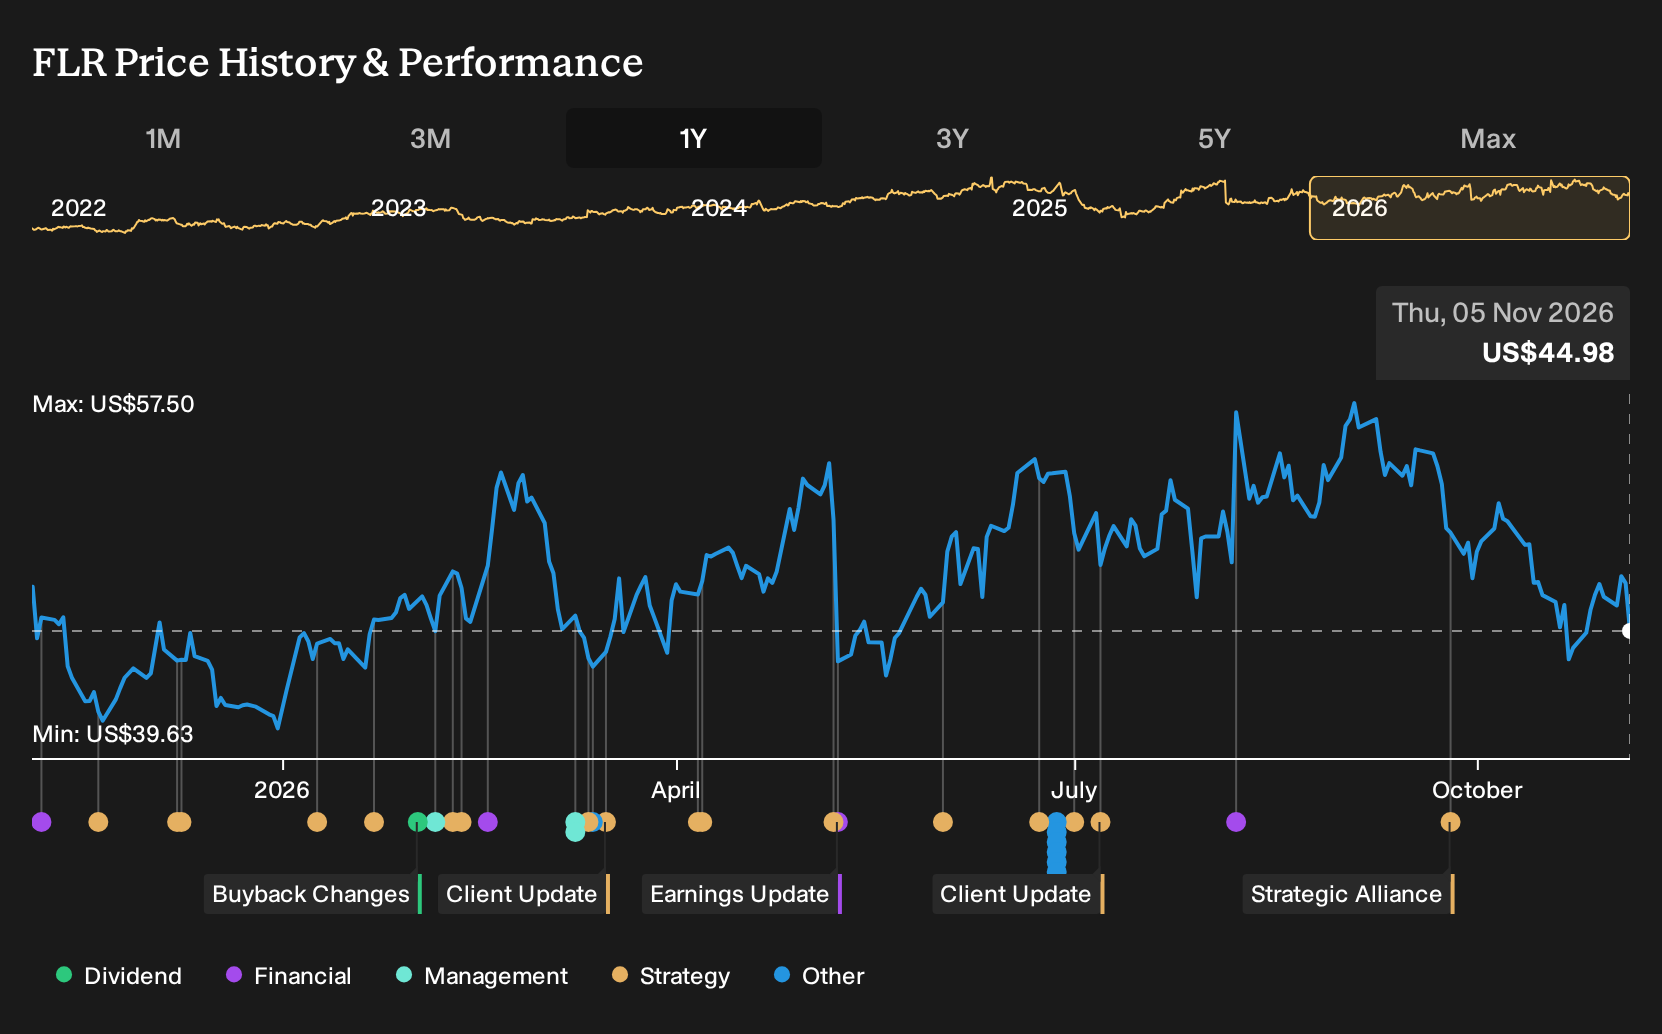
Exploring Other Perspectives
One alternate angle on Fluor focuses less on new mining and data center projects and more on how fast legacy loss contracts actually roll off. The most optimistic analysts were already working with 12.2% annual revenue growth and earnings of about US$743.4m by 2029 before this news. You can compare those assumptions with your own view and decide whether these fresh EPC wins in Chile, Kentucky and Venezuela could change that story, or simply alter the risk profile around it.
Explore 4 other Fluor fair value estimates, including one that suggests as much as 58% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fluor research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Fluor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fluor's overall financial health at a glance.
Looking For More Ideas Beyond Fluor?
If the Fluor story has you thinking about position sizing, risk and where to allocate fresh capital, it can help to line it up against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, check out a shortlist of potential high yield payers through 6 dividend fortresses that may suit a steady cash flow focus.
- If your priority is resilience over excitement, filter for companies with stronger balance sheets and cleaner fundamentals using the list of solid balance sheet and fundamentals (25 results) to stress test your downside risk.
- If you are hunting for underfollowed opportunities, cast a wider net across lesser known but fundamentally sound businesses with the 21 high quality undiscovered gems to see what else might deserve a spot on your radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com