


EN
Share Buyback Plan Could Be A Big Deal For Harvey Norman Shares
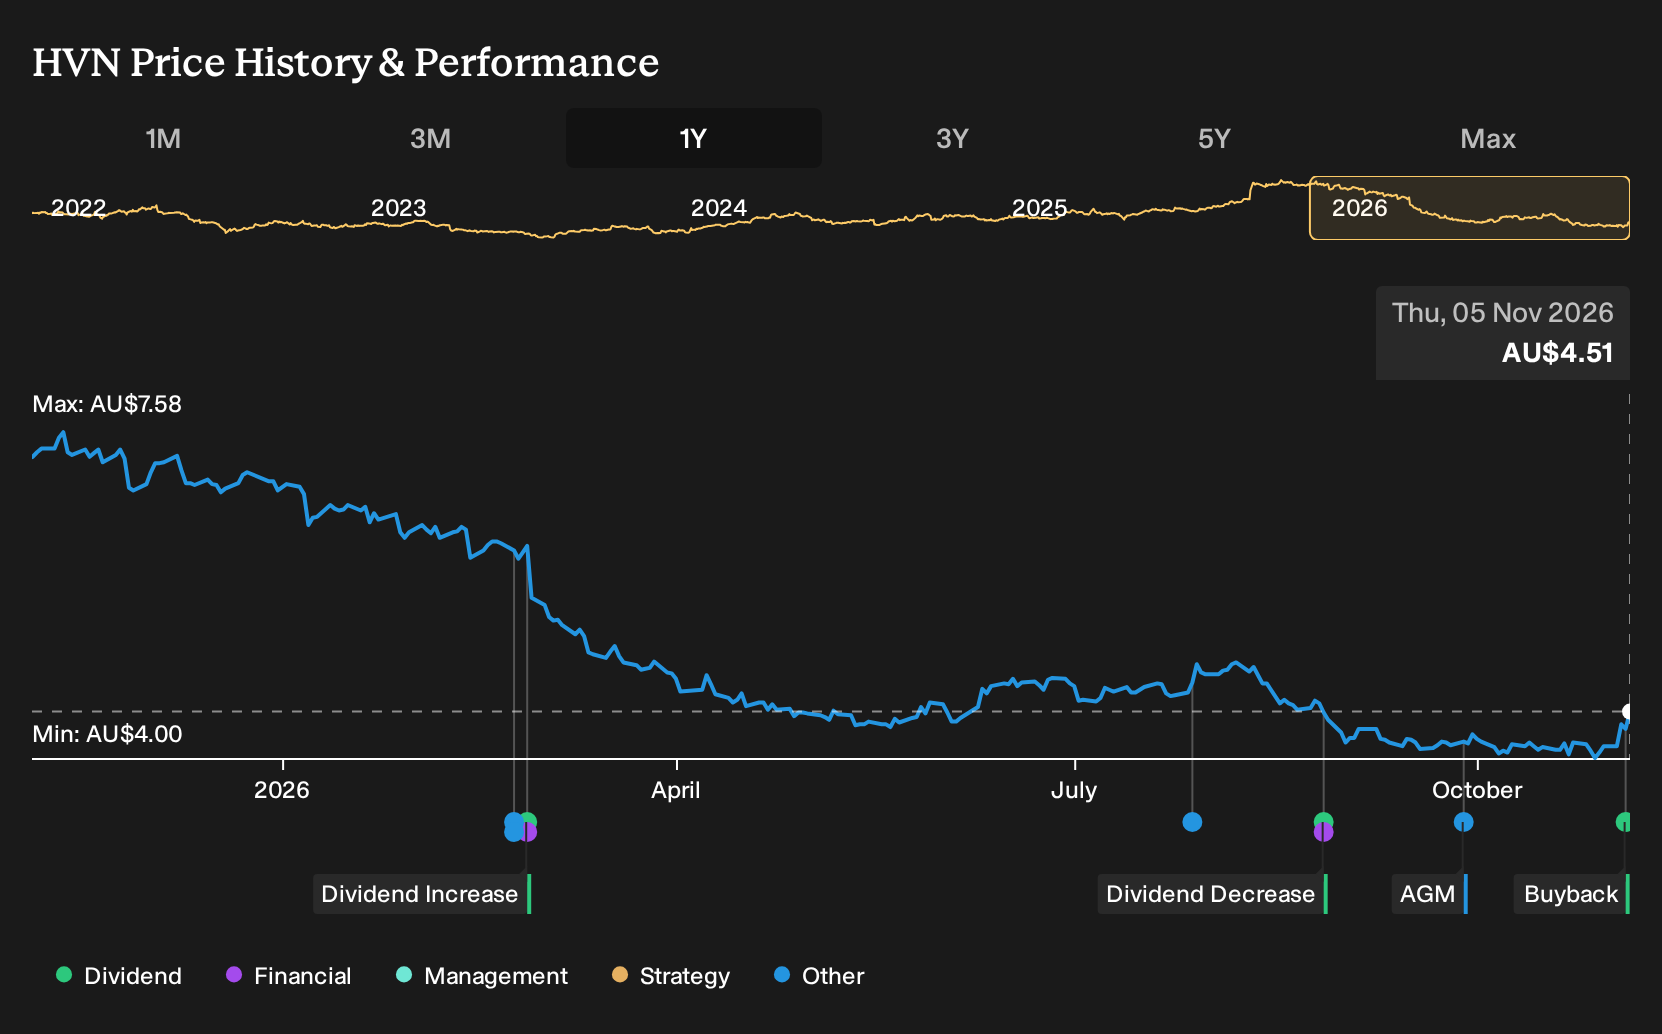
- Harvey Norman Holdings has approved a share repurchase program that allows the business to buy back up to 124,600,665 shares, or 10% of its issued capital, by November 23, 2027, following Board authorization on November 3, 2026.
- The buyback leans on Harvey Norman Holdings' mix of retail and property interests. A meaningful slice of prior profit came from volatile, non-cash property revaluations rather than recurring operating earnings.
- The focus now shifts to how Harvey Norman Holdings' sizeable share repurchase authorization shapes the broader investment narrative around earnings quality and capital discipline.
What Is Harvey Norman Holdings' Investment Narrative?
To own Harvey Norman Holdings, you need to be comfortable with a retail and property hybrid that leans on a founder influenced franchise model. The big picture belief is that a broad footprint in furniture, electronics and bedding, backed by owned shopping complexes, can keep generating solid cash flow even as reported profit moves around. That mix has trade offs. Over 20% of 2025 profit came from property revaluations, which can make earnings look stronger than the underlying shop floor performance.
The newly approved buyback sits right in the middle of that tension. Management is effectively saying the A$5.6b enterprise and its A$4.51 share price justify retiring up to 10% of the register by late 2027. For near term catalysts, the key question is whether operational earnings and franchise fees can comfortably support both this capital return and ongoing property investment, especially with earnings forecasts pointing to a very slight decline even as revenue is expected to rise.
Yet there is still one pressure point that could make this whole capital return story feel a lot less comfortable if ...
There's only one way to know the right time to buy, sell or hold Harvey Norman Holdings. Head to Simply Wall St's company report for the latest analysis of Harvey Norman Holdings's Fair Value.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between A$4.55 and A$6.11 per share, which already gives you a wide spread on Harvey Norman Holdings before factoring in the newly announced buyback. Opinions clearly differ. It therefore helps to compare these community views with your own assessment of earnings quality and property exposure.
Explore 2 other Harvey Norman Holdings fair value estimates, including one that suggests it could be worth just A$4.55.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harvey Norman Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Harvey Norman Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harvey Norman Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Harvey Norman Holdings?
If Harvey Norman Holdings has you thinking about capital allocation, income, and balance sheet strength, it can help to line it up against other opportunities on the Simply Wall St Screener. Use different angles to pressure test your approach and see which companies really fit your risk and return preferences.
- For investors who want potential mispricings with quality fundamentals, scan a curated 5 high quality undervalued stocks that might merit a closer look on your watchlist.
- If reliable income streams matter to you, focus on payout strength and consistency by reviewing a hand picked 5 dividend fortresses that could suit a dividend focused approach.
- When capital protection and resilience come first, concentrate on stability by working through a carefully filtered 6 resilient stocks with low risk scores tailored to lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com