


EN
How Studio Two Launch Will Impact Wix (WIX) Investors
- Wix.com has launched Studio Two, an AI-native editor that lets professionals design on canvas or in React, move projects in and out of Wix as standard code, and deploy sites either on Wix infrastructure or externally while using built-in business solutions.
- The new Aria 2.0 agent, Skills system and open component model indicate Wix.com is pushing deeper into higher value agency and enterprise workflows by combining AI automation with flexible deployment and custom development options.
- We will now look at how Wix.com's investment narrative might be shaped by Studio Two’s open, AI-native approach to professional site creation.
Wix.com Investment Narrative Recap
To own Wix.com, you need to believe its heavy AI push turns into stickier, higher value projects across agencies, SMBs and larger clients. Studio Two fits that story by tying AI, React code and visual editing into one workflow, which can support the existing thesis around AI driven tools, BASE44 and broader SMB operations.
The next near term swing factor is execution on monetising these AI layers while earnings expectations for the current year have been revised lower. Studio Two does not remove the biggest risk, which is that websites and no code tools get commoditised or displaced by other AI surfaces, leaving Wix.com spending heavily on AI and marketing without enough margin improvement.
The most relevant recent datapoint around this launch is the expectation for lower quarterly earnings per share even as revenue is forecast to rise year over year. That combination keeps the focus squarely on whether Studio Two, Harmony, Symphony and BASE44 together can shift Wix.com from AI spend into AI driven operating leverage over time.
Mixed near term profit expectations and a Zacks Rank #3 (Hold) frame Studio Two as an execution test rather than a clear win. For you as a shareholder, the question is whether this open, AI native platform can strengthen conversion to paid, raise average project value and support the guided improvements in BASE44 gross margin without letting AI costs and marketing outgrow the benefit.
Wix.com’s current analyst playbook ties Studio Two directly to some punchy long term numbers. The consensus narrative points to about US$3.0b in revenue and US$222.7m in earnings by 2029, built on an assumed 11.6% yearly rise in sales. That path would require earnings to swing by roughly US$397m from an earnings loss of US$174.6m today to the projected US$222.7m figure. This represents a very large change in profit that Studio Two and the broader AI stack are implicitly being asked to support.
Uncover why Wix.com's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
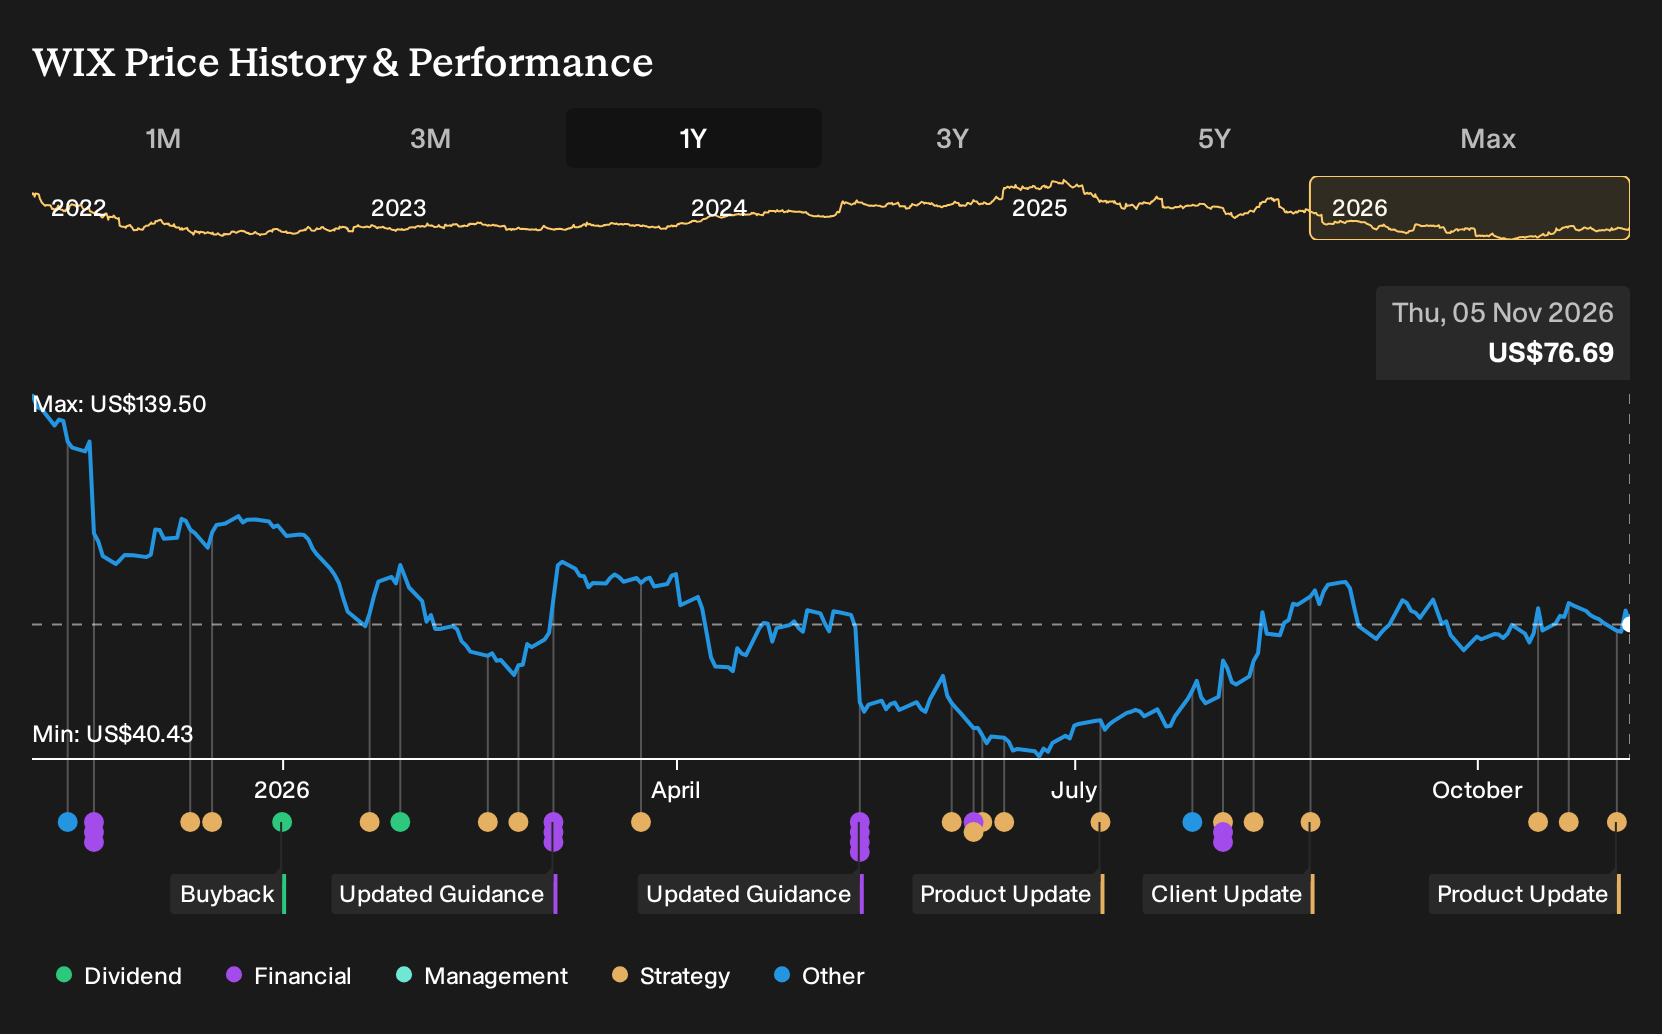
Exploring Other Perspectives
One bearish twist focuses on Wix.com’s cost base. The most cautious analysts treated AI projects as a drag, even before Studio Two, and built their story around slower monetisation, with revenue reaching about US$2.9b and earnings near US$161.4m by 2029. That is a much harsher read. Use it as a cue to explore multiple angles.
Explore 8 other Wix.com fair value estimates, including one that suggests as much as 35% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Wix.com research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Wix.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wix.com's overall financial health at a glance.
Looking for more investment ideas beyond Wix.com?
If Studio Two has you thinking harder about where AI heavy workflows and recurring revenue models might show up next, it can help to scan a broader watchlist, compare fundamentals quickly and then focus only on the opportunities that genuinely fit your risk profile.
- For investors hunting for value with quality backstops, start with a curated group of businesses trading below their estimated worth through 42 high quality undervalued stocks.
- If capital preservation and smoother ride matter most to you, concentrate your search on companies with sturdier balance sheets and lower risk profiles using the 32 resilient stocks with low risk scores.
- When you want a watchlist of financially resilient operators rather than story stocks, build it around a list of solid balance sheet and fundamentals (25 results) that can support growth plans through multiple cycles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com