


EN
InnovAge Holding (INNV) Could Be 24% Undervalued After Strong Quarter And Guidance Reaffirmed
Why InnovAge Holding’s latest quarter matters for investors
InnovAge Holding (INNV) just posted first quarter results that showed higher revenue and net income compared with a year earlier, and reaffirmed its 2027 revenue outlook in the US$1.05b to US$1.085b range.
Despite the strong quarterly update, InnovAge Holding’s share price fell 7.05% over the last day and is down 18.60% over the past 90 days. However, the year-to-date share price return of 75.34% and 1-year total shareholder return of 86.48% still point to strong positive momentum.
Scan 21 high quality undiscovered gems that, similar to InnovAge Holding after this earnings jump and guidance confirmation, may have improving fundamentals that the wider market has not fully priced in yet.
After a strong run this year and a sharp pullback after earnings, InnovAge Holding now sits at an awkward middle ground. Do current expectations and guidance still leave enough upside to justify the risk?
Most Popular Narrative: 24% Undervalued
InnovAge Holding is framed as undervalued in the most followed narrative, with a fair value of $12 against a last close of $9.10, and that gap is anchored in long range earnings and margin assumptions rather than short term sentiment.
Geographic expansion into new markets and underpenetrated states, coupled with improved enrollment efficiency, is enabling InnovAge to leverage its existing infrastructure for scalable growth, setting the stage for higher long-term revenue and operating leverage.
See why 2 investors see InnovAge Holding as 24% undervalued.
Result: Fair Value of $12 (UNDERVALUED)
Still, the bullish InnovAge Holding narrative depends on medical costs remaining tightly controlled and de novo center losses easing, and both could easily move the other way.
Find out about the key risks to this InnovAge Holding narrative.
Another View: What InnovAge Holding’s P/E Ratio Is Telling You
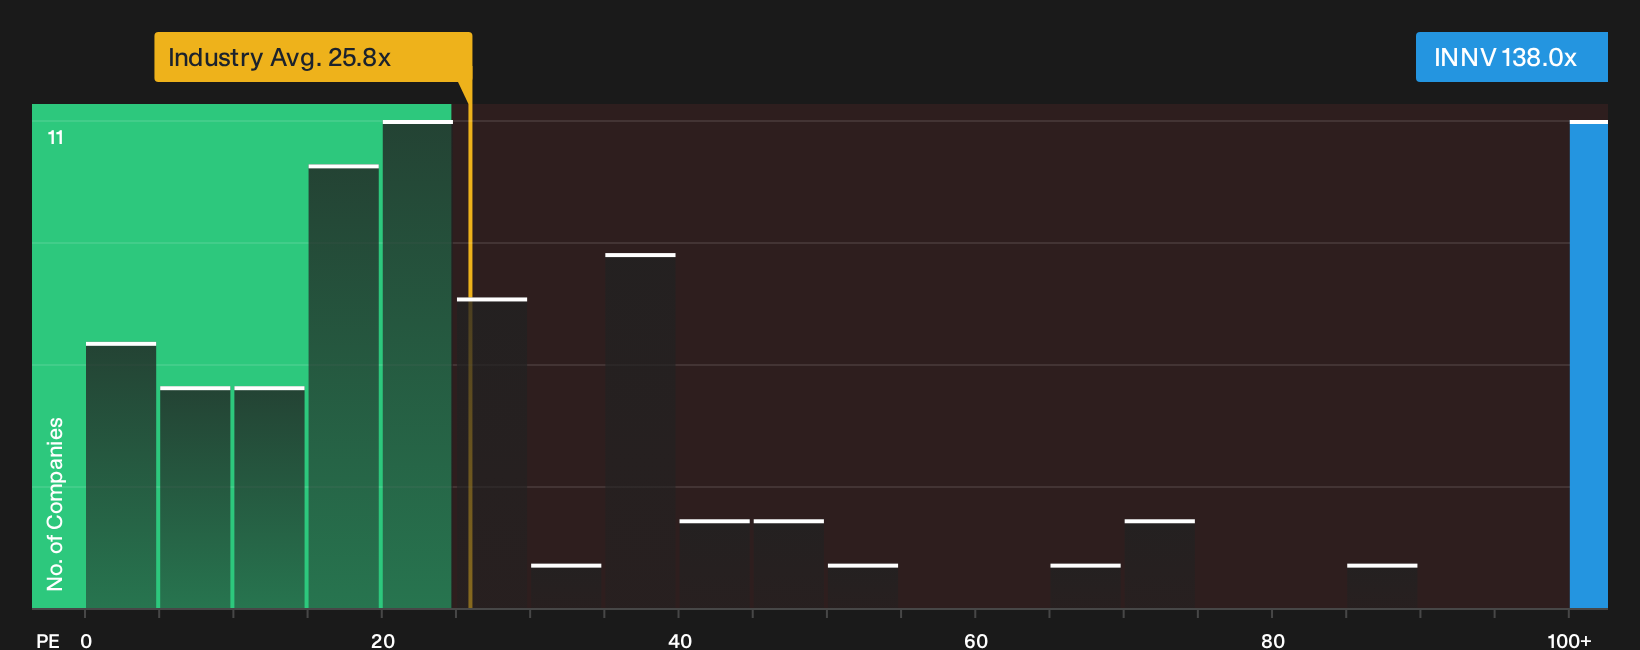
The bullish narrative around InnovAge Holding leans heavily on a fair value of $12 and upbeat growth forecasts. The market’s current P/E of 138x tells a very different story. It is far higher than the US Healthcare group at 25.8x and above a fair ratio estimate of 66.3x.
That kind of gap implies investors are already paying a premium price for earnings that are still modest. This raises the risk that any stumble in margins or guidance reset could hit the share price harder than the headline DCF style upside suggests. Is this valuation cushion or a tightrope?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around InnovAge Holding feels familiar, use it as a prompt to move quickly and test the numbers yourself. To see what is driving the more optimistic sentiment in the data, review the 3 key rewards.
Looking for more InnovAge Holding style investment ideas?
Do not stop with InnovAge Holding. Put this analysis to work by lining up a few fresh candidates that could sharpen your watchlist and broaden your opportunity set.
- Target steadier compounding by scanning a curated pool of resilient companies through the 32 resilient stocks with low risk scores.
- Hunt for stronger balance sheets by zeroing in on businesses that pair financial strength with solid fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Chase mispriced potential by checking out a hand picked mix of quality opportunities through the 42 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com