


EN
Clorox (CLX) On Fresh Results And A Health Push That Still Looks Fully Valued
Clorox (CLX) just posted first quarter results that put fresh numbers in front of investors. Sales came in at US$1,905 million and net income reached US$170 million, with diluted EPS of US$1.39.
Clorox shares have picked up speed recently, with a 12.4% 7 day share price return and a 19.4% 30 day share price return lifting the stock to US$99.70, even though the 1 year total shareholder return is still slightly down and longer term performance remains weaker, helped by the earnings beat, CEO transition news, and mixed ETF flows.
Scan how Clorox stacks up against other potential opportunities by comparing it with our hand picked list of solid balance sheet and fundamentals (25 results).
After that sharp rebound and with Clorox trading just above the average analyst target but well below some fair value estimates, the real tension is clear: Is the recent jump already rich, or still conservative on valuation?
Most Popular Narrative: 2% Overvalued
Clorox last closed at $99.70, a touch above the most followed fair value estimate of $97.47 that is built using a 7.24% discount rate. That small gap puts the focus on whether the health and hygiene thesis can do enough heavy lifting to justify today’s price.
The main thing that has to go right is that Clorox turns its larger health and hygiene platform, including GOJO and Clorox Healthcare, into sustained growth and profitability while managing persistent cost inflation and value seeking consumer behavior.
The current valuation implies investors are pricing Clorox as if margin pressure, muted category growth, and legal or governance overhangs will weigh more heavily on the share price than the potential upside from health and hygiene growth, ERP driven productivity, and GOJO accretion.
See why 48 investors see Clorox as 2% overvalued.
Result: Fair Value of $97.47 (OVERVALUED)
Still, stubborn input cost inflation and value focused shoppers in slower growing categories could limit how much Clorox can rebuild margins from here.
Find out about the key risks to this Clorox narrative.
Another View On Clorox’s Value
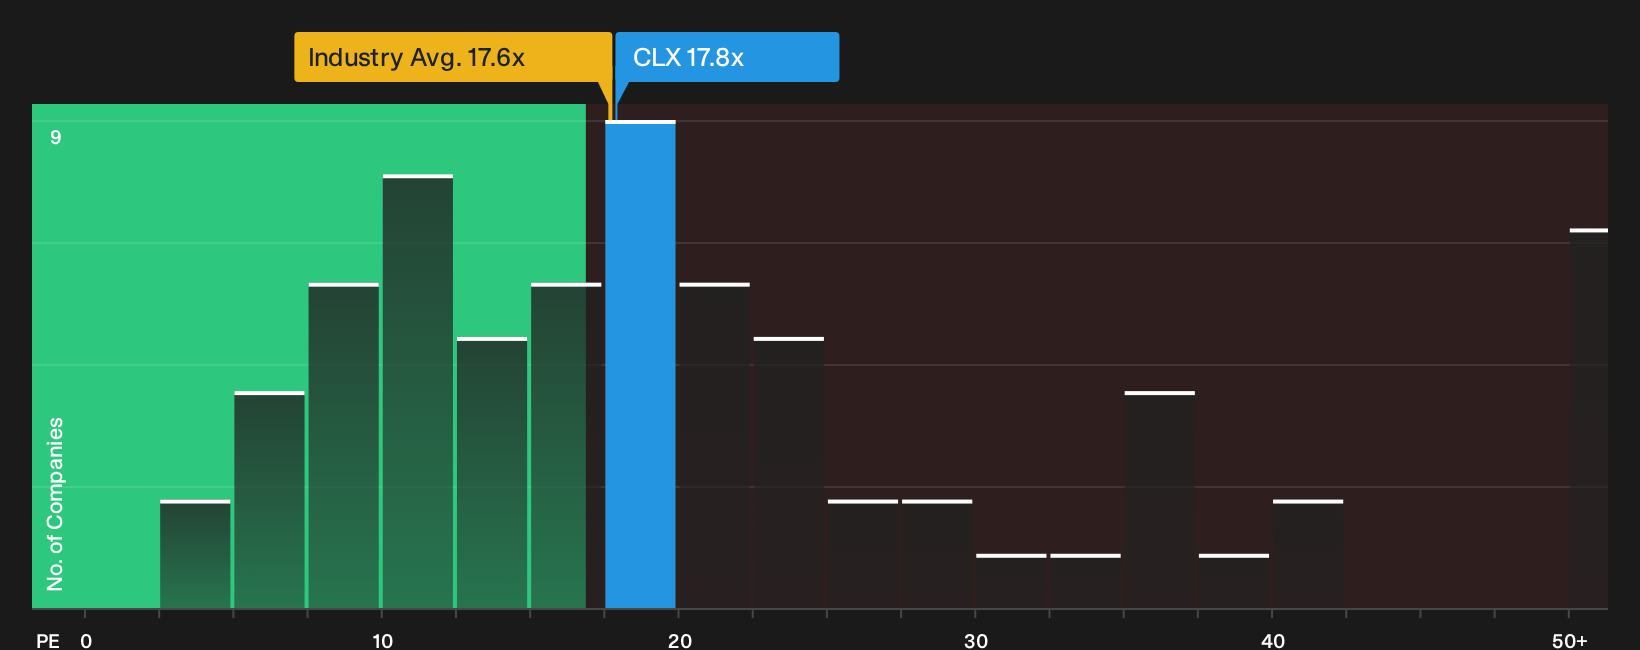
That 2% premium to the US$97.47 fair value suggests a slightly rich setup for Clorox on the narrative model. The P/E picture tells a different story. At 17.8x, CLX trades below peer averages at 27x and sits under its own 19.7x fair ratio, which points to compressed expectations. Is that a cushion or a warning if sentiment shifts?
To see how this price line squares with earnings power and where the multiple could migrate next, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Clorox is mixed, with fresh results and valuation signals pulling in different directions. This is a moment to move quickly and test the narrative against the numbers yourself. To weigh both sides of the argument in one place, start with our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Clorox?
If Clorox has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now and give yourself better options tomorrow.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that can help you stress test your current holdings.
- Hunt for mispriced quality by scanning our hand picked 42 high quality undervalued stocks that may offer stronger fundamentals than their current share prices suggest.
- Anchor your income plan with our focused 6 dividend fortresses that highlights companies combining higher yields with robust underlying financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com