


EN
Is Crombie Real Estate Investment Trust (TSX:CRR.UN) Undervalued Following Third Quarter Earnings?
Crombie Real Estate Investment Trust (TSX:CRR.UN) just posted third quarter 2026 results, reporting sales of CA$127.59 million and net income of CA$28.26 million. These figures give investors fresh numbers to reassess expectations.
Crombie Real Estate Investment Trust’s recent earnings update lands after a stretch where the share price has climbed 8.02% year to date and the 1 year total shareholder return of 17.58% points to income plus price gains working together, although the slight 90 day share price decline of 0.90% hints that momentum has cooled a little heading into this quarter’s numbers.
Compare Crombie Real Estate Investment Trust’s latest earnings shift with hand-picked real estate peers inside the 8 resilient stocks with low risk scores to see which businesses pair resilience with steadier return profiles.
The recent rebound in Crombie Real Estate Investment Trust means some gains are already on the table, yet the earnings mix still paints an unsettled picture. The key question now is how much upside is left once valuation enters the conversation next.
Preferred P/E of 28.3x: Is it justified?
Crombie Real Estate Investment Trust now carries a P/E of 28.3x against a last close of CA$16.57. This places the units on a richer earnings tag than many peers and suggests the market is paying a premium for its income stream.
The P/E ratio compares the current unit price with earnings per unit and is a common yardstick for real estate securities where profits are relatively visible. For Crombie Real Estate Investment Trust, a P/E in the high 20s implies investors are willing to pay a higher price for each dollar of reported profit, even though earnings have declined over the past year and over the last five years.
That premium comes with some tension. Reported earnings fell 34.8% over the past year and have declined 3.1% per year over five years. Profit margins sit at 21.4% compared with 34% a year ago, and interest and dividends are not well covered by earnings. Against that backdrop, a higher P/E can indicate the market is leaning on Crombie Real Estate Investment Trust’s high quality earnings assessment and its grocery anchored and mixed use portfolio, rather than on recent profit trends alone.
The comparison with peers is even starker. The broader North American Retail REITs group trades on an average P/E of 24x, while Crombie Real Estate Investment Trust’s peer set screens at roughly 15.9x. Both gaps show the trust on a materially richer multiple, which signals the market is assigning a higher value to its earnings profile than it does to the sector or close comparators.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 28.3x (OVERVALUED)
Still, Crombie Real Estate Investment Trust faces clear risks if earnings pressure persists or interest costs stay high, which could challenge that premium P/E story.
Find out about the key risks to this Crombie Real Estate Investment Trust narrative.
Another View: Cash Flow Says Crombie May Be Cheap
The high P/E paints Crombie Real Estate Investment Trust as expensive, yet the SWS DCF model points in the opposite direction. At CA$16.57, the units trade about 37.6% below an estimated future cash flow value of CA$26.56. That gap raises a simple question for investors: Which signal deserves more weight, earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
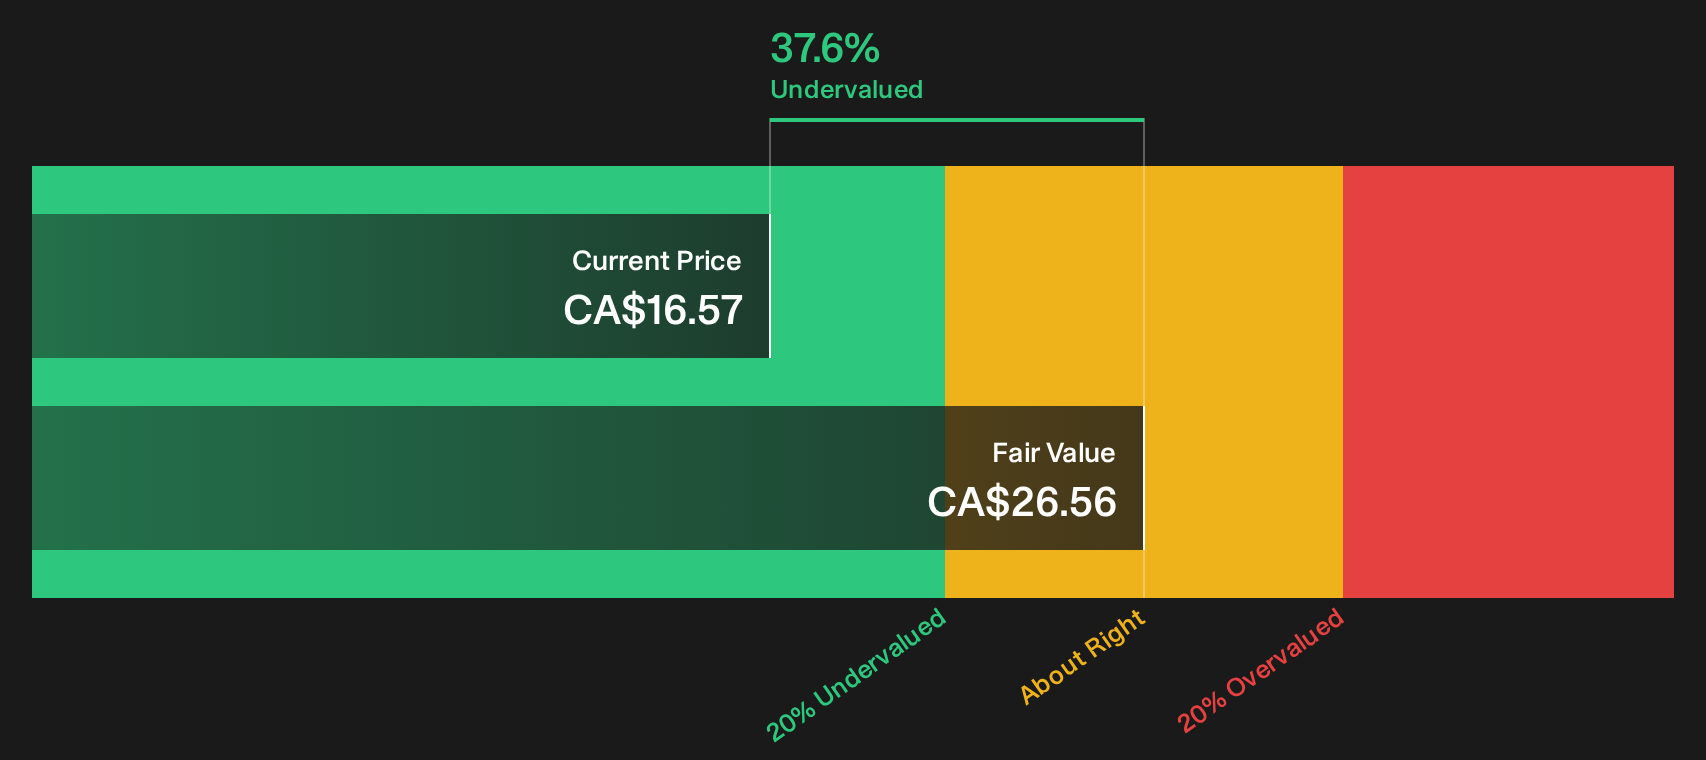
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Crombie Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Crombie Real Estate Investment Trust story so far. If that leaves you on the fence, move quickly and test the numbers, including the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Crombie Real Estate Investment Trust?
If Crombie Real Estate Investment Trust leaves you undecided, broaden your watchlist now. Testing other opportunities side by side can sharpen your judgment and reduce blind spots.
- Target stronger potential value by lining up companies that screen as higher quality and trading below estimated worth using the 6 high quality undervalued stocks.
- Prioritise reliable income streams by comparing businesses offering higher yields with sturdier payout profiles through the 3 dividend fortresses.
- Focus on financial resilience by filtering for companies with cleaner balance sheets and steadier fundamentals via the list of solid balance sheet and fundamentals (5 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com