


EN
Tenet Healthcare (THC) Stock Looks Below Fair Value On Current Earnings
Tenet Healthcare has been on a powerful multi year run, and with the share price now well above earlier levels, investors are asking whether the current valuation still lines up with the company’s earnings profile. The focus has shifted from the move in the chart to a simpler question for holders and potential buyers alike: what exactly are you paying for in terms of profits today?
- Over the past 3 years the stock has returned about 4.4x, which puts a lot of weight on whether the underlying earnings can support that kind of repricing.
- Recent updates around higher profitability and expectations for stronger earnings may support a view that Tenet Healthcare’s margin structure and cash generation have changed meaningfully compared with a few years ago.
- There is a second opinion on Tenet Healthcare worth weighing. See what analysts think Tenet Healthcare's shares could be worth.
For investors, the debate is whether Tenet Healthcare’s current share price is adequately backed by the earnings it is producing today and is expected to produce over time.
If you want to test the same earnings based question you are asking of Tenet Healthcare across a wider field, run the numbers against 42 high quality undervalued stocks.
Is Tenet Healthcare Still Cheap on Earnings?
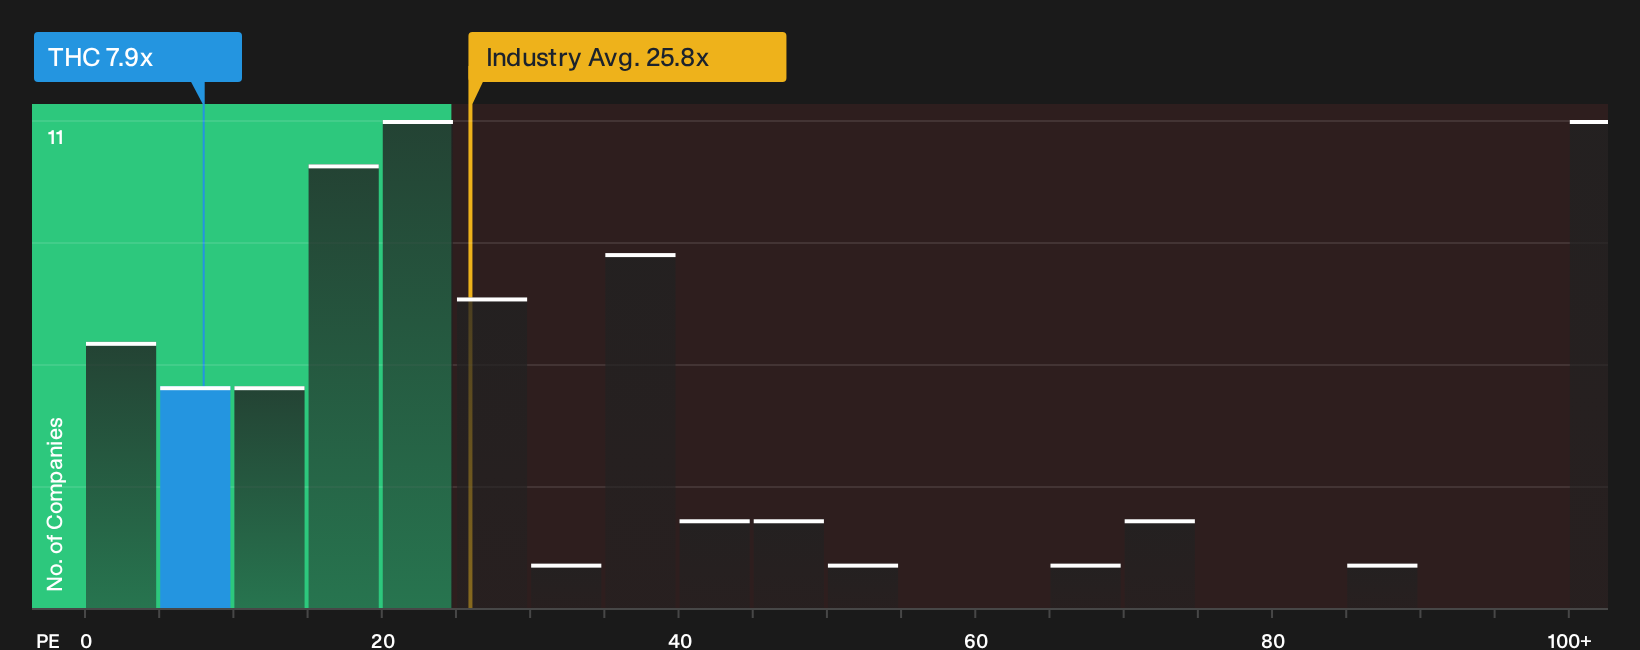
The P/E ratio is a straightforward way to link Tenet Healthcare’s share price to the profits it is generating. On this measure, the stock trades on roughly 7.9x earnings, compared with a Healthcare sector average of about 25.8x and a peer group closer to 21.3x, which places Tenet Healthcare on a much lower earnings multiple than many similar businesses.
Because the P/E that would typically be expected for Tenet Healthcare, after factoring in its margins, growth profile, size and risk, sits higher than today’s 7.9x level, the shares screen as undervalued on this framework. Despite the recent earnings guidance upgrade and stronger sentiment around high acuity procedures, the P/E still leaves the stock pricing in a discount to both the industry and that tailored benchmark. This is what the detailed valuation model behind this article is designed to quantify further. Explore the numbers behind Tenet Healthcare's P/E valuation.
The Tenet Healthcare Narrative: What Would Justify Today's Price?
Tenet Healthcare’s Simply Wall St Narratives pick up where this valuation puzzle leaves off and spell out what would need to happen to growth, margins and earnings for the stock to be worth clearly more or clearly less than today’s price, all housed on the Community page. Each one treats Tenet Healthcare’s implied worth as a hypothesis about how the business might develop. You can revisit that hypothesis over time as new information comes through.
Community views on Tenet Healthcare split between investors who see more earnings power left in the model and others who think expectations already run hot.
Bull case: 14% undervalued
"Technology, automation, AI and the global business center model that have already reduced certain analytics costs by about 60% can be applied more broadly across hospital and Conifer workflows..."
Discover why this Narrative puts Tenet Healthcare at 14% undervalued.
Bear case: 19% overvalued
"From an investor’s standpoint, integrated behavioral care isn’t just a social good, it’s a margin story..."
Explore why this Narrative puts Tenet Healthcare at 19% overvalued.
One more piece of the Tenet Healthcare puzzle
Valuation work answers what you are paying today, but the missing piece is how professional analysts currently map out Tenet Healthcare’s earnings profile a few years from now and how that compares with this price. Explore where analysts expect Tenet Healthcare to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com