


EN
Does Restaurant Brands International (QSR) Stock Trade At A Premium?
Restaurant Brands International has delivered a strong share price run over the past few years, so the key issue now is whether the cash it can generate really supports where the stock trades today. With investors reacting to fresh headlines around Burger King, Tim Hortons and Popeyes, the question is how that operating story translates into long term cash flows that justify the current market value.
- Over the past 5 years the stock has returned 64.3%, which puts real pressure on the underlying cash flow profile to keep backing that kind of compounding performance.
- Recent profit growth, solid system wide sales gains and continued dividends and buybacks suggest management is leaning on mature brands to convert earnings into cash that may support the current valuation over time.
- What if you looked at Restaurant Brands International through its earnings instead? See why Restaurant Brands International's 16.9x P/E tells a different valuation story.
The stock's next move may depend on whether those future cash flows, when valued using a Discounted Cash Flow (DCF) approach, line up with where Restaurant Brands International now trades in the market.
If you are questioning whether Restaurant Brands International's recent 64.3% five year return is properly supported by its cash flows, it can help to compare that same cash flow lens across 42 high quality undervalued stocks.
Does Restaurant Brands International Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) approach here takes Restaurant Brands International's current cash generation and projects it forward in two stages. Latest twelve month free cash flow sits at about $1.57b, and the model expects that pool of cash to keep growing from just over $2.0b in 2027 to a higher level by 2036, with the growth rate easing off over time as the business matures.
Those projections leave the DCF estimate broadly in line with the current share price of $78.55, which suggests the market is already baking in steady, long run conversion of earnings into cash. Because Burger King's recent same store sales strength and Tim Hortons' loyalty partnerships are already in the headlines, that momentum helps explain why the price closely tracks what this cash flow view implies. To see the full assumptions behind that valuation and how it compares with other stocks, you can check the detailed intrinsic value breakdown for Restaurant Brands International. Find out what Restaurant Brands International could be worth using our Discounted Cash Flow (DCF) estimate.
The Restaurant Brands International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Restaurant Brands International valuation puzzle leaves off and spell out which assumptions about future growth, margins and earnings would need to hold for the shares to look meaningfully higher or lower than today. Rather than focusing on a single multiple or model point estimate, each scenario lays out the building blocks behind its suggested value so you can weigh those inputs against Restaurant Brands International's actual results as they are reported.
One of the top community narratives on Restaurant Brands International: 9% undervalued
"Rapid international expansion through a largely franchise-led model, including the plan for about 1,800 net new restaurants by 2028..."
Discover why this Narrative puts Restaurant Brands International at 9% undervalued.
One more angle on Restaurant Brands International that could reshape your view
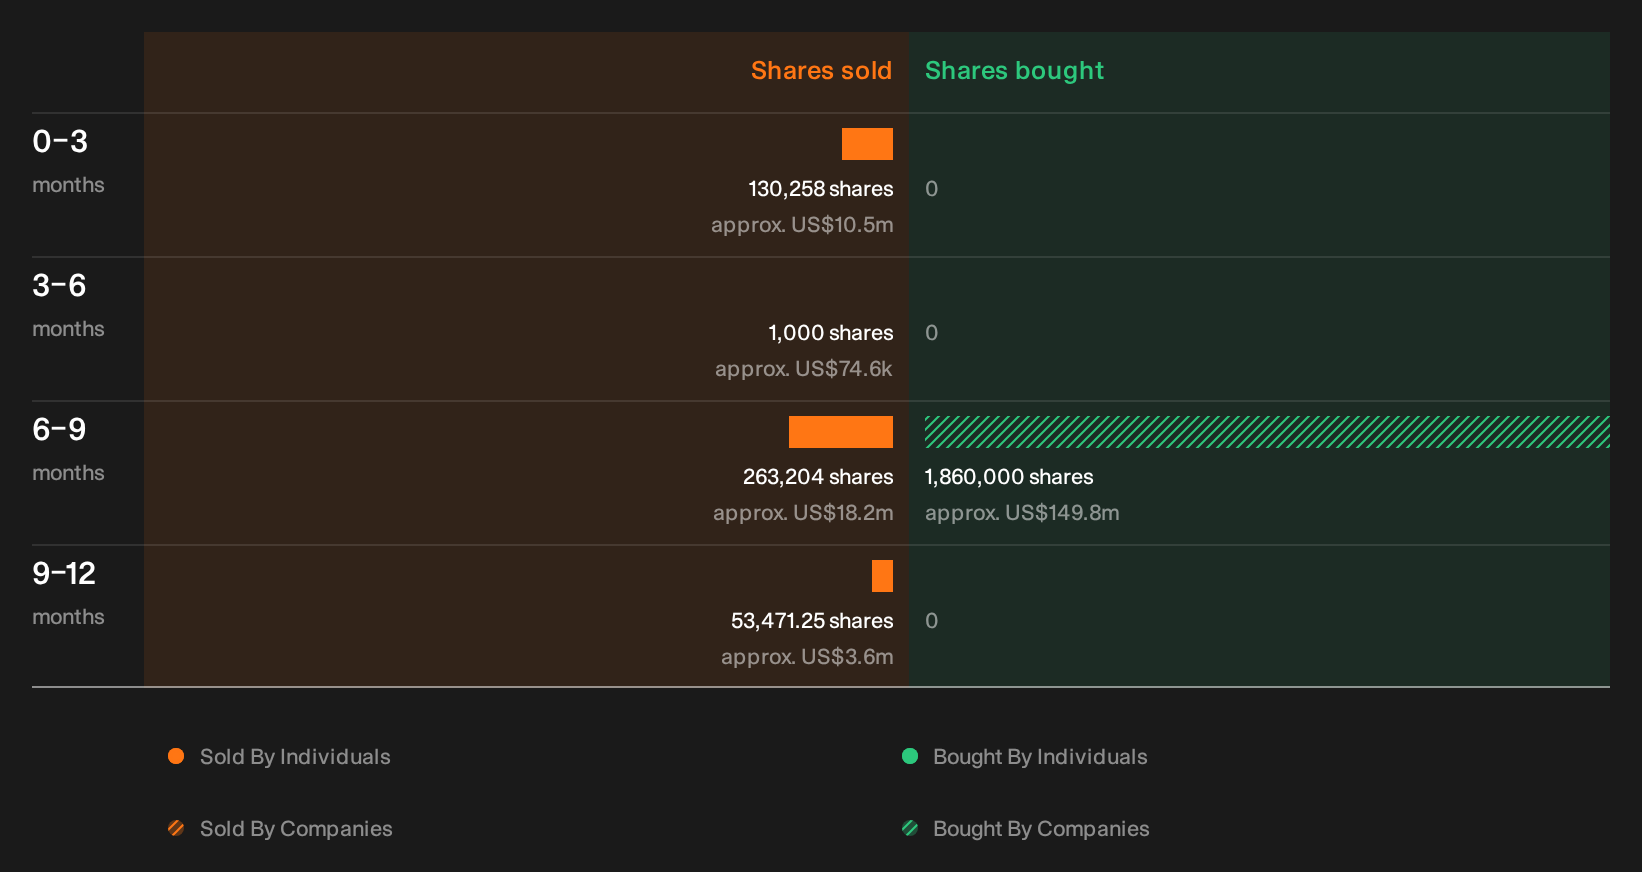
Cash flows and narratives tell only part of the story for Restaurant Brands International, because the recent activity by people inside the business can send a very different signal about risk and reward. See the recent insider selling flagged for Restaurant Brands International.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com